Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Mortgage Rates Today: Rates Drop Following Trump’s $200 Billion Mortgage Bond Directive

January 9, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you’re thinking about buying a home or refinancing your current mortgage, you’re probably wondering what today’s mortgage rates are doing. Well, here’s the quick answer: they’ve taken a dip! As of Friday, January 9, 2026, we’re seeing average 30-year fixed rates drop below 6% for the first time in a while. This is a big deal, and it’s largely thanks to some recent government action.

Mortgage Rates Today: Rates Drop Following Trump’s $200 Billion Mortgage Bond Directive

It feels like just yesterday we were all talking about rates hovering in the 6%-plus range, and now seeing them officially under 6% is a breath of fresh air for many aspiring homeowners and those looking to optimize their existing loans. My own experience in this market has taught me that even small shifts can make a huge difference when you’re talking about hundreds of thousands of dollars over 30 years. The average for a 30-year fixed mortgage is currently sitting around 6.0% to 6.2%, though depending on your specific situation and the lender you choose, you might find even better deals.

What's Driving This Big Drop?

You might be asking, “How did we get here so suddenly?” The main driver behind this welcome change is a pretty bold move by the Trump administration. President Trump has directed government-sponsored enterprises, Fannie Mae and Freddie Mac, to purchase a whopping $200 billion in mortgage bonds.

Why Does Buying Mortgage Bonds Matter?

Think of it like this: when the government steps in to buy more mortgage bonds, it increases the demand for them. When demand for something goes up, its price tends to go up, and its yield (which is essentially what lenders earn) tends to go down. For us as borrowers, a lower yield on mortgage bonds translates directly into lower mortgage interest rates. It's a direct intervention aimed at making owning a home more affordable, which is fantastic news for a lot of people.

Mortgage News Daily reported a significant intraday drop to 5.99% this morning for the 30-year fixed rate, down from 6.21% just yesterday. That kind of single-day movement is rare and truly shows the market's powerful reaction to this intervention.

A Closer Look at Today's Rates

While the headline news is exciting, it’s always good to have a clearer picture of the different types of mortgages. Here's a breakdown of what we're seeing on average:

Product Average Interest Rate Average APR
30-Year Fixed 6.16% 6.22%
15-Year Fixed 5.47% 5.56%
30-Year Fixed FHA 5.80% 5.86%
30-Year Fixed VA 6.24% 6.28%

(Note: APR, or Annual Percentage Rate, typically includes fees and other costs associated with the loan, so it's usually a bit higher than the interest rate itself. It’s a more complete picture of the cost of borrowing.)

You can see that FHA loans, often used by first-time homebuyers, are also benefiting from this downward trend, coming in below the general 30-year fixed rate. VA loans, a great benefit for our veterans, are also slightly higher but still reflect the broader market movement.

What's Next? The Crystal Ball on Mortgage Rates

So, now that rates have dipped below 6%, what's the forecast for the rest of 2026? This is where things get a bit nuanced. While this recent drop is significant, most experts believe that rates won't go on a freefall. They're expected to gradually decline throughout the year.

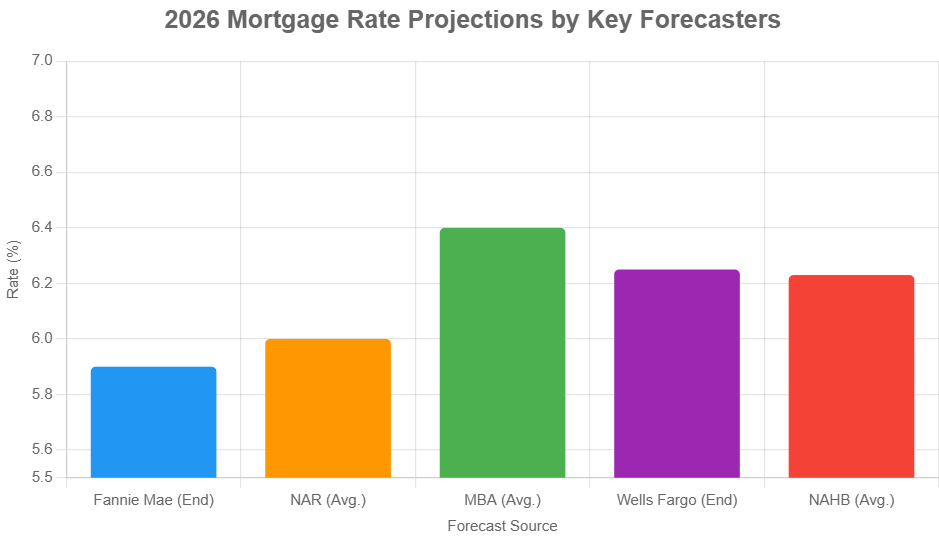
Major housing organizations have released their year-end predictions, and they largely agree on this gradual decrease. Here’s a peek at what some of them are saying:

2026 Mortgage Rate Forecasts

Organization 2026 Year-End Prediction 2026 Q1/Q2 Outlook
Fannie Mae 5.9% 6.2% (Q1) / 6.1% (Q2)
National Association of Realtors (NAR) 6.0% 6.0% (Q1)
National Assoc. of Home Builders (NAHB) 6.2% 6.17% (Q1)
Wells Fargo 6.25% 6.15% (Q1 & Q2)
Mortgage Bankers Association (MBA) 6.4% 6.4% (Q1 & Q2)

As you can see, the consensus is that rates will likely stay in the low 6% to high 5% range for much of the year. Fannie Mae is the most optimistic with a year-end prediction of 5.9%, while others are a bit more conservative. It’s important to remember these are predictions, and the market can surprise us.

The Key Factors Shaping Tomorrow's Rates

A few major forces are at play that will continue to influence mortgage rates:

  • Government Bond Purchases: As we’ve seen, the government's plan to buy $200 billion in mortgage bonds is a powerful tool. Analysts believe this move could help keep rates around 6.0% or even lower in the short term, offering some stability.
  • The Federal Reserve's Next Moves: The Federal Reserve has been pretty active, with three rate cuts in late 2025. However, they're expected to be more cautious in 2026. The general feeling is that we might see only one additional rate cut for the entire year. This cautious approach by the Fed can put a bit of upward pressure on rates, preventing them from dropping too dramatically.
  • Economic Indicators – The Tale of Inflation and Jobs: The economy is a constant balancing act. Right now, there are ongoing concerns about inflation that’s proving a bit stubborn and a labor market that’s surprisingly strong. These factors can push rates back up a bit, preventing them from sinking too far below the 6% mark for extended periods. We’re keeping a close eye on the jobs report released today, as these numbers can really move the needle on interest rates. Last month's report showing slower-than-expected inflation certainly helped push rates down.

My Take: Is Now the Time to Buy or Refi?

From my perspective in the market, this period feels like a prime opportunity. The government intervention has created a temporary window of lower rates. If you've been on the fence about buying a home, this could be the moment to make your move. The lower interest rate means you could qualify for a larger loan amount or simply have a more manageable monthly payment.

For those looking to refinance, especially if you have an older mortgage with a rate significantly higher than today's offerings, the savings could be substantial. Even if rates only dip a bit further, locking in a rate in the high 5% or low 6% range, compared to say, 7% or 8% from a year or two ago, can save you tens of thousands of dollars over the life of your loan.

It’s also worth noting that while rates are dropping, home prices are still expected to creep up. Most experts predict home prices might rise by about 1% to 4% this year, depending on your local market. This means that the savings from lower mortgage rates might be partially offset by rising home values. So, it's a good idea to weigh both factors when making your decision.

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Today’s Mortgage Rates, Jan 9: Low 6% Range Persists, Experts Predict Continued Stability

January 9, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As we kick off the first full week of 2026, the news for homebuyers and homeowners looking to refinance is overwhelmingly one of stability. Today, January 9, 2026, the national average for a 30-year fixed mortgage rate hovers around 6.16%, showing very little movement from the previous week. This steadiness, while perhaps not thrilling, is actually good news for those of us watching the market, as it signals a more predictable environment for big financial decisions like buying a home.

It's a welcome change from the roller-coaster ride we experienced over the past few years. I remember just over a year ago, the average 30-year fixed was sitting at a much higher 6.93%. That’s a significant difference, and it represents hundreds of dollars in monthly savings for borrowers.

Today's Mortgage Rates, Jan 9: Low 6% Range Persists, Experts Predict Continued Stability

What the Numbers Tell Us This Week

Let's break down what the latest data from Freddie Mac and Zillow is telling us about mortgage rates on January 9, 2026.

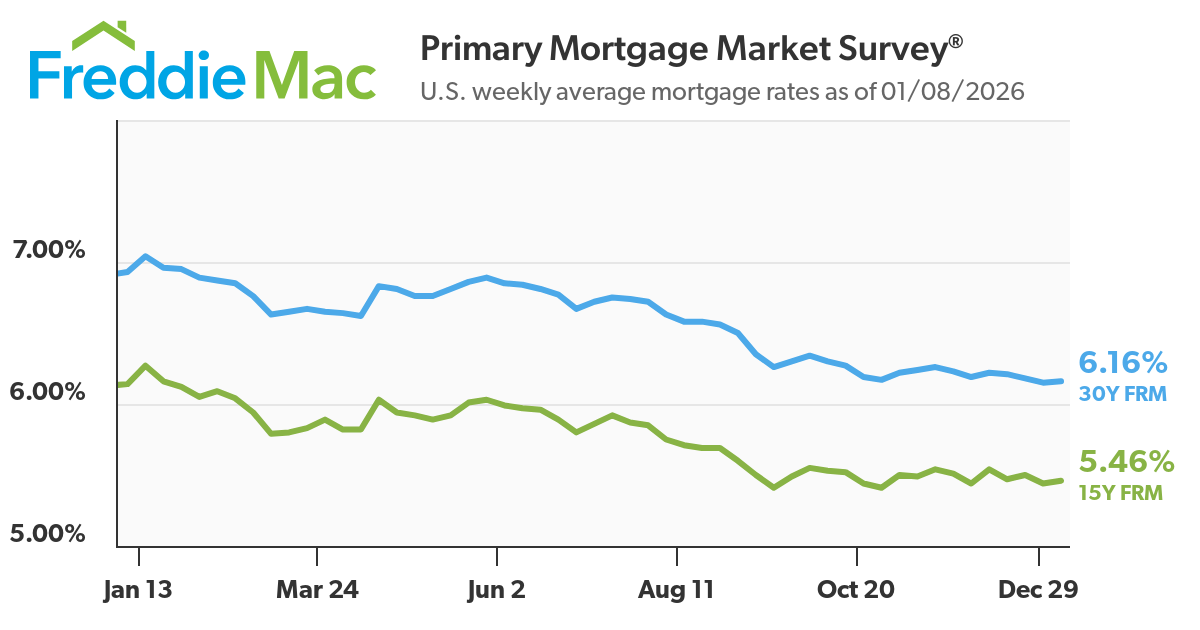
According to Freddie Mac, which tracks average rates weekly, the 30-year fixed-rate mortgage averaged 6.16% this week, a slight increase of just one basis point (0.01%). The 15-year fixed-rate mortgage is at 5.46%, up two basis points from last week. While these are small upticks, it’s important to remember where we were a year ago: the 30-year fixed was at 6.93% and the 15-year fixed at 6.14%. This year-over-year drop of nearly three-quarters of a point for the 30-year is substantial and has clearly opened doors for more people looking to buy.

Zillow's data, which often reflects slightly more current, day-to-day rates, gives us a snapshot of popular loan options:

Current Mortgage Rates (Data – Jan 9, 2026)

Loan Type Interest Rate
30-year fixed 6.05%
20-year fixed 5.98%
15-year fixed 5.48%
5/1 ARM 6.32%
7/1 ARM 6.53%
30-year VA 5.55%
15-year VA 5.16%
5/1 VA 5.37%

Note: These are national averages and have been rounded. Rates can vary based on your credit score, down payment, and lender.

You can see from Zillow's numbers that the 30-year fixed is just slightly lower than Freddie Mac's reported average, around 6.05%. This aligns with Freddie Mac's observation that rates are “hovering close to the 6% mark.” I find these micro-differences fascinating because they highlight how individual lenders might be competing or adjusting their offerings based on their own projections and business goals.

Refinancing: Still an Attractive Option

For those of you who already own a home, the refinance market is also seeing similar stability.

Current Mortgage Refinance Rates (Data – Jan 9, 2026)

Loan Type Interest Rate
30-year fixed 6.12%
20-year fixed 5.94%
15-year fixed 5.60%
5/1 ARM 6.32%
7/1 ARM 6.45%
30-year VA 5.47%
15-year VA 5.10%
5/1 VA 5.32%

Refinancing your mortgage can be a smart move if you can secure a lower interest rate than you have now. Even a small drop can save you thousands over the life of your loan, and it can allow you to shorten your loan term or even tap into your home’s equity. The rates for refinancing are very similar to purchase rates, which is typical when the market is this stable.

What’s Driving This Stability and What's Next?

Sam Khater, Freddie Mac's Chief Economist, hit the nail on the head when he said, “The combination of solid economic growth and lower rates has led to improving momentum in for-sale residential demand, with purchase applications up over 20% from a year ago.” This is a crucial point I want to emphasize. Unlike times when rates might be high and the economy sluggish, we're seeing a healthier balance.

Here are the key factors influencing mortgage rates right now, and what I'm watching:

  • The 10-Year Treasury Yield: This is a big one. Mortgage rates are closely tied to the yields on U.S. Treasury bonds, particularly the 10-year. When these bond yields go up, mortgage rates tend to follow, and vice versa. Investors are constantly assessing the economic outlook to decide where to put their money, and this directly impacts borrowing costs.
  • Inflation Trends: The Federal Reserve's primary goal is to keep inflation in check. If inflation is cooling, the Fed is less likely to raise interest rates, which usually means mortgage rates can stay steady or even fall. We saw a peak in inflation a couple of years ago, and while it's come down, any signs of it creeping back up would concern the Fed and potentially push rates higher.
  • The Labor Market: A strong job market usually signals a healthy economy, which can sometimes put upward pressure on inflation. However, a too-hot job market can also make the Fed nervous about inflation. Conversely, some weakening in the labor market (without causing a recession) might actually be good for mortgage rates, as it could signal that inflationary pressures are easing.
  • Federal Reserve “Wait and See”: The Fed doesn't directly set mortgage rates, but its actions and pronouncements about interest rates heavily influence them. For a while now, the Fed has been signaling a pause in rate hikes, and the market has been anticipating potential cuts in the future. This “wait and see” attitude from the Fed has contributed to mortgage rates staying within a relatively tight band since late last year.

From my perspective, this period of stability is a breath of fresh air for potential buyers. The uncertainty of rapidly rising rates can be paralyzing. Now, buyers can plan with more confidence, knowing that their monthly payments are less likely to change dramatically from one week to the next. The over 20% jump in purchase applications that Freddie Mac noted is a direct result of this, and I expect that momentum to continue if rates hold steady.

Looking Ahead: The 2026 Forecast

What does the rest of 2026 hold for mortgage rates? Most experts, including those at Zillow, are predicting that rates will likely stay in the low-6% range throughout the year. There’s even a possibility they could dip below 6% if we see continued easing in inflation or some softening in the labor market.

It’s a far cry from the eye-watering peak of nearly 7.79% we saw in late 2023 for the 30-year fixed. The significant rate cuts by the Federal Reserve in late 2025 certainly helped bring us down to current levels. However, it's worth remembering that rates today are still more than double the historic low of 2.65% seen in January 2021. That period of ultra-low rates was an anomaly, and the current environment, while higher, is more reflective of a balanced economy.

As we move further into the new year, all eyes will be on upcoming economic data releases, especially the jobs report. These reports often act as catalysts for market movements. So, while stability is the theme today, it’s always wise to stay informed and agile!

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, Jan 9: 30-Year Refinance Rate Goes Down by 13 Basis Points

January 9, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Good news for homeowners looking to refinance! As of today, January 9th, the national average for a 30-year fixed refinance rate has dipped by 13 basis points, now sitting at a stable 6.49%. This welcome decrease from last week's average of 6.62% means that if you've been on the fence about refinancing, now might be a smart time to explore your options and potentially lower your monthly payments.

Mortgage Rates Today, Jan 9: 30-Year Refinance Rate Goes Down by 13 Basis Points

What Does a 13 Basis Point Drop Really Mean for Your Wallet?

It might sound like a small number, but that 13 basis point (or 0.13%) drop can make a real difference, especially when you're talking about the large sums involved in a mortgage. Think about it this way: if you have a mortgage of, say, $300,000, a drop from 6.62% to 6.49% could save you a noticeable amount each month. Over the life of the loan, these savings can really add up. It's not just pocket change; it can be enough to handle other financial goals or simply ease your monthly budget. This is why keeping an eye on these mortgage rate shifts is so important to anyone holding an existing home loan.

Today's Mortgage Rate Snapshot: Beyond the 30-Year Refi

While the 30-year fixed refinance rate is making headlines, it's always helpful to see how other loan types are performing. Here's a quick look at where things stand today, according to Zillow:

Loan Type Average Rate (Jan 9, 2026) Change from Previous Week
30-Year Fixed Refinance 6.49% Down 13 Basis Points
15-Year Fixed Refinance 5.56% Stable
5-Year Adjustable-Rate (ARM) Refinance 7.11% Stable

As you can see, while the 30-year refinance is getting a bit cheaper, the rates for 15-year fixed refinances and 5-year ARMs are holding steady. This means the benefit of the current rate drop is most directly felt by those looking to extend their repayment period or swap out a higher-interest loan for a new 30-year one.

Fixed-Rate vs. Adjustable-Rate Refinancing: Which Path is Right for You?

Choosing to refinance is a big decision, and one of the first forks in the road is deciding between a fixed-rate mortgage and an adjustable-rate mortgage (ARM).

  • Fixed-Rate Mortgages: When I think about fixed-rate loans, I picture stability. Your interest rate, and therefore your monthly principal and interest payment, stays the same for the entire life of the loan. This offers predictability and makes budgeting much easier. For someone who plans to stay in their home for a long time or likes the security of knowing exactly what their payment will be, a fixed-rate mortgage is usually the way to go.
  • Adjustable-Rate Mortgages (ARMs): ARMs, on the other hand, start with an introductory fixed rate for a set period (often 5, 7, or 10 years). After that initial period, the interest rate can adjust periodically based on market conditions. This can be attractive if you plan to move or refinance again before the initial fixed period ends, as ARM rates are often lower initially than fixed-rate options. However, there's always the risk that rates could rise significantly after the fixed period, leading to higher monthly payments. It's a bit of a gamble, but can pay off if you manage it correctly.

Understanding the Nuances of Adjustable-Rate Mortgages

Beyond the basic fixed vs. ARM choice, it’s worth diving a little deeper into ARMs. The most common type you'll see for refinancing is often a 5/1 ARM. This means the rate is fixed for the first 5 years, and then it adjusts annually (the “1”). When that adjustment period kicks in, your rate will be tied to a specific financial index, plus a margin.

Key things to remember about ARMs:

  • Initial Rate Advantage: They usually offer a lower starting rate compared to a 30-year fixed.
  • Risk of Rate Increases: After the initial period, your rate could go up. Most ARMs have rate caps that limit how much your rate can increase at each adjustment and over the life of the loan, but your payment could still become substantially higher.
  • Who They're For: ARMs are best suited for borrowers who can comfortably handle potential payment increases, plan to sell or refinance before the adjustment period, or expect interest rates to fall in the future.

How Your Loan-to-Value (LTV) Ratio Affects Refinancing

Another crucial factor that lenders consider when you're looking to refinance is your Loan-to-Value (LTV) ratio. This simply compares the amount you owe on your mortgage to the current market value of your home.

  • High LTV (e.g., 80% or more): If you owe a significant portion of your home's value, you might face a higher interest rate or lenders might require you to pay for Private Mortgage Insurance (PMI) on a refinance, just like you might have done on your original purchase loan.
  • Low LTV (e.g., 80% or less): Borrowers with lower LTVs are generally seen as less risky. This often translates to better interest rates and fewer (or no) fees. Many lenders consider an LTV of 80% or less ideal for refinancing without requiring PMI.

It's always worth getting a home appraisal to understand your current home's value and calculate your LTV accurately.

Don't Forget the Costs: Refinancing Isn't Always Free!

While the idea of lower monthly payments is incredibly appealing, it's vital to remember that refinancing comes with costs. These are often referred to as “closing costs,” and they can add up.

Common refinancing costs include:

  • Appraisal Fee: To determine the current market value of your home.
  • Title Search and Title Insurance: To ensure the property title is clear.
  • Origination Fees: Charged by the lender for processing the loan.
  • Credit Report Fee: To pull your credit history.
  • Recording Fees: Charged by your local government to record the new deed and mortgage.
  • Attorney Fees: In some states, an attorney is required.

When you're comparing different refinance offers, always ask for a Loan Estimate, which details all these fees. It’s crucial to calculate your “break-even point” – the point at which the savings from your lower monthly payment will offset the closing costs you paid. If you plan to sell your home before you reach that break-even point, refinancing might not be financially beneficial.

Recommended Read:

30-Year Fixed Refinance Rate Trends – January 8, 2025

Best Time to Refinance Your Mortgage: Expert Insights

Should You Refinance Your Mortgage Now or Wait Until 2026? 

Market Trends and What the Experts Are Saying About the Future

So, what's behind these rate movements, and what can we expect moving forward? From my perspective, it's a dynamic environment, and a lot of factors are at play.

  • Recent Volatility: We saw rates flirt with lows toward the end of last year, which was a relief for many. However, as is often the case, they've seen a slight uptick this week. For 30-year purchase mortgages, the average is currently around 6.16%. This shows that even though refinances are seeing some movement, the purchase market is also experiencing its own fluctuations.
  • The Fed's Shadow: Everyone in this space is watching the Federal Reserve very closely. Today, January 9th, is a key day because the December jobs report is expected. If unemployment ticks up, it could signal a weaker economy, which often leads the Fed to consider lowering interest rates. This, in turn, can send mortgage rates, especially for refinances, further down as the market anticipates those cuts.
  • 2026 Outlook: Steady as She Goes? Looking ahead to the rest of 2026, most seasoned analysts are predicting a year of relative stability rather than wild swings. While some optimists foresee rates potentially dipping towards 5.5% by mid-year, the Mortgage Bankers Association has a more conservative outlook, expecting rates to hover around 6.4% for much of the year. This prediction is based on the assumption of continued steady economic growth, which tends to keep rates from plummeting.
  • Refinance Activity is Booming: It's really interesting to see that refinancing now makes up more than half of all mortgage activity. This is a clear sign that a lot of homeowners who locked in higher rates (think 7% or 8%) in 2023 and 2024 are actively seeking opportunities to refinance and gain some financial breathing room. The current drop in the 30-year refi rate is a clear invitation for many of these homeowners to explore their options.

Key Takeaways for Your Refinance Journey

To wrap things up, here are the most important things to remember from today's mortgage rate news:

  • The 30-year fixed refinance rate is down 13 basis points to 6.49% as of January 9th, according to Zillow.
  • This drop offers a tangible opportunity to lower your monthly mortgage payment.
  • When considering a refinance, weigh the pros and cons of fixed-rate versus adjustable-rate mortgages.
  • Be aware of refinancing costs and calculate your break-even point.
  • Your Loan-to-Value (LTV) ratio significantly impacts the rates you'll be offered.
  • Keep an eye on economic indicators like the jobs report and Federal Reserve statements, as they influence future rate movements.

Navigating the mortgage market can feel complex, but staying informed about these daily changes can empower you to make the best financial decisions for your home and your future.

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

With interest rates and housing policies shaping affordability, 2026 offers investors a pivotal chance to lock in cash‑flowing rental properties.

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Talk to a Norada investment counselor today (No Obligation):
(800) 611-3060

Get Started Now

Recommended Read:

  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Flipping, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Mortgage Rates Near 2025 Lows Signal a Shift Towards Better Affordability

January 9, 2026 by Marco Santarelli

Mortgage Rates Near 2025 Lows Signal a Shift Towards Better Affordability

As we kick off 2026, the news for anyone looking to buy a home is decidedly positive: mortgage rates are hovering near their 2025 lows, signaling a welcome shift towards better affordability.

This is what I've been feeling in my bones as someone who watches the housing market every single day. We saw the 30-year fixed mortgage rate begin 2025 well above 7%, and after a bit of a rollercoaster ride, it settled into the low 6% range as the year wrapped up. Now, as we step into the new year, Zillow is predicting a continued, albeit gradual, descent toward the 6% mark by the close of 2026. It's not a dramatic drop, but for anyone trying to make homeownership a reality, these gradual improvements are huge wins.

Mortgage Rates Near 2025 Lows Signal a Shift Towards Better Affordability

A Look Back: How Rates Traveled in 2025

To truly appreciate where we are today, it's helpful to remember the journey mortgage rates took over the past year. Think of it like this:

  • The Start of 2025: We began the year with rates feeling a bit daunting, hovering above the 7% mark. In fact, the third week of January saw a yearly peak of 7.04%. That felt like a tough pill to swallow for many aspiring homeowners.
  • Mid-Year Stability (of sorts): For a good chunk of the first half of 2025, rates stayed somewhat elevated, often circling around 6.7%. It wasn't the sky-high territory of the start of the year, but it still made borrowing a significant expense.
  • The Late-Year Downward Trend: The real change began around September. This was when the Federal Reserve started making moves, initiating a series of rate cuts. This proactive step had a tangible effect, nudging mortgage rates noticeably lower.
  • End of 2025 Low: By the final day of 2025, the average 30-year fixed rate had fallen to 6.15%. This represented a significant drop of about 0.85 percentage points from where we started the year. More importantly, it brought a sense of stability back to the market, which, in turn, boosted affordability for potential buyers.

Why the Resistance at 6%?

Now, why aren't rates just plummeting to, say, 5% or even lower? From my perspective, it’s a delicate balancing act in the economy. We're seeing a slowing labor market, which would normally signal lower rates. However, there's a persistent concern about stubborn inflation. These two opposing forces are like a tug-of-war, making it tough for rates to break through that 6% floor decisively.

The upcoming December Bureau of Labor Statistics (BLS) employment report, hitting the stands on January 9th, is a big deal. It’ll be our first clear snapshot of the labor market’s health since a recent government hiccup, and it will definitely shed light on which way this tug-of-war might be leaning.

The Impact on the Housing Market in 2026

So, what does this mean for you if you're dreaming of homeownership this year? 2026 is shaping up to be a year of small, but meaningful, wins.

  • Improved Affordability: Even though Zillow is forecasting only moderate declines in borrowing costs, the good news is that affordability is set to gradually improve. As home values see modest increases – meaning they aren't skyrocketing at the pace we've seen recently – household incomes have a chance to catch up. This wider gap between incomes and home prices means more people will be able to qualify for a mortgage and enter the buyer's pool.
  • A Significant Milestone: If the current trends hold true, we might just reach a major milestone by the end of 2026: the typical home could once again be affordable to the median household. This is a big deal after several years where homeownership felt like a luxury many could no longer afford.
  • “Small Wins” That Add Up: While we're not looking at a flood of super-low rates, these gradual improvements in borrowing costs are exactly what many shoppers have been waiting for. After a period of stretched affordability, these consistent, albeit modest, positive shifts are incredibly welcome.

Expert Forecasts for the End of 2026

It's always smart to see what the experts are saying. While my own observations align with the general trend, others have their predictions too. Here’s a quick rundown of what some leading housing authorities anticipate for the end of 2026:

Forecaster Predicted 30-Year Fixed Mortgage Rate (End of 2026)
Zillow Around 6.0%
Fannie Mae Approximately 5.9%
Bankrate Bouncing around 6.0%, potentially as low as 5.5%
Realtor.com 6.3%
Mortgage Bankers Assoc. Holding steady at 6.4%

Key Takeaways from the Experts:

  • Moderation, Not a Crash: The consensus is clear: we're not likely to see a return to the ultra-low 3% rates we experienced during the pandemic. Instead, expect rates to remain comfortably below the 2025 high of over 7%.
  • The Economic Tightrope: The actual path of mortgage rates will be heavily influenced by what happens with inflation, the strength of the labor market, and the Federal Reserve's policy decisions. Any further rate cuts will, of course, play a significant role.
  • Affordability is Key: The combined effect of these moderating rates, alongside modest home price growth and rising incomes, is where the real story is. This is what's projected to finally bring the typical home within reach of the median household once again as 2026 draws to a close.

As a seasoned observer of this market, I feel a sense of cautious optimism. The challenges of affordability have been significant, and it's heartening to see tangible signs of improvement on the horizon. The gradual descent of mortgage rates, coupled with a stabilizing housing market, presents a real opportunity for a growing number of people to achieve their homeownership dreams in 2026.

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates

Mortgage Rates Remain Stable Fueling Buyer Demand in 2026

January 9, 2026 by Marco Santarelli

Mortgage Rates Remain Stable Fueling Buyer Demand in 2026

It's a breath of fresh air for many aspiring homeowners: stable mortgage rates are starting to bring buyers back into the housing market in 2026, signaling a positive shift after a period of uncertainty. The good news is that rates have settled into a more predictable pattern, and this stability is encouraging more people to start looking for their dream homes.

For what feels like ages, the housing market has been a bit of a rollercoaster. We saw rates skyrocket, making it tough for many to even consider buying a home. But as we've moved into 2026, things are starting to feel different. The numbers coming out from Freddie Mac's Primary Mortgage Market Survey® paint a promising picture.

Mortgage Rates Remain Stable Fueling Buyer Demand in 2026

What's Driving This Shift?

The main reason we're seeing this change is that mortgage rates have found a comfortable spot, hovering around the 6% mark. This isn't just a small dip; it's a significant drop from where we were just last year. For example, as of January 8, 2026, the 30-year fixed-rate mortgage averaged 6.16%. To put that into perspective, just a year ago, that same mortgage averaged a much higher 6.93%. That difference might not sound huge in daily talk, but over the life of a loan, it can mean tens of thousands of dollars in savings. And that’s enough to make a real difference for a family.

It's not just about the lower rates, though. We're also seeing the economy holding up pretty well. This combination of lower borrowing costs and solid economic growth is like a double shot of espresso for the housing market. It’s giving people the confidence and the means to start seriously considering a purchase.

The Numbers Don't Lie: A Look at the Data

Freddie Mac has been tracking these trends, and their data is eye-opening. In the first week of the new year, purchase applications – which are a good indicator of how many people are actively looking to buy a home – were up over 20% from this time last year. That's a significant jump and suggests that buyers who were sitting on the sidelines are now stepping back into the game.

Let's break down some of the key figures from Freddie Mac's Primary Mortgage Market Survey® for the U.S. weekly averages as of January 8, 2026:

Mortgage Type Average Rate (01/08/2026) 1-Week Change 1-Year Change Estimated Monthly Savings (vs. 1 Yr Ago*)
30-Yr Fixed FRM 6.16% +0.01% -0.77% Significant (Tens of Thousands)
15-Yr Fixed FRM 5.46% +0.02% -0.68% Substantial (Thousands)

*Note: This is a simplified illustration. Actual savings depend on loan amount and exact rate difference.

Looking at the year-over-year change is where you really see the impact. A drop of 0.77% for the 30-year fixed-rate mortgage and 0.68% for the 15-year fixed-rate mortgage means a lot more buying power for consumers. If you were looking to buy a $300,000 home, that 0.77% difference could translate to hundreds of dollars less each month. It’s like getting a bit of a discount that you didn't have before.

Stable Mortgage Rates Begin to Rekindle Purchase Demand in 2026
Source: Freddie Mac

Market Momentum and the Return of Buyers

This stabilization of rates around the 6% mark isn't just a minor blip; it's a catalyst. It's providing the predictability that buyers crave. For a long time, there was so much uncertainty about where rates were headed. Now, seeing them stay relatively steady makes it easier for people to plan their finances and make big decisions.

I've talked to a lot of people in the real estate industry, and the general feeling is that the market is starting to breathe again. We're seeing more open houses, more inquiries, and just a general buzz of activity that we haven't felt as strongly in a while. The experts are pointing to a few key factors:

  • Lower Borrowing Costs: As the numbers show, this is the most obvious driver. When your monthly mortgage payment goes down, you can afford more home or simply have more disposable income each month.
  • Resilient Economic Growth: A strong economy means people are more secure in their jobs and more confident about taking on a mortgage. It’s a sign that the fundamentals are sound enough to support homeownership.
  • Sidelined Buyers Returning: Many potential buyers had to put their plans on hold when rates were high. Now, with more favorable conditions, they're re-entering the market with renewed optimism.

Regional Differences and Future Outlook

While the national picture is encouraging, it's important to remember that real estate is local. We're hearing that areas in the Northeast, Midwest, and South are particularly showing improving conditions for first-time buyers. This could be due to slightly different local economic factors or housing inventory.

Looking ahead, forecasters from organizations like Fannie Mae and the Mortgage Bankers Association (MBA) are generally expecting these rates to stick around in the low 6% range for the first quarter of 2026. This suggests a period of sustained stability, which is music to the ears of anyone looking to buy.

Let's look at some expert projections for the average rate in 2026:

Source Projected Average Rate Key Driver
Fannie Mae 5.9% Gradual inflation cooling
Bankrate 6.1% Balancing Fed cuts vs. inflation risk
Redfin 6.3% Avoiding recession while inflation lingers
Mortgage Bankers Association (MBA) 6.4% Expectations of a single Fed cut in 2026

These different projections highlight the ongoing economic dance between managing inflation and supporting growth. But the overall consensus is that rates are likely to remain in a range that's much more manageable than we've seen recently. The difference between, say, 6.1% and 6.4% might seem small, but it can impact affordability significantly.

My Take on the Market

From my perspective, this period of stable mortgage rates is a welcome development. It’s fostering a healthier balance between buyers and sellers. For years, we saw prices soar partly because of low rates and high demand, with limited supply. Now, with rates settling, we might see a more sustainable pace of price growth, which is good for the long-term health of the market.

What’s crucial for potential buyers right now is to get pre-approved for a mortgage. Knowing exactly what you can afford is the first step. Then, work with a good real estate agent who understands your local market. Don't forget to factor in all the costs of homeownership, not just the mortgage.

This is an excellent time for those who have been dreaming of buying to really explore their options. The market is responding to affordability, and that's a powerful force. It feels like the housing market is finally finding its footing, and that's something to be optimistic about.

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates

Today’s Mortgage Rates, Jan 8: 30-Year Fixed Rate Goes Down Below 6%

January 8, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or refinancing your current mortgage, pay attention: as of January 8, 2026, the national average for a 30-year fixed mortgage rate is hovering right around 5.98%. This is a critical number, as it means we're not far from rates dipping below the significant 6% mark, which could open up new possibilities for many. While this rate offers a degree of affordability, it's crucial to understand the full picture, including how it compares to shorter loan terms and what it means for your wallet over time.

Today's Mortgage Rates, Jan 8: 30-Year Fixed Rate Goes Down Below 6%

Understanding Today's Mortgage Rate Environment

It’s an interesting time in the mortgage market. Rates have been inching closer to that 6% threshold for weeks, and today’s figures from Zillow show us right on its doorstep. For buyers, this means potentially more favorable borrowing costs compared to the recent past. For homeowners, it brings the possibility of refinancing to a lower rate, which can significantly impact monthly payments and overall interest paid. However, it's important to remember that these are national averages, and your specific rate will depend on many factors, including your credit score, down payment, the lender you choose, and even your geographic location.

Current Mortgage Rates: A Snapshot

Here’s a breakdown of the national averages for different types of mortgages as of January 8, 2026:

Loan Type Rate (%)
30-Year Fixed 5.98
20-Year Fixed 5.84
15-Year Fixed 5.41
5/1 ARM 6.11
7/1 ARM 6.34
30-Year VA 5.48
15-Year VA 5.06
5/1 VA 5.37
  • The 30-year fixed rate remains the most popular choice for many, offering stability and a predictable monthly payment. At 5.98%, it provides a level of comfort, though it does come with a higher total interest cost over the life of the loan.
  • The 15-year fixed rate at 5.41% is notably lower than its 30-year counterpart. This can be incredibly attractive for those who can comfortably afford a higher monthly payment, as it shaves off years from the loan term and can save you a substantial amount in interest.
  • Adjustable-Rate Mortgages (ARMs) like the 5/1 and 7/1 offer a lower initial rate, but come with the risk of future rate increases after the initial fixed period. They are often chosen by people who plan to sell or refinance before the adjustment period begins.

Refinance Rates: Should You Consider It?

If you're already a homeowner, the question often becomes: is it a good time to refinance? Here's what the refinance market looks like today:

Loan Type Rate (%)
30-Year Fixed 6.09
20-Year Fixed 5.81
15-Year Fixed 5.51
5/1 ARM 6.17
7/1 ARM 6.12
30-Year VA 5.60
15-Year VA 5.26
5/1 VA 5.51

Notice that refinance rates are generally a bit higher than purchase rates. This is common, as lenders often have different pricing for cash-out refinances or when an existing mortgage is being paid off. However, the gap isn't huge, and for many, the ability to lower their monthly payment or change their loan term could still make refinancing a smart move.

Putting the Numbers into Perspective: Monthly Payments

To truly grasp the impact of these rates, let’s look at some real-world examples. Imagine you're taking out a $300,000 loan.

Loan Type Interest Rate Term Length Monthly Payment*
30-Year Fixed 5.98% 360 months ~$1,790
15-Year Fixed 5.41% 180 months ~$2,450

*Payments shown are principal + interest only, excluding taxes and insurance.

What does this tell us?

  • By choosing the 30-year fixed at 5.98%, your monthly payment is more manageable at around $1,790. This makes it easier to fit into your budget right now. You get the benefit of a lower immediate payment and more breathing room in your cash flow.
  • However, opting for the 15-year fixed at 5.41% boosts your monthly payment significantly to about $2,450. That's an extra $660 per month. But, the trade-off is huge. You'll pay off your home much faster and save a massive amount on interest over the life of the loan.

The Long-Term Financial Impact: Lifetime Interest Cost

This is where things get really interesting, and frankly, where I always advise people to look beyond just the monthly payment. Let's do a quick comparison of the total interest paid over the life of the loan for that $300,000 loan:

  • 30-Year Fixed (5.98%): Over 30 years, you'd pay approximately $344,400 in interest. Add that to your principal, and you're looking at a total cost of around $644,400 for your home.
  • 15-Year Fixed (5.41%): By contrast, over 15 years, you'd pay roughly $151,000 in interest. That’s a staggering savings of over $193,000! The total cost for your home would be around $451,000.

These are estimates and can vary slightly based on exact closing dates and payment schedules.

My take: For many, even if the 15-year payment is a stretch, finding a way to make it work can be one of the smartest financial decisions they make. That extra $660 a month is a significant amount, but saving nearly $200,000 in interest over time is life-changing. It frees up so much more for retirement, investing, or simply enjoying life. However, if that higher payment truly puts a strain on your finances, the 30-year option is still a solid path to homeownership, especially with rates still hovering near 6%. It allows you to get into a home now, and you can always look into refinancing into a shorter term or making extra principal payments down the line if your financial situation improves.

What’s Driving Today's Mortgage Rates?

Understanding why rates are where they are adds another layer of insight. Zillow’s analysis points to a couple of key factors influencing the market in early 2026:

  • Seasonal Slowdown: We're currently in the post-holiday period, which historically sees a dip in mortgage application volume. This can sometimes create a temporary lull in demand, which could influence rates, though broader economic trends are usually more dominant.
  • Economic Factors: Inflation, Federal Reserve monetary policy, and the overall health of the economy all play massive roles. While rates have dipped, affordability challenges due to high home prices persist for many buyers.
  • Market Balance Hint: There are signs the real estate market is slowly moving towards a more balanced state. Some areas are seeing prices ease a bit, and inventory is picking up. This could give buyers a bit more leverage and potentially cool the overheated appreciation we've seen in past years.

The Mortgage Demand Picture

Despite the rates nudging lower, overall mortgage application volume actually dropped by 9.7% in the recent two-week period ending January 2, 2026, as reported by MBA. This is partly due to the holiday slowdown, but it also highlights that even with lower rates, the market isn't exactly booming.

  • Refinance Applications: Saw a bigger drop, down 14%. However, the year-over-year comparison is strong, up 133%. This means many homeowners have already refinanced when rates were even lower, or that opportunities are still significantly better than a year ago.
  • Purchase Applications: Dropped by 6% from two weeks prior but are still up 10% year-over-year. This indicates a steady, albeit not explosive, demand from homebuyers.

Looking Ahead: What to Expect

Industry experts are generally anticipating that rates will stick around current levels for a while, with the possibility of dipping below 6% more consistently later in 2026. If that happens, it could truly “unleash” pent-up buyer demand, especially as we head into the traditionally busy spring housing market.

My Personal Take

From my experience, the 5.98% on the 30-year fixed is a very compelling rate for anyone looking to buy or refinance. It strikes a good balance between affordability and offering some of the lowest rates we've seen in a while. For those who can manage the higher payments, the 15-year fixed at 5.41% is almost a no-brainer if your goal is to save the maximum amount of money over time and build equity rapidly. Don't get so caught up in the monthly payment that you forget the total cost. It's always worth talking to a trusted mortgage professional who can run personalized scenarios for you.

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, Jan 8: 30-Year Refinance Rate Drops by 10 Basis Points

January 8, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of January 8, 2026, the 30-year fixed refinance rate has dipped by 10 basis points, a welcome sign for homeowners looking to potentially lower their monthly payments. While other refinance rates are holding steady, this small but significant movement could be your cue to explore refinancing your mortgage.

For homeowners, that often includes a serious look at their mortgage. After all, it’s usually the biggest debt we have, and even a slight change in the interest rate can make a real difference to our wallets month after month. Today, January 8, 2026, brings a bit of financial breathing room, thanks to a drop in one of the most popular mortgage types.

Mortgage Rates Today, Jan 8: 30-Year Refinance Rate Drops by 10 Basis Points

What's Happening with Refinance Rates Right Now?

Think of refinance rates like the weather; they can change, but sometimes they just settle in for a bit. According to the latest data from Zillow, the national averages for fixed and adjustable refinance rates have been pretty stable recently. That’s not a bad thing! Stability can make planning a lot easier.

Here's a quick look at the national averages as of today, January 8, 2026:

  • 30-Year Fixed Refinance Rate: 6.52% (This is the big mover, down from last week)
  • 15-Year Fixed Refinance Rate: 5.50% (Holding steady, offering a quicker path to ownership)
  • 5-Year ARM Refinance Rate: 6.98% (Adjustable-rate mortgages are also stable for now)

The Tiny Drop That Could Mean Big Savings

The most exciting bit of news is the 10 basis point drop in the 30-year fixed refinance rate. Last week, the average was hovering around 6.62%, and now it’s at 6.52%. Now, I know what you might be thinking – 0.10%? That doesn't sound like much. But trust me, when you’re talking about a loan that can last three decades, even a small percentage point can add up to thousands of dollars in savings over time.

To put this into perspective, let's look at how it breaks down:

Loan Type Current Rate (Jan 8, 2026) Last Week's Rate Change
30-Year Fixed 6.52% 6.62% –0.10%
15-Year Fixed 5.50% 5.50% Stable
5-Year ARM 6.98% 6.98% Stable

This little dip in the 30-year rate might just be the nudge some homeowners need to seriously consider refinancing. It’s about finding that sweet spot where your monthly payment is manageable while also making progress on paying down your home loan.

Understanding Your Monthly Payment

Knowing the numbers is key to making smart financial decisions. Let’s imagine you have a $300,000 loan and see how these rates might affect your monthly bill. Remember, these figures are for principal and interest only and don't include property taxes or homeowner's insurance.

Here’s a quick comparison for a $300,000 loan:

Loan Type Interest Rate Term Length Estimated Monthly Payment*
30-Year Fixed 6.52% 360 months ~$1,900
15-Year Fixed 5.50% 180 months ~$2,450

*Payments are principal + interest only.

As you can see:

  • The 30-Year Fixed: Offers a lower monthly payment of around $1,900. This can be a lifesaver if you’re trying to free up cash for other expenses or investments. However, because you're stretching the payments over twice as long, you'll end up paying more in total interest by the time you own your home free and clear.
  • The 15-Year Fixed: Comes with a higher monthly payment, approximately $2,450. But the upside is huge! You’ll pay off your mortgage much faster (in half the time!) and save tens of thousands of dollars in interest over the life of the loan.

So, it’s a classic trade-off: affordability now versus long-term savings.

Recommended Read:

30-Year Fixed Refinance Rate Trends – January 7, 2025

Best Time to Refinance Your Mortgage: Expert Insights

Should You Refinance Your Mortgage Now or Wait Until 2026? 

Beyond the Numbers: What This Means for You

This update is more than just numbers on a screen; it’s a potential opportunity. The Mortgage Bankers Association (MBA) has been tracking this closely, and their recent reports confirm that interest rates have hit a 15-month low. That's a pretty significant milestone.

Even though overall mortgage application volume has been a bit slow, we're seeing a spike in refinance applications. In fact, refinance applications rose by 7.4% in the most recent survey. This tells me that a lot of homeowners, just like you, are noticing these rates and are starting to explore their options. Refinancing now makes up 56.6% of all mortgage applications, up from the previous week.

It's important to note that despite the usual holiday slowdown, the refinance index is a whopping 133% higher than it was this time last year. This indicates a strong underlying interest in refinancing.

On the flip side, the purchase market has seen a bit of a dip, with applications for new home purchases falling 6.2%. This is likely due to economic uncertainty and a job market that, while improving, still keeps some potential buyers on the sidelines.

Looking Ahead: What the Experts Predict

What does all this mean for the rest of 2026? The MBA has a forecast, and they anticipate mortgage rates will likely remain relatively stable throughout the year. They’re not expecting a huge drop, but they do anticipate “spells of refinance opportunities” as rates naturally fluctuate.

Their economists are projecting that rates will average around 6.4% for the entire year. The reason for this stability? They point to inflation that’s proving a bit stubborn and an economy that’s still growing. These factors tend to keep interest rates in that mid-6% range rather than seeing a dramatic decrease.

My Take: Is Refinancing Right for You?

From my perspective, the stability we're seeing in January 2026 is a golden opportunity for homeowners. While rates are still higher than the absolute rock-bottom lows we saw a few years back, the modest 10 basis point drop in the 30-year fixed rate is definitely worth paying attention to.

If you’ve been thinking about refinancing, now is the time to get quotes and compare.

  • For those prioritizing long-term payoff and saving the most on interest: The 15-year fixed rate at 5.50% is still an excellent choice if your budget comfortably allows for the higher monthly payment.
  • For those who need more breathing room in their monthly budget: The slightly lower 30-year fixed rate of 6.52% could significantly ease your cash flow. This reduction, while small percentage-wise, makes that monthly payment more manageable.

Don't just take my word for it – get an official quote from your lender or multiple lenders. Many refinancing costs can be offset by the savings you'll achieve, especially if you plan to stay in your home for several more years. It’s about making your mortgage work for you, not against you.

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

With interest rates and housing policies shaping affordability, 2026 offers investors a pivotal chance to lock in cash‑flowing rental properties.

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Talk to a Norada investment counselor today (No Obligation):
(800) 611-3060

Get Started Now

Recommended Read:

  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Flipping, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

How a 1% Drop in Mortgage Rates Could Unlock 5.5 Million Buyers

January 7, 2026 by Marco Santarelli

How a 1% Drop in Mortgage Rates Could Unlock 5.5 Million Buyers

Imagine finally finding that perfect house, picturing your life there, only to realize the monthly payments are just out of reach. It’s a story many potential homebuyers know all too well these days. But what if things could change? Well, it turns out that even a seemingly small shift, like a 1% drop in mortgage rates, could make a huge difference, potentially opening the door for millions of people to buy a home.

Yes, according to research from the National Association of REALTORS® (NAR), a 1% decrease in mortgage rates could add about 5.5 million households to the pool of potential buyers, including 1.6 million renters who might finally be able to make the leap into homeownership. This is exciting news for anyone feeling priced out of the market right now.

How a 1% Drop in Mortgage Rates Could Unlock 5.5 Million Buyers

Why All the Fuss About Mortgage Rates?

You’ve probably heard a lot about mortgage rates lately. They've been a major topic because they directly impact how much house you can afford. Think of it like this: the mortgage rate is the price you pay to borrow the money needed to buy your home. When that price goes up, your monthly payments go up significantly.

For a while now, we've been dealing with a double whammy: home prices shot up, and then mortgage rates followed suit. The National Association of REALTORS® pointed out that between mid-2022 and the end of 2023, average rates jumped from around 3% to over 7%. What does that mean in real dollars? For many people, it meant their monthly mortgage payment jumped by more than $1,000 compared to what they might have paid before the pandemic. Ouch.

From my perspective, this surge in costs effectively put many potential buyers on pause. They were ready and willing, but the numbers just didn't work anymore. It created what experts call an affordability crunch, freezing many buyers in their tracks.

Breaking Down the Numbers: What's a 1% Drop Worth?

Okay, let's talk specifics. How much difference does that 1% really make? It’s more than you might think.

Let’s look at an example cited by Matt Schulz, LendingTree’s chief consumer finance analyst. Suppose you're buying a $500,000 home and manage a 10% down payment ($50,000), leaving you needing a $450,000 mortgage.

  • At a 7% interest rate: Your estimated monthly payment for principal and interest would be around $3,895.
  • If rates dropped to 6.25%: That same loan would mean a monthly payment of about $3,672.

That's a saving of $223 per month. Now, imagine if rates dropped even further, say, to 6%. Based on calculations, the principal and interest payment on that same $450,000 loan could fall closer to $2,700 per month. That’s a potential saving of nearly $1,200 per month compared to the 7% rate!

While the ultra-low rates of 2020-2021 are likely behind us, a drop of 1% from current levels is a pretty big deal. NAR's research highlights that this kind of change could make homeownership achievable for millions more households. They estimate that 5.5 million households could be added to the potential buyer pool. Out of that group, a significant portion – 1.6 million – are renters who might finally see a path to owning their own place.

My take on this? It’s not just about saving a few bucks. It's about shifting the dream of homeownership from “maybe someday” to “maybe next year.” It changes the whole affordability equation for a massive number of people.

Who Gets the Biggest Boost?

When mortgage rates decrease, certain groups benefit more than others:

  • First-Time Home Buyers: This group often has less equity built up and may be stretching their budget to afford a home. They are often the most sensitive to monthly payment changes. Rising rents have made saving for a down payment even harder, so a lower rate that reduces the monthly mortgage payment can be the key factor in making a purchase possible.
  • Current Homeowners Looking to Move: Many homeowners refinanced or bought homes when rates were historically low. They might be hesitant to sell now because moving would mean taking out a new, much higher-rate mortgage. However, if rates drop significantly (like by 1%), it could lessen the “lock-in effect.” This might encourage them to sell their current homes, which in turn adds more properties to the market – increasing housing inventory for everyone. NAR economist Nadia Evangelou notes that lower rates help “both first-time buyers and current homeowners take the next step.”

It seems like a potential drop in rates could be a catalyst for activity across the board, helping people move up, move down, or buy for the very first time.

Are People Already Responding to Lower Rates?

It’s not just theoretical. Real estate professionals are already seeing signs that buyers are sensitive to rate changes.

Brad O’Connor, chief economist at Florida REALTORS®, shared during a recent NAR event that Florida saw a roughly 10% year-over-year increase in home sales this past fall. This uptick happened right when mortgage rates were starting to come down, hovering around 6.25%. Pending home sales in Florida were even up by 23% in October compared to the previous year. “We’re encouraged by how we see people are responding to lower interest rates already,” O’Connor mentioned.

Similarly, Ryan Price, chief economist at Virginia REALTORS®, noted a similar trend in his state. He observed an increase in sales in the fall that coincided with improved mortgage rates in September. He called these “early glimmers of hope” for what might come next year.

Personally, I’ve been hearing similar stories from agents and buyers in my area. When there’s even a hint of better affordability, the phones start ringing, and showings pick up. It really shows that pent-up demand is just waiting for the right conditions.

What’s the Crystal Ball Saying About Mortgage Rates?

So, will rates actually drop significantly? The National Association of REALTORS® has a forecast suggesting that mortgage rates could fall to around 6% in 2026.

This prediction takes into account several economic factors, including:

  • Potential cuts to the Federal Reserve's short-term interest rates.
  • Ongoing trends in inflation.
  • Government spending and national debt levels.
  • Global trade impacts (like tariffs).
  • The Federal Reserve’s management of its balance sheet (quantitative tightening).
  • The performance of the 10-year Treasury yield, which is a key indicator for mortgage rates.

While predicting the future is tricky, this forecast offers a hopeful outlook for potential homebuyers.

Deep Dive: How a 1% Drop in Mortgage Rates Could Unlock 5.5 Million Buyers in Your Area

NAR’s analysis digs deeper, looking at how specific metro areas could be impacted if rates were to drop from, say, 7% down to 6%. It's not just about the national numbers; the effect can be felt differently from place to place.

Generally, a rate decrease means more households can afford the monthly payments associated with the median-priced home in that area. Here are some of the areas predicted to see the biggest jump in qualifying households from a 1% rate drop:

  • Kalamazoo-Portage, Mich.: Potential for an 8% increase in households qualifying to buy.
  • Yuma, Ariz.: 7.5% increase.
  • Racine, Wis.: 7.5% increase.
  • Hilton Head Island-Bluffton, S.C.: 7.4% increase.
  • Rochester, Minn.: 7.4% increase.

Let's look at some specific examples provided by NAR to see the potential impact:

New York-Newark-Jersey City, NY-NJ-PA

  • A 1% drop (from 7% to 6%) could increase the share of households qualifying to buy by 3.8%.
  • This means roughly 285,972 more households could afford the median-priced home.
  • If just 10% of these newly qualified households buy, that could lead to approximately 28,597 additional home sales in the next year or two.

Atlanta-Sandy Springs-Alpharetta, GA

  • A 1% rate drop could boost the number of qualifying households by 5.4%.
  • An estimated 126,038 more households would gain affordability.
  • This could translate to about 12,604 additional home sales.

Dallas-Fort Worth-Arlington, TX

  • This area might see a 4.9% increase in qualifying households with a 1% rate drop.
  • Around 144,734 more households could afford the median home.
  • An estimated 14,473 additional sales could result.

Los Angeles-Long Beach-Anaheim, CA

  • Here, a 1% drop could mean 2.7% more households qualifying.
  • That's about 122,864 additional households affording the median home.
  • Projected additional sales could be around 12,286.

San Jose-Sunnyvale-Santa Clara, CA

  • A similar rate drop could add 2.9% to the qualifying household share.
  • This translates to about 19,835 more households qualifying.
  • Potentially leading to 1,984 additional home sales.

(Note: These figures are based on NAR's analysis and projections. Actual impacts can vary.)

These examples illustrate the significant ripple effect lower rates can have, not just on individual buyers but on the overall market activity in major metropolitan areas.

My Thoughts: A Welcome Shift for Homeownership

As someone who follows the housing market closely, the potential impact of a 1% drop in mortgage rates is genuinely significant. While 6% is still higher than the rock-bottom rates we saw a few years ago, it represents a substantial improvement in affordability compared to the 7%+ rates.

This research from NAR gives me confidence that the market is dynamic. It shows that when affordability improves, people respond. Bringing 5.5 million potential buyers back into consideration could lead to a more balanced market, provide much-needed opportunities for aspiring homeowners, and help existing owners make their next move. It’s a crucial step towards making the dream of homeownership accessible again for a much larger slice of the population. If rates continue on the predicted downward trend, 2026 could indeed be a pivotal year for the housing market.

🏡 Which Rental Property Would YOU Invest In?

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

VS

San Antonio, TX
🏠 Property: Salz Way
🛏️ Beds/Baths: 3 Bed • 2 Bath • 2330 sqft
💰 Price: $384,999 | Rent: $2,375
📊 Cap Rate: 4.1% | NOI: $1,324
📅 Year Built: 2019
📐 Price/Sq Ft: $166
🏙️ Neighborhood: A

Tennessee’s balanced rental vs Texas’s larger home with lower cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Talk to a Norada investment counselor (No Obligation):

(800) 611-3060

Contact Us Now

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates

Experts Predict Little Chance of Mortgage Rates Dropping Below 6% in 2026

January 7, 2026 by Marco Santarelli

Experts Predict Little Chance of Mortgage Rates Dropping Below 6% in 2026

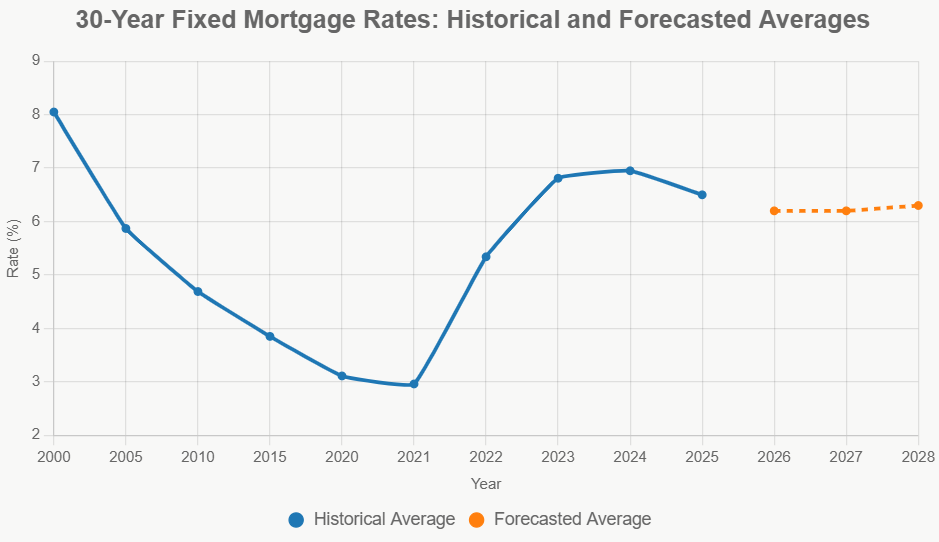
If so, you're probably wondering what's going to happen with mortgage rates. It's the million-dollar question, right? Well, I've been looking closely at the latest forecasts, especially the 30‑year mortgage rate predictions for 2026 by Zillow, Redfin, and Realtor.com. And here's the headline takeaway I'm getting: most experts think the average 30-year fixed mortgage rate will likely settle around 6.3% in 2026. It’s not a huge drop, but it might be just enough to make things a bit easier for buyers.

As we wrap up 2025, the housing market feels like it's finally catching its breath after a few wild years. Remember when rates shot up past 7%? Ouch. Thankfully, the Federal Reserve's moves this year have brought rates down into the mid-6% range. But that dream of getting back to those super-low rates we saw a few years ago? That still seems unlikely for now.

This 6.3% prediction from Zillow, Redfin, and Realtor.com suggests a gradual cooling off, more of a steady adjustment than a sudden boom or bust. I'll be sharing my own thoughts and insights based on what I'm seeing in the market data and hearing from these major real estate players.

Experts Predict Little Chance of Mortgage Rates Dropping Below 6% in 2026

What the Experts Are Saying About 2026 Mortgage Rates

It’s interesting how closely Zillow, Redfin, and Realtor.com seem to agree on the main point: rates are expected to ease slightly, but probably not dramatically drop below 6% for any extended period in 2026. Think of it as a gentle nudge towards better affordability rather than a wide-open door.

Here’s a quick look at their general outlook:

Platform Projected 2026 Average Rate Key Rate Range/Scenarios Impact on Payments (Estimated)
Zillow Around 6.3% (unlikely below 6%) Lingers in the low- to mid-6% range Modest improvement
Redfin 6.3% Mostly low-6% range, brief dips <6% Slight affordability boost
Realtor.com 6.3% Stays in the low-6% range ~1.3% payment reduction

What strikes me is this consistent forecast. It tells me that the underlying economic forces are pointing in a similar direction for all these groups. They're all looking at factors like inflation, the Federal Reserve's actions, and the overall health of the economy.

Historical and Projected 30-Year Fixed Mortgage Rates (2010-2026)

Zillow's team, who pay close attention to things like rent prices (a big part of inflation), are really emphasizing that inflation isn't going away completely. This is a major reason they don't see rates diving below 6%. They believe the bond market, which heavily influences mortgage rates, will keep rates somewhat anchored above that psychological threshold.

Redfin talks about a “Great Housing Reset,” and their prediction fits right into that. They see rates averaging 6.3%, maybe dipping slightly below 6% here and there, but not staying there. It suggests a market finding a more stable footing.

Realtor.com's forecast is right on the money at 6.3% too. They highlight that this could mean a noticeable drop in monthly payments—around 1.3% less for the typical homebuyer compared to 2025. That might not sound huge, but trust me, when you're talking about mortgage payments, every little bit helps!

Why Are Rates Predicted to Be Around 6.3%?

It's easy to just throw out a number, but why do these experts think this? Several big economic factors are at play. Based on my reading and experience, here are the main ones shaping the 2026 mortgage rate predictions:

  • The Federal Reserve's Balancing Act: The Fed has been raising interest rates to fight inflation. Now, they've started cutting them, which helps lower mortgage rates. But they're being cautious. They've signaled they'll likely cut rates more in 2025, maybe 50 to 75 basis points total. However, they don't want to cut too fast or too deep, especially if inflation starts ticking up again. By late 2025, they might reach a “neutral” rate – not actively trying to slow the economy down, but not stimulating it either. This neutrality means less downward pressure on mortgage rates.
  • Inflation Still Lingers: Even with rate cuts, inflation hasn't completely vanished. Costs for things like rent and housing services are still a bit stubborn. Since mortgage rates are closely tied to the yields on government bonds (like the 10-year Treasury), and those yields are sensitive to inflation fears, rates are likely to stay higher than they were a few years ago. Think of it like this: if investors think inflation will eat away at their returns, they'll demand higher interest rates on bonds, and that pushes mortgage rates up.
  • The Economy is Okay, But Not Amazing: We're seeing slowing economic growth and unemployment ticking up slightly (maybe around 4.5%). This is actually one reason the Fed can cut rates. But the job market is still pretty solid, with decent job creation each month. This resilience prevents a sharp economic downturn that might force rates much lower. It’s a Goldilocks scenario – not too hot, not too cold – which often leads to moderate rate environments.
  • Worries About Debt and Global Stability: The U.S. has a lot of government debt, and that can sometimes put upward pressure on interest rates. Plus, global issues – like trade tensions or conflicts – can create uncertainty. When the world feels shaky, investors often move money to safer assets, which can affect bond yields and, consequently, mortgage rates. These factors act as a brake, preventing rates from falling too drastically.
  • What's Happening in Housing Itself: Even though rates are higher, there still aren't enough homes for sale in many areas. This shortage keeps demand relatively strong, which can indirectly support mortgage rates by preventing a steep drop in home prices.

From my perspective, it’s this mix of factors – the Fed trying to be careful, inflation not totally gone, a steady economy, and some lingering global/debt concerns – that creates the consensus for rates hovering in that low-to-mid-6% range.

What Does This Mean for the Housing Market? A “Reset,” Not a “Boom”

So, what’s the practical impact of these 30‑year mortgage rate predictions? The word I keep hearing from these experts is “reset.” It suggests a market that's becoming more balanced, not one that's suddenly going to take off like a rocket.

Here’s what I expect we might see:

  • More Homes Selling: With rates slightly lower, some buyers who were priced out or waiting on the sidelines might jump back in. Zillow predicts around 4.26 million existing-home sales, Redfin is looking at about 4.2 million, and Realtor.com forecasts 4.13 million. This is a modest increase, maybe 1-4% higher than in 2025. It’s driven by the fact that buyers could potentially save tens of thousands of dollars over the life of their loan compared to earlier peaks.
  • Home Prices Stabilize: Forget huge price jumps. Experts are predicting price growth to slow down to about 1-2.2% nationally. Realtor.com sees prices going up maybe 2.2%, Redfin forecasts just 1%, and Zillow is around 1.2%. This is good news because it means incomes might start keeping pace with, or even slightly outpacing, home price increases for the first time in a while.
  • Refinancing Picks Up: Many homeowners refinanced when rates were at historic lows a few years back. Now, with rates expected to be in the mid-6% range, some of those folks might find a reason to refinance again if rates dip into the high 5% or very low 6% range. Redfin, for instance, sees refinancing activity jumping significantly. This could help homeowners lower their monthly payments.
  • A Better Balance for Buyers and Sellers: We might see a slight increase in the number of homes available for sale (maybe 15-20% more). This could ease the intense competition buyers have faced. However, I suspect a significant chunk of potential buyers, especially younger ones like millennials, might still struggle with affordability, even with slightly lower rates. Builders might continue offering incentives like mortgage rate buydowns to attract buyers.

I personally feel this gradual adjustment is healthier for the market long-term. It helps prevent another bubble and allows things to stabilize after the craziness of the pandemic and the subsequent rate hikes.

Not All Areas Are the Same: Regional Differences Matter

It’s crucial to remember that these national averages don't tell the whole story. My experience shows that real estate is always local.

  • Midwest vs. Sun Belt: You might find better affordability and more stable rates in Midwestern cities, where home prices are generally lower. Places like Indianapolis could see rates around 6.2% with payments dropping. On the flip side, popular Sun Belt areas like Phoenix might continue to see rates slightly higher, maybe closer to 6.5%, and still experience some price growth.
  • Value Opportunities: Zillow points out cities like Buffalo, NY, that might see home values increase despite higher rates, maybe by 3.5%. These are often places where prices haven’t skyrocketed as much. Conversely, areas like Austin, TX, might see prices soften slightly (-0.5%).
  • Coastal Hubs: Expect sticker shock to remain a challenge in major coastal cities where demand is high and prices are already expensive. Even with a 6.3% rate, monthly payments could easily be $3,000 or more.

Conclusion: A Steady Path Forward

Looking at the 30‑year mortgage rate predictions for 2026, I feel cautiously optimistic. The consensus points towards a gradual cooling, settling around 6.3%. This isn't the super-low rate environment of the past, but it’s a step towards better balance and affordability after a period of intense fluctuation.

This forecast suggests a housing market focused on sustainable growth rather than speculative frenzy. While unexpected economic events can always shake things up, 2026 appears poised to be a year of steady progress for those looking to make a move in real estate. It’s a good time to be informed, do your homework, and make strategic decisions based on the best data available.

From Cash to Cash Flow: Build Hassle‑Free Passive Income

Invest once, collect monthly — a simple way to turn your capital into steady, hassle‑free passive income.

Norada Real Estate helps you seize this rare opportunity with turnkey rental properties in strong markets—so you can build passive income while borrowing costs remain historically low.

🔥 HOT NEW Properties JUST ADDED! 🔥

Talk to a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Mortgage Rates Predictions for 2026: Insights from Leading Forecasters
  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Today

Mortgage Rate Predictions for 2026: What Leading Forecasters Expect

January 7, 2026 by Marco Santarelli

Mortgage Rate Predictions for 2026: What Leading Forecasters Expect

The question on everyone’s mind, especially if you're dreaming of homeownership or looking to refinance: what will mortgage rates do by 2026? Based on current economic indicators and expert analysis, mortgage rates in 2026 are expected to see a modest decline, likely hovering between 5.9% and 6.5% for a 30-year fixed loan. While a significant drop below 6% isn't a certainty, this anticipated easing offers a glimmer of hope for a more accessible housing market.

Mortgage Rate Predictions for 2026: What Leading Forecasters Expect

As I look at the data and speak with folks who follow this stuff closely, it feels like we're moving from a period of significant upward pressure on rates to a more stable, slowly descending path. It’s not a freefall, mind you, but it’s definitely a move in the right direction after the highs we’ve seen. This isn't just about numbers; it's about how people can afford their homes, build equity, and participate in the American dream.

The Road Behind Us: From Pandemic Perks to Pricey Mortgages

To understand where we're headed, we have to look back at how we got here. Remember those unbelievably low mortgage rates around 2021? A 30-year fixed-rate mortgage averaged a stunning 3.15%. It was a golden age for home buyers and refinancers!

Then, as we all know, the economy started to heat up fast. Inflation, which had been pretty quiet, suddenly surged. To try and tame it, the Federal Reserve started raising interest rates pretty aggressively. This “interest rate hike” cycle meant mortgage rates shot up, hitting a peak near 7% in 2023. Ouch. For anyone trying to buy a house, that meant much higher monthly payments. It also created a “lock-in effect” where homeowners with super-low rates weren't selling their homes, leading to less inventory.

Now, as we stand in late 2025, rates have stabilized a bit, mostly hovering in the 6.2% to 6.7% range. This is still high compared to a few years ago, but it’s a welcome pause after the rapid increases.

Here's a quick look at how rates have moved:

Year Average 30-Year Fixed Rate (%) Key Reason
2020 3.38 Pandemic stimulus, low inflation
2021 3.15 Continued Fed support, record-low yields
2022 5.53 Inflation starts to rise, Fed hikes begin
2023 7.00 Aggressive Fed action to curb inflation
2024 (Estimate) 6.90 Inflation slows, Fed begins cuts
2025 (Estimate) 6.73 More rate cuts, mortgage rates stabilize
2026 (Projection) ~5.9% – 6.5% Further easing, economic moderation

This table shows just how much rates can swing based on what the economy is doing.

chart showing mortgage rate predictions for 2026

What's Driving the 2026 Forecasts? It's All About Balance

The predictions for 2026 mortgage rates aren't pulled out of thin air. They're based on careful analysis of what drives these costs. Think of it like a delicate balancing act between a few key economic forces:

  • Fighting Inflation: The Federal Reserve's main goal has been to get inflation back down to their target of around 2%. If they succeed, and inflation stays down, it gives the Fed room to lower its own key interest rates. Lower short-term rates from the Fed generally lead to lower long-term rates, including mortgage rates.
  • The Economy's Health: Is the economy humming along nicely without overheating? Or is it slowing down too much, perhaps heading towards a recession? Forecasters are hoping for a “soft landing”—where the economy cools down just enough to curb inflation without crashing. If the economy weakens significantly, the Fed might cut rates more, pushing mortgage rates down faster. But if it stays surprisingly strong and inflation proves stubborn, rates might stay higher for longer.
  • Treasury Yields: Mortgage rates are closely tied to the yields on U.S. Treasury bonds, particularly the 10-year Treasury. When investors demand higher yields on these safe investments (meaning they can get more for their money), mortgage lenders also have to charge more. Factors like government spending, international demand for U.S. debt, and general economic sentiment all influence Treasury yields.
  • Job Market Stability: A strong job market usually means people have money to spend and borrow, which can sometimes fuel inflation. If job growth slows down considerably, it might signal a weaker economy, which again could lead to lower interest rates.

My take on this? From what I’ve seen, the Fed has made real progress on inflation. Core inflation (which strips out volatile food and energy prices) is still a bit sticky, but I'm optimistic it will continue its downward trend. This should give the Fed the confidence to continue cutting rates, which should translate to lower mortgage rates in 2026. However, I don't see us returning to the sub-4% rates of the early 2020s anytime soon. Those were truly extraordinary times.

What the Experts Are Saying: A Range of Views

You'll find a spectrum of opinions when you look at mortgage rate predictions for 2026. This isn't a bad thing; it actually highlights the uncertainties involved.

  • Fannie Mae, a big player in the mortgage market, expects rates to end 2026 around 5.9%. They're betting on the Fed making a couple more moves to lower rates.
  • The Mortgage Bankers Association (MBA), on the other hand, sees things as a bit more stable. They predict rates to be around 6.4% for the year. They seem to think things like wage growth might keep some pressure on yields.
  • The National Association of Realtors (NAR) has a slightly more optimistic outlook, anticipating an average rate around 6.0%. They believe better affordability will boost home sales.
  • Other institutions like Wells Fargo and the National Association of Home Builders (NAHB) are looking at rates in the 6.2% to 6.25% range. They often point to ongoing costs in building homes and labor market tightness as factors that could keep rates from falling too much.

Here's a visual of those different predictions:

Mortgage Rate Predictions for 2026

While the exact numbers vary, the general trend points towards lower rates than we have right now, but likely not dramatically lower.

How Will This Affect You? Breaking Down the Impact

So, what does a potential drop in mortgage rates mean for different people?

  • For Homebuyers: Even a half-percentage-point drop can make a big difference. On a $400,000 mortgage, a rate of 6.0% instead of 6.5% could save you roughly $120 per month and nearly $43,000 over the life of the loan. For first-time buyers struggling with affordability, this easing can be crucial. However, home prices are also expected to continue rising, albeit at a slower pace (around 1.3%–2.5%). So, while rates might improve, the overall cost of buying could still be a challenge.
  • For Refinancers: If you have a mortgage with a rate above 6.5% or 7%, a move down towards 6% could finally make refinancing worthwhile. Many homeowners have been stuck with their existing low-rate mortgages (the “lock-in effect”). A decrease could prompt a wave of refinancing, allowing people to lower their monthly payments by a couple of hundred dollars.
  • For Sellers: With potentially more buyers able to afford homes, the housing market could become more active. This could lead to quicker home sales and a modest increase in prices. However, more inventory might also mean less intense bidding wars compared to the frenzied market of a few years ago.
  • For the Economy: Increased home sales and refinancing activity generally give the economy a boost. More construction means more jobs, and people who can lower their monthly payments have more money to spend elsewhere.

Here's a simple table summarizing the potential benefits:

Group Benefit of ~0.5% Rate Drop Potential Hurdle
Homebuyers Lower monthly payments, improved affordability Still-rising home prices, down payment challenges
Refinancers Reduced mortgage payments, cash savings Need to qualify for new loan, appraisal values
Sellers Faster sales, potentially higher prices Increased competition, property taxes
Overall Economy Stimulus via construction and consumer spending Inflation risks, global economic shifts

The Wildcards: What Could Throw a Wrench in the Works?

No prediction is foolproof. There are always risks that could push mortgage rates in unexpected directions:

  • Stubborn Inflation: What if inflation doesn't cool down as expected? If it stays stubbornly above 2%, the Fed might have to hold off on rate cuts for longer, or even consider raising them again. This would likely keep mortgage rates higher than predicted, possibly edging back towards 6.8% or 7%.
  • Economic Shocks: A sudden recession, a major geopolitical event (like a new conflict impacting oil prices), or unexpected supply chain issues could send shockwaves through the economy. A severe downturn might force the Fed to cut rates aggressively, dropping mortgage rates significantly, perhaps to the 5.5% range. On the flip side, surprisingly strong economic growth could keep rates elevated.
  • Government Spending/Debt: High levels of government borrowing can sometimes put upward pressure on interest rates as the government competes for funds in the bond market.

Given these uncertainties, I always advise people to prepare for a range of possibilities. Don't bet your entire financial plan on rates dropping dramatically. Consider your own timeline and financial situation when making housing decisions.

My Own Thoughts: Patience and Preparedness

From my perspective, the 2026 mortgage rate predictions suggest a market that is gradually becoming more accessible. The days of 3% rates are likely behind us for the foreseeable future, but the peak of 7%+ seems to be receding. This middle ground, the mid-6% range, offers a more balanced environment.

For those looking to buy, my advice is to focus on what you can control:

  1. Improve your credit score: A higher score gets you better rates.
  2. Save for a solid down payment: This reduces your loan amount and can sometimes open up better loan options.
  3. Get pre-approved for a mortgage: This gives you a clear picture of what you can afford and shows sellers you're a serious buyer.
  4. Shop around for lenders: Don't just go with the first one you talk to. Rates and fees can vary.

For those looking to refinance, keep a close eye on rates. If we see a sustained drop of 0.5% or more from your current rate, it might be time to explore your options.

The housing market is a complex beast, influenced by so many factors. While we can analyze trends and listen to expert opinions, life often throws curveballs. The key is to stay informed, be prepared, and make decisions that align with your personal financial goals, not just chase the latest rate prediction.

In essence, 2026 looks set to be a year of cautious optimism for the housing market, driven by a slow and steady easing of mortgage rates. It won't be a return to the wild lows of the pandemic era, but it should be a welcome improvement for many aiming to achieve homeownership or financial flexibility through refinancing.

Want Stronger Returns? Invest Where the Housing Market’s Growing

Turnkey rental properties in fast-growing housing markets offer a powerful way to generate passive income with minimal hassle.

Work with Norada Real Estate to find stable, cash-flowing markets beyond the bubble zones—so you can build wealth without the risks of ultra-competitive areas.

🔥 HOT NEW LISTINGS JUST ADDED! 🔥

Talk to a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down Below 6% in the Next 60 Days?
  • Who Benefits Most from Today's Lower Mortgage Rates?
  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
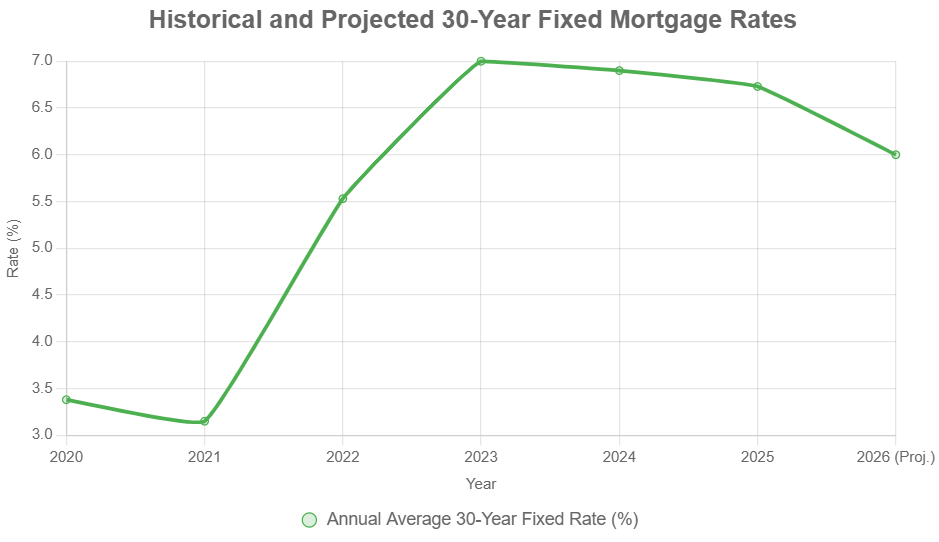
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Today

  • « Previous Page
  • 1
  • …
  • 60
  • 61
  • 62
  • 63
  • 64
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...