Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

30-Year Fixed Mortgage Rate Drops Steeply by 45 Basis Points

March 25, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Drops Steeply by 45 Basis Points

This is fantastic news for anyone dreaming of homeownership or looking to refinance: the 30-year fixed mortgage rate has significantly dropped by 45 basis points compared to last year, according to the latest data from Freddie Mac, making buying a home much more achievable this spring.

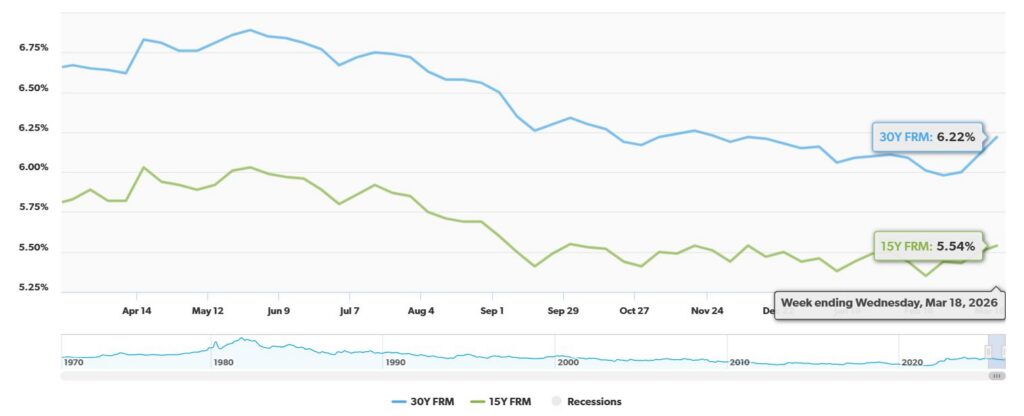
While rates did tick up slightly this past week to 6.22%, it's crucial to zero in on what that year-over-year comparison tells us. The current average is a full 45 basis points lower than the 6.67% average recorded during the same week last year. This isn't just a small blip; it’s a substantial shift that could put homeownership within reach for many more people this spring.

30-Year Fixed Mortgage Rate Drops Steeply by 45 Basis Points

For those who aren't immersed in mortgage lingo every day, a “basis point” might sound a bit technical. Think of it this way: one basis point is equal to 0.01%. So, a 45 basis point drop means the interest rate has fallen by 0.45%. It might not sound like a huge number in isolation, but when it comes to mortgages – especially a long-term one like a 30-year fixed – this difference can translate into significant savings over the life of the loan.

As Freddie Mac’s Primary Mortgage Market Survey® highlights, as of March 19, 2026:

  • The 30-year fixed-rate mortgage (FRM) averaged 6.22%.
  • This is a slight increase of 0.11% from the previous week's 6.11%.
  • However, and this is the crucial part, it's a notable 0.45% lower than the 6.67% seen a year ago.

This difference, while seemingly small on a week-to-week scale, represents a real opportunity for buyers. What I've seen in my years working with the housing market is that even small decreases in interest rates can make a big impact on what people can afford.
30-Year Fixed Mortgage Rate Drops Steeply by 45 Basis Points
Freddie Mac

A Deeper Dive: How This Affects Your Wallet

Let's crunch some numbers to see the real-world impact of this rate drop. When considering a mortgage, the interest rate is a major factor in your monthly payment. A lower rate means a lower monthly payment, freeing up your budget for other expenses or allowing you to afford a slightly larger home.

Consider this comparison for a 30-year fixed-rate mortgage, using the current rate of 6.22% versus last year's average of 6.67%:

Loan Amount Monthly Payment (6.22%) Monthly Payment (6.67%) Monthly Savings
$300,000 $1,841.30 $1,929.87 $88.57
$450,000 $2,761.95 $2,894.80 $132.85
$600,000 $3,682.60 $3,859.74 $177.14

Looking at these figures, even on a $300,000 loan, you're saving nearly $89 a month. On a larger loan, like $600,000, that monthly savings jumps to almost $178. Over 30 years, this adds up to thousands upon thousands of dollars in savings. This is the kind of difference that can help someone get approved for a mortgage they might have been denied previously, or allow them to buy a home that better suits their family's needs.

Beyond the Weekly Wobble: The Bigger Picture of Affordability

It’s easy to get caught up in the week-to-week fluctuations of mortgage rates. The fact that rates have edged up slightly this week is not uncommon. The market is influenced by a lot of factors, from inflation numbers to Federal Reserve policy, and it can be a bit of a rollercoaster. However, as Freddie Mac's Chief Economist, Sam Khater, points out, “the market is more affordable than last spring.” I completely agree with that sentiment.

We've seen periods where rates flirted with or even exceeded 8% in late 2023. Compared to those highs, the current average of 6.22% is a significant improvement. This sustained dip from last year, despite short-term increases, paints a more optimistic picture for potential homebuyers. It means that while you might see small daily or weekly changes, the overall trend has been favorable for affordability.

This improved affordability is reflected in positive market indicators. We're seeing improvements in purchase applications and pending home sales, which suggests that more people are actively looking to buy and are able to move forward with their plans. This is the kind of momentum that makes for a healthier and more dynamic housing market.

The 15-Year Fixed: Another Option for Savvy Borrowers

While the 30-year fixed-rate mortgage gets a lot of attention because of its lower monthly payments, it’s always worth looking at other options. The 15-year fixed-rate mortgage also offers a compelling picture.

According to Freddie Mac:

  • The 15-year fixed-rate mortgage averaged 5.54%.
  • This is up slightly from 5.50% last week.
  • However, it's a 0.29% lower than the 5.83% average from the same week last year.

Borrowing on a 15-year term means you'll have higher monthly payments compared to a 30-year mortgage, but you'll pay significantly less interest over the life of the loan and own your home free and clear much faster. For those who can comfortably manage the higher payments, a 15-year mortgage can be a very smart financial move.

What Does This Mean for the Spring Homebuying Season?

This 45 basis point drop in the 30-year fixed mortgage rate is precisely the kind of good news that can energize the spring homebuying season. Buyers who may have been priced out or were hesitant due to high borrowing costs are now likely to re-enter the market.

Here's what I believe this will translate to:

  • Increased Buyer Confidence: With lower rates and a general sense of improved affordability, buyers will feel more confident making a purchase.
  • More Competitive Market: As more buyers enter the fray, we might see increased competition for desirable properties. It’s important for buyers to be prepared and act decisively when they find the right home.
  • Refinancing Opportunities: Homeowners who have been waiting for a better rate to refinance their existing mortgage could also find this a good time to explore their options. Lower rates can reduce monthly payments or allow homeowners to tap into their home equity.

It’s still important to remember that the housing market is local, and prices can vary significantly by region. However, this broad decrease in mortgage rates is a positive tailwind for the entire country.

🏡 Two Rentals With Strong Investor Potential

Pleasant Grove, AL
🏠 Property: 4th Ave (1549 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1549 sqft
💰 Price: $265,000 | Rent: $1,850
📊 Cap Rate: 6.2% | NOI: $1,368
📅 Year Built: 2026
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Pleasant Grove, AL
🏠 Property: 4th Ave (1856 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1856 sqft
💰 Price: $410,000 | Rent: $3,200
📊 Cap Rate: 5.8% | NOI: $1,981
📅 Year Built: 2026
📐 Price/Sq Ft: $221
🏙️ Neighborhood: B+

Two Pleasant Grove rentals—one affordable with higher cap rate vs one larger with stronger NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

Today’s Mortgage Rates, March 24: 30-Year Fixed Rises to 6.37%, 15-Year FRM at 5.82%

March 24, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of Tuesday, March 24, 2026, mortgage rates have taken a notable jump, with the popular 30-year fixed rate hitting a high we haven't seen in a while. This upward movement is largely tied to the ongoing global uncertainties and the Federal Reserve's recent decision to keep interest rates where they are for now. Looking at the numbers from Zillow, the average 30-year fixed rate is now at 6.37%, which is a quarter-point increase just in the last week. Even the 15-year loan has seen a bump, now sitting at 5.82%, up 17 basis points compared to last Tuesday.

Today's Mortgage Rates, March 24: 30-Year Fixed Rises to 6.37%, 15-Year FRM at 5.82%

I always like to see where things stand clearly, so here's a quick rundown of the national averages, as reported by Zillow. It's a good idea to keep these numbers in mind when you're thinking about homeownership or refinancing.

Loan Type Average Rate
30-Year Fixed 6.37%
20-Year Fixed 6.28%
15-Year Fixed 5.82%
5/1 ARM 6.50%
7/1 ARM 6.31%
30-Year VA 5.89%
15-Year VA 5.48%
5/1 VA 5.51%

What strikes me about these figures is how the increase isn't just limited to one type of loan. We're seeing a general upward trend across both regular mortgages and VA loans. This really shows how connected mortgage rates are to what's happening in the broader financial markets.

How Today's Market is Affecting Things

It’s no surprise to anyone following the markets that mortgage rates are deeply connected to something called bond yields, especially the 10-year Treasury note. When those yields go up, mortgage rates tend to follow.

  • A Direct Link: Take yesterday, March 23, 2026, for instance. The 10-year Treasury yield climbed to 4.346%. Almost immediately, we saw mortgage rates begin to tick higher.
  • The Go-To Gauge: Lenders often use the 10-year Treasury yield as a kind of guidepost for setting their 30-year fixed mortgage rates. It makes sense because both are long-term investments, and they're essentially competing for the same money from investors.
  • The Gap: Right now, the average mortgage rate is sitting around 6.49%. If you compare that to the 10-year Treasury yield, it's about 2% higher. This extra percentage can be thought of as the “spread,” which covers the lender's risks, like the chance that a borrower might not be able to pay back the loan or that people might refinance their homes sooner than expected.

What's Driving These Rate Hikes?

Several things are adding up to push mortgage rates in this direction. As someone who's been watching this space for a while, it's a combination of factors that creates this pressure.

  • Global Jitters: We're seeing continued tension in different parts of the world. This has pushed oil prices up significantly, even going above $100 a barrel. When oil prices jump like that, it tends to make people worry about inflation, and those fears can quickly spread to bond yields and, consequently, mortgage rates.
  • The Fed's Pause: The Federal Reserve, through its Federal Open Market Committee (FOMC), held its meeting on March 17–18. They decided to keep the federal funds rate steady at 3.50%–3.75%. While this might seem like good news to some, it also meant that hopes for any quick drop in borrowing costs were dashed.
  • Market Swings: The Treasury yields have been a bit all over the place lately, with a notable spike recently to 4.303%. These kinds of rapid ups and downs make it really tricky for lenders to figure out what to charge for mortgages because they need some predictability in their pricing.

What to Expect in the Near Future

Looking ahead, it feels like things are going to stay a bit dynamic.

  • Rates are on the Move: I’ve heard from people in the industry that some of the best rates out there are only available for a short window – sometimes just three or four days – before they get adjusted again. This means if you're looking to lock in a rate, you need to be ready to act fairly quickly.
  • 2026 Forecasts: Experts from places like Fannie Mae and the Mortgage Bankers Association (MBA) are predicting that for the rest of 2026, the 30-year fixed rate will likely stay somewhere in the range of 6.0% to 6.4%. It's not going to be a sudden drop, but rather a period of hovering.
  • Thinking About Home Equity: With the rates for buying a new home or refinancing your main mortgage being higher, I'm seeing more homeowners consider options like Home Equity Lines of Credit (HELOCs). These currently have an average rate of 7.20%. It's a way for people to access the money they've built up in their homes without changing their current, likely lower, mortgage rate.

My Thoughts on Where We Stand

Today’s mortgage rates on March 24, 2026, paint a picture of a market that's navigating some tricky waters. Global events, concerns about prices going up, and the careful approach the Federal Reserve is taking are all playing a big role. While it's true that rates have climbed to some of their highest points in months, the general feeling is that they might settle into that 6.0%–6.4% range for the remainder of the year.

If you're thinking about buying a home or refinancing, it’s important to look at these short-term ups and downs and compare them with the longer-term forecasts. And for those lucky enough to have locked in those super-low pandemic-era rates, using something like a HELOC might be a smarter move if you need to tap into your home equity. I always advise people to speak with a trusted mortgage professional to figure out the best strategy for their personal situation.

🏡 Two Southeastern Rentals With Strong Cash Flow

Rincon, GA
🏠 Property: Founders Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1600 sqft
💰 Price: $275,000 | Rent: $2,200
📊 Cap Rate: 7.0% | NOI: $1,613
📅 Year Built: 2025
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Port Charlotte, FL
🏠 Property: Prineville St
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1914 sqft
💰 Price: $349,900 | Rent: $2,100
📊 Cap Rate: 5.0% | NOI: $1,457
📅 Year Built: 2025
📐 Price/Sq Ft: $183
🏙️ Neighborhood: A

Georgia’s affordable rental with higher cap rate vs Florida’s A‑rated property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 24, 2026: 30-Year Refinance Rate Drops by 2 Basis Points

March 24, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

It's Tuesday, March 24, 2026, and if you've been watching mortgage rates, you might have noticed a slight dip in the average 30-year refinance rate. Today, it's come down by 2 basis points to 6.70%, according to Zillow's latest data. While this might sound like just a small wiggle in the numbers, it's part of a bigger story in the current housing market that's worth exploring.

Mortgage Rates Today, March 24, 2026: 30-Year Refinance Rate Drops by 2 Basis Points

What's Happening with Refinance Rates Right Now?

Let's get straight to the numbers you're likely curious about. As of today, March 24, 2026, here’s a snapshot of where refinance rates stand nationally, as reported by Zillow:

  • 30-Year Fixed Refinance Rate: The national average has dipped to 6.70%. This is a slight decrease from last week's average of 6.72%, making it a 2 basis point drop. It's worth noting that this is still close to the highest levels we've seen since late last year.
  • 15-Year Fixed Refinance Rate: This shorter-term option is also seeing a bit of a relief, falling to 5.76% from 5.88% last week, a 12 basis point decrease.
  • 5-Year Adjustable-Rate Mortgage (ARM) Refinance Rate: This is where we see the most significant movement today, dropping by a notable 42 basis points to 6.70%.

Now, a 2 basis point drop on a 30-year mortgage might not seem like a game-changer for everyone's monthly payment. However, it’s a sign that the market is still trying to find its footing, and every little bit can add up, especially over the life of a loan.

Why Are Rates Moving Like This? The Big Picture

When I look at mortgage rates, I don't just focus on the day-to-day numbers. I try to understand the deeper currents pushing them. Several big factors are at play right now:

  • Inflation Worries: This is probably the biggest shadow hanging over the market. We're still seeing signs that prices are higher than the Federal Reserve would like. When inflation is high or expected to rise, lenders often increase mortgage rates to compensate for the fact that the money they lend out today will be worth less in the future.
  • Global Unrest: Unfortunately, geopolitical tensions, especially in the Middle East, are a constant source of market uncertainty. Higher oil prices, which often result from these conflicts, can directly fuel inflation. This uncertainty makes investors nervous, and they tend to demand higher returns for their investments, which includes mortgage-backed securities.
  • The Federal Reserve's Balancing Act: The Fed’s recent meeting on March 18th kept interest rates steady. They’ve signaled that they might cut rates one more time by the end of the year, but the persistent inflation data is making them cautious. They don't want to lower rates too quickly and then have to raise them again, which would mess up the economy even more. This caution keeps mortgage rates from falling significantly.
  • Treasury Yields: Mortgage rates often follow the direction of U.S. Treasury yields, particularly the 10-year Treasury note. When Treasury yields climb, mortgage rates usually follow suit. We've seen the 10-year yield push above its recent trading range, which is another signal of upward pressure on mortgage rates.

It's a juggling act, isn't it? The Fed wants to keep inflation in check, but they also don't want to hurt the economy too much. Meanwhile, global events are adding their own layer of complexity.

A Look at Application Trends: What Homeowners Are Doing

Beyond the rates themselves, it's helpful to see how actual homeowners are reacting. Zillow's data also gives us a glimpse into mortgage application activity:

  • Overall Application Drop: For the week ending March 13, 2026, total mortgage applications fell by 10.9%. This makes sense when rates are feeling high.
  • Refinance Activity Slows: Specifically, refinance applications saw a 19% week-over-week decline. When rates are a bit elevated, fewer people feel compelled to go through the process of refinancing.
  • Still Higher Than Last Year: Despite this weekly dip, refinance activity is still about 69% higher than it was during the same week in 2025. This is an important point. Even though today's rates might seem high compared to the super-low pandemic rates, they are still better than where they were early last year for many. This suggests that while the rush to refinance has calmed, people who need to refinance are still doing so.

This tells me that homeowners are being more selective. They aren't rushing into refinancing just for the sake of it. They're looking at their specific financial situation and deciding if the savings are worth the effort and cost.

My Expert Take: What Should You Be Thinking About?

Having spent years analyzing the mortgage market, I’ve learned a few things that might help you navigate these waters.

  • The “Magic Number” for Refinancing: A common rule of thumb is that refinancing usually makes financial sense if you can lower your current interest rate by at least 0.5% to 1.0%. Crucially, you also need to factor in your closing costs. If it takes you five years to break even on those costs, and you only plan to stay in your home for another three, it might not be the right move for you. Always do the math based on your specific situation.
  • The “Golden Handcuffs” Effect: Many of you, like me, might be enjoying a mortgage rate that was secured during the ultra-low period of the pandemic. Rates under 5% are hard to beat. If you have one of these “golden handcuffs” rates, today's rates in the high 6% range are likely not attractive enough for a traditional refinance. Giving up a 3.5% rate for a 6.7% rate just doesn't add up for most people.
  • Exploring Alternatives: For those homeowners who are “locked in” with those fantastic pandemic-era rates but still need access to cash for renovations, debt consolidation, or other major expenses, it's worth looking beyond traditional refinancing. I'm seeing more and more people turn to Home Equity Lines of Credit (HELOCs) or home equity loans. These products allow you to tap into your home's equity without touching your primary, low-interest mortgage. It’s a smart way to leverage your home's value while preserving that amazing rate you worked hard to get.

The Bottom Line for March 24, 2026

Mortgage refinance rates today are a reflection of our current economic reality. We're dealing with persistent inflation, global unease, and a Federal Reserve trying to thread the needle carefully. While the 30-year refinance rate dropping by 2 basis points to 6.70% is a positive sign for some, it's not a dramatic shift.

For those who locked in low rates during the pandemic, today’s rates probably don’t make sense for a full refinance. However, if you're looking to access your home's equity, exploring options like HELOCs might be a more strategic move than chasing a rate that's still significantly higher than what you currently have. Always crunch the numbers and consider your personal financial goals before making any big decisions. The housing market is always moving, and staying informed is your best tool.

🏡 Two TURnkey properties With Strong Cash Flow

Rincon, GA
🏠 Property: Founders Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1600 sqft
💰 Price: $275,000 | Rent: $2,200
📊 Cap Rate: 7.0% | NOI: $1,613
📅 Year Built: 2025
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Port Charlotte, FL
🏠 Property: Prineville St
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1914 sqft
💰 Price: $349,900 | Rent: $2,100
📊 Cap Rate: 5.0% | NOI: $1,457
📅 Year Built: 2025
📐 Price/Sq Ft: $183
🏙️ Neighborhood: A

Georgia’s affordable rental with higher cap rate vs Florida’s A‑rated property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 22, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Mortgage Rates Rise into the Mid-6% Range, Significantly Cooling Demand

March 23, 2026 by Marco Santarelli

Mortgage Rates Rise into the Mid-6% Range, Significantly Cooling Demand

The housing market, it seems, has hit a bit of a speed bump. As of March 2026, mortgage rates have nudged their way back into the mid-6% range, marking their highest point since late last year. For anyone thinking about buying a home or refinancing their current mortgage, this news is a clear signal that borrowing money for a home just got more expensive, and it's already putting the brakes on activity, especially for those looking to refinance.

What's driving this latest climb? You can point the finger at a couple of major players: rising Treasury yields, fueled by ongoing geopolitical tensions in the Middle East, and that persistent worry about inflation that just doesn't seem to want to go away.

Mortgage Rates Climb Back into the Mid-6% Range, Significantly Cooling Demand

What Does This Mean for Your Mortgage?

Let's break down what these numbers actually look like right now. From March 19th to 23rd, 2026:

  • 30-Year Fixed-Rate Mortgages are hovering between 6.12% and 6.63%. That's a pretty wide spread, meaning it still pays to shop around with different lenders.
  • For those looking for a shorter commitment, 15-Year Fixed-Rate Mortgages are averaging closer to 5.54% to 5.91%.
  • And for homeowners hoping to snag a better deal on their existing loan, the average 30-year refinance rate has climbed to about 6.77%. Ouch.

This jump in rates directly impacts how much house you can afford and how much you'll pay over the life of your loan. Consider this: for a $400,000 home with a 20% down payment (meaning a loan of $320,000), even a small increase in the interest rate can add up.

Mortgage Rate Monthly Principal & Interest (P&I) Payment Monthly Increase
5.5% $1,816.92 –
6.0% $1,918.56 +$101.64
6.5% $2,022.62 +$104.06
7.0% $2,128.97 +$106.35

As you can see, every half-percent adds a noticeable chunk to your monthly bill. In fact, a jump from 6.0% to 7.0% could mean paying over $2,500 more per year in mortgage payments. And the compounding effect over 30 years is staggering – that's an extra $75,700 in interest paid on that same loan just by going from 6% to 7%! These calculations don't even include property taxes, homeowners insurance, or potential private mortgage insurance (PMI), which only add to the total monthly housing cost.

The Impact on Housing Demand: Not a Uniform Chill

So, with borrowing becoming more expensive, what's happening to the housing market? Well, it's not a single, simple story.

Refinance Woes:

The refinance market is feeling the pinch the most. When rates were lower, many homeowners saw a clear benefit in refinancing to lock in a cheaper monthly payment. Now, with rates climbing back up, the incentive to refinance has largely disappeared for a lot of people. This is why refinance applications have seen a significant drop, falling by anywhere from 18.5% to a whopping 26% week-over-week. The math just doesn't add up for many anymore.

In fact, during the week ending March 13, 2026, total mortgage applications plunged by a substantial 10.9%, marking the sharpest decline we've seen since late last year. It’s a clear indicator that higher borrowing costs are making people pause and reconsider their plans.

Purchase Market Resilience (for now):

Interestingly, the market for new home purchases is showing a bit more resilience. While you might expect demand to plummet across the board, purchase applications have actually seen a slight uptick of 0.9% recently. Why? It's likely the start of the spring buying season, a traditional period of increased activity, and some buyers might be rushing to get into the market before rates potentially climb even further.

However, this resilience is happening alongside tight inventory levels. We're still looking at roughly a 2-month supply of homes. This lack of available homes for sale is a crucial factor that continues to prop up home prices, even as demand shows signs of cooling. It’s a delicate balance.

What's Next? The Federal Reserve's Stance and Future Forecasts

To understand where we might be headed, we need to look at the big picture and what the Federal Reserve is doing. At their meeting on March 18th, the Fed decided to keep the benchmark federal funds rate steady. They're holding firm at 3.50%–3.75%, signaling a cautious approach. They're waiting for inflation to get firmly under control before they even consider making any further rate cuts. This measured stance from the Fed often influences mortgage rates indirectly.

Looking ahead, the forecasts from major housing groups like Fannie Mae and the Mortgage Bankers Association suggest that we can expect mortgage rates to hover around the 6% to 6.4% mark for the rest of 2026. This means the current higher borrowing costs are likely here to stay for a while.

My Take: Navigating the Current Climate

From my perspective, this is a classic case of supply and demand, amplified by broader economic forces. The rise in mortgage rates isn't just a minor inconvenience; it directly impacts affordability. For many potential buyers, especially first-time homebuyers, the difference of a percentage point or two can mean the difference between buying a home and being priced out of the market altogether.

The continued tight inventory is the silver lining for sellers, as it prevents a drastic drop in prices. However, for buyers, it means they're facing both higher borrowing costs and limited choices.

If you're considering buying or refinancing, my best advice is to:

  • Shop Around Aggressively: Don't settle for the first rate you're offered. Compare offers from multiple lenders to ensure you're getting the best possible deal.
  • Get Pre-Approved: Knowing exactly how much you can borrow will help you set a realistic budget.
  • Focus on Your Long-Term Goals: If buying a home is a long-term goal, and you've found a place you love and can afford, sometimes waiting for rates to drop isn't the best strategy, especially if prices are rising.
  • Crunch the Numbers Realistically: Understand the full impact of the interest rate on your monthly payments and the total cost of homeownership.

The mortgage rate environment is always evolving, and staying informed is key to making the best financial decisions for your future.

🏡 Two Rentals With Strong Investor Potential

Pleasant Grove, AL
🏠 Property: 4th Ave (1549 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1549 sqft
💰 Price: $265,000 | Rent: $1,850
📊 Cap Rate: 6.2% | NOI: $1,368
📅 Year Built: 2026
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Pleasant Grove, AL
🏠 Property: 4th Ave (1856 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1856 sqft
💰 Price: $410,000 | Rent: $3,200
📊 Cap Rate: 5.8% | NOI: $1,981
📅 Year Built: 2026
📐 Price/Sq Ft: $221
🏙️ Neighborhood: B+

Two Pleasant Grove rentals—one affordable with higher cap rate vs one larger with stronger NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Today’s Mortgage Rates, March 23: Refinance Demand Falls as 30-Year Fixed Rate Hits 6.31%

March 23, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or refinancing, you've probably been watching mortgage rates closely. On Monday, March 23, 2026, they moved up, nudging closer to levels we haven't seen consistently since last fall. While it's not a dramatic leap, this shift means the 30-year fixed mortgage rate is now averaging around 6.31%, with the 15-year fixed rate at 5.77%, according to data from Zillow's lender marketplace. This uptick signals that we're moving away from the recent dip and back into the mid-6% range, influenced by ongoing economic currents.

Today's Mortgage Rates, March 23: Refinance Demand Falls as 30-Year Fixed Rate Hits 6.31%

Current Mortgage Rates

Mortgage Type Rate
30-Year Fixed 6.31%
20-Year Fixed 6.29%
15-Year Fixed 5.77%
5/1 ARM 6.36%
7/1 ARM 6.34%
30-Year VA 5.85%
15-Year VA 5.47%
5/1 VA 5.39%

Let's break down the numbers as they stood on March 23, 2026, based on Zillow's insights. This gives us a clear snapshot of the current borrowing costs:

  • 30-Year Fixed Rate: 6.31% – This is the most common type of mortgage, offering predictable monthly payments for the life of the loan. The upward tick here affects a lot of potential buyers.
  • 20-Year Fixed Rate: 6.29% – A middle ground for those who want to pay off their home a bit faster than a 30-year but still want a fixed payment.
  • 15-Year Fixed Rate: 5.77% – A popular choice for those who can afford slightly higher monthly payments in exchange for paying off their mortgage in half the time and significantly less interest over the loan's life.
  • 5/1 Adjustable-Rate Mortgage (ARM): 6.36% – This type of loan starts with a fixed rate for five years, then adjusts annually. Lenders often offer a slightly lower initial rate compared to fixed-rate loans, but there's a risk of payments increasing later.
  • 7/1 Adjustable-Rate Mortgage (ARM): 6.34% – Similar to the 5/1 ARM, but the initial fixed period is seven years.
  • 30-Year VA Rate: 5.85% – For eligible veterans and service members, VA loans offer competitive rates.
  • 15-Year VA Rate: 5.47% – A shorter-term option for VA borrowers.
  • 5/1 VA Rate: 5.39% – An adjustable-rate option for VA borrowers.

As you can see, the rise isn't exclusive to one type of loan. It's a general upward trend influencing most borrowing options, pushing us back towards those mid-6% figures.

What's Pushing Rates Up? The Market Pulse

It's crucial to understand that mortgage rates don't exist in a vacuum. They're directly influenced by larger economic forces. Here's what's been shaping the market recently:

  • A Swift Reversal: We saw mortgage rates hit some of their lowest points in late February 2026. However, March brought a notable shift, with rates beginning a steady climb. This kind of quick turnaround can make planning feel like a moving target for homebuyers.
  • The Big Picture Influencers:
    • Global Tensions and Oil Prices: The ongoing conflict in Iran has sent shockwaves through the energy markets, pushing oil prices higher. This, in turn, tends to ignite inflation fears across the globe, making lenders more cautious.
    • Following the 10-Year Treasury: Mortgage rates are almost always tethered to the 10-year Treasury yield. When that yield goes up, mortgage rates tend to follow. We've seen a significant increase in this key indicator, directly translating to higher borrowing costs.
    • The Fed's Steady Hand: The Federal Reserve held its benchmark interest rate steady at 3.50%–3.75% during its March meeting. This decision, while expected, signaled that they aren't leaning towards immediate interest rate cuts, which would have put downward pressure on mortgage rates. Their caution suggests they're watching inflation closely.

These factors combined create a sentiment of uncertainty, and when there's uncertainty, lenders often price that risk into their rates.

How This Affects You: Real-World Impacts

The rise in mortgage rates isn't just an abstract economic event; it has tangible consequences for individuals and the housing market as a whole.

  • Cooling Demand: It's no surprise, but when borrowing becomes more expensive, demand tends to soften. Total mortgage applications saw a significant drop of 10.9% in the week ending March 13. This suggests that fewer people are actively seeking to buy or refinance.
  • Refinancing Slowdown: The impact is particularly sharp on those looking to refinance. With rates ticking back up, the incentive to go through the refinancing process diminishes. Refinance activity fell dramatically, down 26% week-over-week. If you were considering refinancing to lower your monthly payment, now might be the time to re-evaluate your options and urgency.
  • Regional Divergence: While national averages paint one picture, it's crucial to remember that housing markets are local. I've noticed that in the Northeast and Midwest, where inventory is tight, home prices are actually on the rise. Conversely, some areas in Florida and California are seeing prices correct downward. This means the impact of mortgage rates can be felt differently depending on your chosen location.
  • The Total Cost of Homeownership: It's not just the mortgage payment that's weighing on affordability. I've seen insurance premiums continue to climb in many areas, and property taxes are also a significant factor. These rising costs beyond the mortgage principal and interest are creating a heavier monthly burden for homeowners, making the overall cost of owning a home a more significant consideration than ever.

Looking Ahead: What to Expect in 2026

While the current trend is upward, it's not necessarily a cause for panic. Expert forecasts offer some perspective. The Mortgage Bankers Association, for instance, projects 30-year fixed mortgage rates to hover around 6.10% for the remainder of 2026.

However, my experience tells me that forecasts are just that – predictions. The financial markets are notoriously dynamic, and unforeseen events can always shift the trajectory. We should be prepared for continued volatility. While the overall direction might be towards a slight stabilization, expect some bumps along the way.

Key Takeaways to Remember

To sum it up, here are the most important points from today's mortgage rate situation:

  • On March 23, 2026, mortgage rates climbed to 6.31% for the 30-year fixed, their highest level since September 2025.
  • The primary forces driving this climb are rising oil prices due to geopolitical conflict, increased inflationary concerns, and the upward movement in Treasury yields.
  • The Federal Reserve's decision to hold rates steady reinforces the current environment of higher borrowing costs.
  • This has led to a significant drop in refinance applications, while purchase applications are also feeling the strain.
  • We're seeing diverse trends in regional housing markets, and the total cost of ownership, including insurance and taxes, is a growing concern for affordability.
  • While forecasts suggest rates may stabilize near 6.10% by year-end, be ready for continued market fluctuations.

The Bottom Line: Today's mortgage rates on March 23, 2026, reflect a market adjusting to new economic realities. The climb back into the mid-6% range is impacting affordability and significantly cooling the demand for refinancing a mortgage. For those looking to purchase, understanding these shifts, alongside regional housing dynamics and rising ownership costs, is essential for making informed decisions in 2026.

🏡 Two Rentals With Strong Investor Potential

Pleasant Grove, AL
🏠 Property: 4th Ave (1549 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1549 sqft
💰 Price: $265,000 | Rent: $1,850
📊 Cap Rate: 6.2% | NOI: $1,368
📅 Year Built: 2026
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Pleasant Grove, AL
🏠 Property: 4th Ave (1856 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1856 sqft
💰 Price: $410,000 | Rent: $3,200
📊 Cap Rate: 5.8% | NOI: $1,981
📅 Year Built: 2026
📐 Price/Sq Ft: $221
🏙️ Neighborhood: B+

Two Pleasant Grove rentals—one affordable with higher cap rate vs one larger with stronger NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 23, 2026: 30-Year Refinance Rate Rises by 2 Basis Points

March 23, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Monday, March 23, 2026: The 30-year fixed refinance rate ticked up to an average of 6.74%, a small climb of 2 basis points from where we were last week. While this might seem like a tiny shift, it's part of a bigger story that's making homeowners pause and think about whether refinancing is still the smart move right now.

Mortgage Rates Today, March 23, 2026: 30-Year Refinance Rate Rises by 2 Basis Points

What's Happening with Refinance Rates?

It feels like just yesterday we were talking about rates heading in a different direction, but lately, things have gotten a bit choppy. According to Zillow's latest figures for March 23, 2026, the average rate for a 30-year fixed refinance has settled at 6.74%. This is up from last week's 6.72%. You might notice that other loan types are also showing similar trends:

  • 30-Year Fixed Refinance: 6.74%
  • 15-Year Fixed Refinance: 5.93%
  • 5-Year Adjustable-Rate Mortgage (ARM) Refinance: 7.15%

These numbers are pretty steady on a day-to-day basis, but looking at the bigger picture for the month, there's definitely an upward pressure that's hard to ignore.

Why Are People Refinancing (or Not)?

It’s no surprise that when rates nudge higher, fewer people rush to refinance. The Mortgage Bankers Association reported a pretty significant drop of 27% week-over-week in conventional refinance applications. This tells me that a lot of folks are seeing these rates and deciding to hold off for now.

However, I've worked in this space for a while, and I know that not everyone is in the same boat. Homeowners who secured their mortgages back in the peak years of 2023 and 2024, when rates were hovering around 7% to 8%, might still find today's rates quite attractive. For them, refinancing could still mean a noticeable reduction in their monthly payments, even with this small uptick.

Interestingly, while refinance applications are down, the purchase market is showing some life. Applications for buying a home actually rose by 7.8% recently. This makes sense as we head into spring, a traditionally busy time for home sales. People are still buying houses, even if borrowing is a bit more expensive than it was a few months ago.

The Big Picture: What's Driving These Moves?

It’s easy to just look at the number, but what’s actually causing these mortgage rates to fluctuate? There are a few major players at work:

  • Global Unrest: Let’s be honest, the ongoing conflict in Iran is a huge anxiety for the markets. It's pushing oil prices up, and with them, broader concerns about global inflation. When inflation fears rise, it often means higher interest rates. Think about it: oil is used to make almost everything, so when its price goes up, costs for businesses and consumers tend to follow.
  • The Federal Reserve's Strategy: The Federal Reserve made its latest decision on March 18th, keeping its main interest rate steady in the 3.50%–3.75% range. What’s more telling, though, is their forecast: they're now anticipating only one rate cut for the entire year of 2026. Fed Chair Jerome Powell has made it clear that these cuts are on hold until they see more solid proof that inflation is truly cooling down. This signals a more cautious approach from the central bank, which has a direct impact on borrowing costs across the economy.
  • Treasury Yields – The Silent Partner: Mortgage rates tend to follow the 10-year Treasury yield very closely. Right now, that yield has climbed to 4.32%. When investors are worried about the economy or inflation, they often demand higher returns on bonds, pushing yields up. Since mortgages are essentially long-term bonds, when Treasury yields go up, mortgage rates usually follow suit. It’s a pretty direct correlation that affects millions of homeowners.
  • Inflation Numbers Don't Lie: We’ve seen the latest reports on Producer Price Index (PPI) and Consumer Price Index (CPI), and unfortunately, they’ve come in a bit hotter than economists predicted. This means prices are still climbing, both for businesses at the wholesale level and for us as consumers. Persistent inflation is a major signal to the Fed and the markets that further rate hikes or at least sustained higher rates are necessary.

My Take: What You Really Need to Know

From my experience, the current market feels… well, a little nervous. The CNN Fear & Greed Index often shows a “fear” sentiment, which can lead to pretty wild swings in rates from day to day. It’s this uncertainty that makes planning tough for everyone.

One thing I’ve been telling clients is this: if you were planning to refinance and felt good about rates around 6.0% to 6.5% for 2026, we might be seeing those higher ends of that spectrum becoming the norm, at least for now. Given the global tensions and the Fed's stance, locking in a rate sooner rather than later might be a wise move if you’re ready to refinance. Waiting for rates to drop significantly might mean missing out on the best opportunities available.

And what about the housing shortage? While higher rates do make buying a home less affordable, we're also seeing housing inventory start to level off. This means that even with the higher borrowing costs, people looking to buy might actually have more choices to look at than they did just a few months ago. It’s a bit of a balancing act between affordability and availability.

Key Takeaways for Today:

  • The 30-year fixed refinance rate is now at 6.74%, a slight increase of 2 basis points from last week.
  • Refinancing demand has dipped, but people are still buying homes, with purchase applications showing seasonal strength.
  • The main forces pushing up borrowing costs are stubborn inflation, global geopolitical issues, and rising 10-year Treasury yields.
  • Experts are still forecasting rates to stay within the 6.0% to 6.5% range for 2026, but expect more twists and turns.
  • If you've been thinking about refinancing, it might be a good time to consider locking in your rate sooner rather than later.

The Bottom Line

Right now, mortgage refinance rates are at some of their highest points of 2026. This is definitely changing how homeowners are approaching refinancing – a lot fewer applications are coming in. For most people, refinancing might not make as much financial sense as it did a few months back. However, if you’ve got an older mortgage with a really high interest rate, there might still be some good deals to be found. With ongoing worries about inflation and global stability, interest rates are likely to stay elevated. The housing market is facing a bit of a challenge this spring, but maybe, just maybe, the slight increase in available homes will offer some folks a glimmer of hope if they're looking to buy.

🏡 2 New Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 22, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Mortgage Refinance Demand Drops Sharply by 19% in March 2026

March 22, 2026 by Marco Santarelli

Mortgage Refinance Demand Drops Sharply by 19% in March 2026

If you've been thinking about refinancing your mortgage, you're probably not alone in rethinking that strategy right now. My own gut feeling, supported by the latest numbers from the Mortgage Bankers Association, tells me that mortgage refinance demand in the United States took a sharp and sudden turn south in mid-March 2026. We saw the Refinance Index drop by a significant 19% for the week ending March 13th, officially putting an end to a month-long period of growth and signaling that rising borrowing costs are making homeowners pause.

It’s always interesting to watch how quickly market sentiment can shift, isn't it? Just when it seemed like homeowners were getting comfortable with slightly better rates, the rug was pulled out from under them. As someone who's followed the housing market for a while, this kind of volatility isn't entirely unexpected, especially when you factor in the bigger global picture.

Mortgage Refinance Demand Drops Sharply by 19% in March 2026

What's Behind This Sudden Slump?

Several factors are clearly colliding to create this perfect storm for refinancers.

1. The Interest Rate Rollercoaster:

The most immediate and impactful reason is the sharp rise in interest rates. The average contract rate for a 30-year fixed-rate mortgage climbed to 6.30% for the week ending March 13th. This might not sound like a massive jump on its own – it’s a 11 basis point increase from the previous week – but it's the highest we've seen this year, beating out December 2025 levels. When you're talking about mortgages, even small percentage point changes translate into significant dollar amounts over the life of a loan, making borrowers think twice.

2. Global Tensions Brewing:

Beyond just our mortgage rates, the wider economic environment is a big player. Rising Treasury yields, which are closely tied to mortgage rates, have been pushed higher by a pretty tense international situation. Geopolitical conflict in the Middle East has kept oil prices elevated, and this is stoking a familiar fear: a broader inflationary shock. When inflation heats up, it often leads to higher interest rates across the board, and that’s exactly what we're seeing reflected in mortgage markets.

3. The Fed's Balancing Act:

While the Federal Reserve decided to keep interest rates steady at their March meeting, the lead-up to that decision was anything but calm. Earlier volatility and the pause in anticipated rate cuts by the Fed have contributed to this upward pressure on mortgage yields. It feels like the Fed is walking a tightrope, trying to control inflation without completely derailing the economy, and this uncertainty trickles down into all borrowing costs.

A Closer Look at the Numbers

Let’s break down what happened during the week ending March 13, 2026, according to the Mortgage Bankers Association:

Metric Change (Week-over-Week) Current Level/Status
Refinance Index -19% Leading the overall decline
30-Year Fixed Rate +11 bps 6.30% (Highest in 2026)
Purchase Index +1% Showing resilience into spring season
Total Applications -10.9% Sharpest drop since Sept. 2025

Notice how the Purchase Index actually saw a slight increase? This suggests that while people looking to buy homes are still active, those aiming to refinance existing mortgages are hitting the brakes pretty hard. It’s a Tale of Two Markets, if you will.

Still Better Than Last Year?

Now, before we get too gloomy, it’s important to put this sharp weekly drop into perspective. Even with this recent plunge, refinance activity is still significantly higher than it was around this time last year. We’re talking about activity levels 69% to 70% higher than the same week in 2025.

And here’s another key point: current rates, at 6.30%, are still lower than they were a year ago. Back in early March 2025, the average rate for a 30-year mortgage was around 6.67%. That's a difference of about 42 to 45 basis points. So, while rates have gone up recently, they haven't completely erased the advantage homeowners might have had compared to a year ago.

However, the conventional refinance applications felt the brunt of this downturn, dropping by a considerable 27% over the week. This segment of the market is often the most sensitive to rate changes, and its significant decline underscores just how much impact the current rate environment is having.

What Does This Mean for Homeowners and the Market?

My take on this is that we're seeing a very natural market correction. Homeowners who were aggressively refinancing to capture lower rates have likely already done so. Now, with rates ticking up and uncertainty in the air, the financial incentive to refinance diminishes considerably for many. The cost savings just aren't as compelling when rates are on the rise, and the risk of higher payments if rates continue to climb might make people hesitant.

This lull in refinance activity could also have a ripple effect. Less refinancing means fewer transactions, which can impact lenders, mortgage brokers, and related industries. It also means homeowners are likely to be more settled in their current mortgages for longer.

Looking ahead, I'll be watching to see if this trend continues or if rates stabilize or even decline again. The Federal Reserve's next moves, along with developments in global markets, will be critical. For now, it seems the refinance party has been put on hold.

🏡 2 New Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 19, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 22: 30-Year Fixed Rises to 6.31%, a Six-Month High

March 22, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or refinancing an existing mortgage, you've probably been keeping a close eye on interest rates. As of Sunday, March 22, 2026, today's mortgage rates have reached their highest point since September of last year, a trend that’s making waves in the housing market. The 30-year fixed mortgage rate is now averaging a solid 6.31%, and the 15-year fixed rate has ticked up to 5.77%. This isn't just a small blip; it reflects a broader economic story that's worth understanding if you're navigating the current real estate environment.

It feels like just yesterday we were seeing rates dip below the 6% mark, and honestly, it’s a bit of a jolt to see them climb again. This shift is a stark reminder of how sensitive the housing market is to larger economic forces. From my perspective, when rates move like this, it signals that several factors are at play, and it’s not just a random fluctuation.

Today's Mortgage Rates, March 22: 30-Year Fixed Rises to 6.31%, a Six-Month High

Let’s break down the numbers you need to know, directly from Zillow, which is a go-to source for this kind of data. As of March 22, 2026, these are the rates we're seeing:

Mortgage Type Interest Rate
30-Year Fixed 6.31%
20-Year Fixed 6.29%
15-Year Fixed 5.77%
5/1 ARM 6.36%
7/1 ARM 6.34%
30-Year VA 5.85%
15-Year VA 5.47%
5/1 VA 5.39%

These figures are significant because they represent the highest we’ve seen in about six months. This means that for anyone taking out a new mortgage or considering refinancing an older, higher-rate loan, the costs involved have just gone up. It puts a bit more pressure on wallets, plain and simple.

Why Are Rates Going Up? It's Not Just One Thing.

There are a few big reasons why we're seeing this upward trend in mortgage rates. It’s a confluence of global events and domestic economic policy that's pushing borrowing costs higher.

  • Inflation Woes: The biggest story continues to be inflation. Even though the Federal Reserve has been working to keep it in check, stubborn inflation concerns are making lenders nervous. When inflation is high, the money you borrow today is worth less in the future, so lenders need to charge more interest to compensate.
  • Global Economic Jitters: The world feels a little uncertain right now. The ongoing conflict with Iran, for instance, has really shaken global markets. When oil prices jump above $100 a barrel, as they have recently, it directly contributes to inflation. This kind of global instability always makes investors a bit more cautious, and that caution gets passed on to borrowing costs.
  • The Fed's Tightrope Walk: The Federal Reserve held its benchmark interest rate steady at 3.5%–3.75% during its March 18 meeting. While this might seem like good news, keeping the federal funds rate high signals the Fed's continued focus on fighting inflation. It also means the cost of borrowing money for banks remains elevated, which in turn influences the rates they offer to consumers. They’ve only projected one rate cut for late 2026, which doesn't offer much immediate relief.
  • Bond Market Signals: Longer-term government bonds are a key indicator for mortgage rates. The 10-year Treasury yield recently shot up to 4.303%. When Treasury yields rise, it generally means investors are demanding more return for lending their money, and this directly correlates with higher mortgage rates.

How This is Affecting Homeowners and Buyers

When mortgage rates rise, it doesn’t just affect the numbers on a spreadsheet; it has real-world consequences for real people.

  • The Affordability Squeeze: For those looking to buy, especially for the first time, this jump is noticeable. Moving from rates below 6% just a month ago to over 6.3% can mean an extra few hundred dollars on your monthly mortgage payment. That can make a significant difference in what kind of home people can afford or even if they can enter the market at all. I’ve seen firsthand how quickly affordability can change when rates shift even a quarter of a percent.
  • Refinancing Gets Less Appealing: Homeowners who locked in rates below 6% are likely feeling pretty good about that decision right now. With rates climbing, the incentive to refinance has dwindled significantly. Why would you trade a 5.5% rate for a 6.31% rate? This is why we're seeing a shift in how people access home equity.
  • Turning to HELOCs and Home Equity Loans: Instead of refinancing their primary mortgage, many homeowners are tapping into their home equity through Home Equity Lines of Credit (HELOCs) or home equity loans. The average rates for these are currently around 7.20% for HELOCs and 7.47% for home equity loans. While these rates are higher than primary mortgages, they allow homeowners to keep their existing low mortgage rate and still access cash for renovations, debt consolidation, or other needs. It’s a smart move for many to preserve their prime mortgage terms.
  • Demand Takes a Hit: Unsurprisingly, this rate environment has cooled down buyer demand. Mortgage applications fell by 10.9% last week, and the drop in refinance activity was particularly sharp. When rates move further away from the magic 6% mark, people tend to put their buying or refinancing plans on hold.

What Does the Future Hold? Expert Predictions

Looking ahead, there’s a lot of discussion about where rates might go. While nobody has a crystal ball, some of the smartest minds in the industry have offered their insights.

  • Fannie Mae's View: Fannie Mae is predicting that by the end of 2026, rates could potentially settle back down to the 5.7%–5.9% range. This optimistic outlook assumes that economic growth will slow down from its current pace, which would typically lead to lower interest rates.
  • The Mortgage Bankers Association (MBA) Perspective: The MBA, on the other hand, is a bit more cautious. They forecast that rates will likely remain in the 6% to 6.5% range for the rest of 2026. Their view suggests that persistent inflation will keep borrowing costs elevated, even if they don't climb much higher from here.

From my experience, these predictions often come with a caveat: the economic situation is fluid. If there are unexpected developments, these forecasts could change.

Key Takeaways for Today's Market

If you're trying to make sense of all this, here are the most important things to remember as of March 22, 2026:

  • Rates are High (for now): We've hit a six-month high for mortgage rates, with the benchmark 30-year fixed at 6.31%.
  • Inflation and Global Issues Drive This: Persistent inflation, geopolitical conflicts, and rising bond yields are the main reasons for these higher costs.
  • Homeowners are Being Creative: To avoid higher primary mortgage rates, people are increasingly using HELOCs and home equity loans.
  • Buyers are Pulling Back: Demand has softened, although there's more inventory available, which can create opportunities for determined buyers.
  • Expect More of the Same (for a while): Analysts anticipate rates will stay elevated, with only modest potential for relief towards the end of the year.

The Bottom Line: Today's mortgage rates, March 22, have climbed to their highest levels since last fall, impacting both those looking to buy and those considering refinancing. The current economic climate, fueled by inflation and global uncertainty, is keeping borrowing costs high. While there's hope for stabilization later in 2026, the near future suggests continued challenges for affordability in the housing market. It’s a time for careful consideration and strategic planning for anyone involved in real estate.

🏡 Two Rentals With Strong Investor Potential

Pleasant Grove, AL
🏠 Property: 4th Ave (1549 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1549 sqft
💰 Price: $265,000 | Rent: $1,850
📊 Cap Rate: 6.2% | NOI: $1,368
📅 Year Built: 2026
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Pleasant Grove, AL
🏠 Property: 4th Ave (1856 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1856 sqft
💰 Price: $410,000 | Rent: $3,200
📊 Cap Rate: 5.8% | NOI: $1,981
📅 Year Built: 2026
📐 Price/Sq Ft: $221
🏙️ Neighborhood: B+

Two Pleasant Grove rentals—one affordable with higher cap rate vs one larger with stronger NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 22, 2026: 30-Year Refinance Rate Rises by 28 Basis Points

March 22, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

For anyone thinking about refinancing their mortgage, the news isn't exactly what we'd hoped for today, March 22, 2026. According to Zillow, the 30-year fixed refinance rate has held steady at 6.88% since yesterday, but that's a significant jump of 28 basis points compared to where we were just last week. This upward tick means borrowing money to adjust your current mortgage is costing more right now.

This 28-basis point jump is something we've been watching. It's not a surprise, given the bigger economic picture, but it does mean that the dream of snagging a much lower monthly payment through refinancing is a bit further out of reach for many homeowners at this exact moment. It’s a stark reminder of how quickly things can shift in the world of interest rates.

Mortgage Rates Today, March 22, 2026: 30-Year Refinance Rate Rises by 28 Basis Points

What the Numbers Tell Us

Let's break down what the numbers from Zillow are showing us today. While things are stable day-to-day, the jump from last week is the real story.

Here's a quick look at the refinance rates as of Sunday, March 22, 2026:

  • 30-Year Fixed Refinance: 6.88% (No change from yesterday)
  • 15-Year Fixed Refinance: 6.02%
  • 5-Year ARM Refinance: 7.32%

This 6.88% for a 30-year fixed refinance isn't exactly a shocker, but it's definitely higher than many homeowners were hoping for. It means what felt like a good opportunity last week is now less appealing.

Why Are Rates Moving Like This?

It’s easy to just see the numbers, but understanding why they move is key. A few big factors are at play right now, and they’re all linked.

The Federal Reserve's Gentle Pause

The Federal Reserve announced on March 18th that they'll be keeping interest rates where they are, sitting between 3.5% and 3.75%. This “pause” is a signal that they're being cautious. They're seeing inflation creeping up, and they don’t want to do anything that might make it worse. When the Fed keeps its rates steady, it usually means mortgage rates don’t move too wildly on a day-to-day basis, but it doesn’t automatically bring them down either.

Inflation Still Lingers

Speaking of inflation, the Fed has actually upped its prediction for inflation heading into the rest of 2026. They now expect it to be around 2.7%. This is a pretty significant upward revision. What's causing this? A couple of things, but climbing oil prices and ongoing global tensions are definitely major culprits. When the cost of things goes up, borrowing money tends to get more expensive too.

Global Worries Keep Yields High

The situation in the Middle East is still a concern, and unfortunately, this ongoing conflict is pushing up the cost of Treasury bonds, or Treasury yields. Why does this matter for your mortgage? Because mortgage rates are closely tied to these government bond yields. When yields go up, so do mortgage rates. It's a direct connection that many people don't realize.

What Does This Mean for Your Refinance Plans?

The drop in refinance applications tells the story here. Zillow reported a 19% plunge in refinance application volume week-over-week. This makes perfect sense. When rates jump like they did from last week to this week, people understandably put their plans on hold.

However, it’s important to look at the bigger picture. Even with this recent dip, refinance activity is still a whopping 70% higher than it was at this time last year, in 2025. This tells me that although the current rates aren’t as sweet as they were, there are still plenty of homeowners who see value in refinancing, perhaps for reasons other than just a lower monthly payment.

My experience tells me that a lot of homeowners, maybe as many as 82%, are already sitting pretty with mortgage rates below 6%. If you’re one of those lucky ones, refinancing to a rate that’s nearly 7% probably doesn’t make a lot of financial sense. You’re likely holding onto a very good deal. For these homeowners, refinancing would only make sense if they need to tap into their home equity (a cash-out refinance) or if they somehow have an older loan with an even higher rate.

What's Next for Mortgage Rates?

Looking ahead, the experts are offering some predictions. Groups like Fannie Mae and the Mortgage Bankers Association are forecasting that 30-year mortgage rates might settle in around 6% to 6.1% by the end of 2026.

This suggests that while we shouldn't expect a drastic drop in rates any time soon, there might be a bit of a stabilization. However, it’s crucial to remember that this is just an estimate. Things like inflation surprises or new global events could easily shift these forecasts. For now, it seems like we’re in for a period of moderate rates, with the potential for bumps along the way.

Key Takeaways from Today

So, to sum it all up:

  • The 30-year fixed refinance rate is currently at 6.88%. It's steady from yesterday, but noticeably higher by 28 basis points compared to last week.
  • Borrowers are reacting to the higher rates, with refinance demand dropping significantly this past week, although activity is still much higher than last year.
  • Most homeowners are already benefiting from significantly lower rates, making it less attractive to refinance unless they have specific needs like accessing cash.
  • Higher inflation and international issues are the main drivers pushing borrowing costs up.
  • The best guess for the rest of 2026 is that rates might settle closer to 6%–6.1%, but we should expect some ups and downs before then.

The Bottom Line

It’s a bit of a mixed bag out there for those looking to refinance. While the 30-year fixed refinance rate holding at 6.88% today might be stable, that jump from last week is cooling things down for borrowers. The market is definitely adjusting, with cash-out refinancing and home equity loans becoming more popular options for those who need to access their home's value. For now, it seems like patience might be a virtue, as we wait for rates to potentially settle closer to the 6% range later in the year.

🏡 2 New Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 21, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Mortgage Rates Surge to the Highest Level in Over Three Months

March 21, 2026 by Marco Santarelli

Mortgage Rates Surge to the Highest Level in Over Three Months

So, you've been dreaming of owning a home, maybe picturing yourself settling in just in time for warmer weather. Well, I've got some news that's a bit of a buzzkill. For the third week in a row, mortgage rates have been climbing, hitting their highest point in more than three months. As of March 21, 2026, you're looking at an average of 6.22% for a 30-year fixed mortgage, according to Freddie Mac. This jump is a tough pill to swallow, especially after we saw rates dip below 6% earlier in February. It’s a stark reminder that the housing market is a dynamic beast, and external forces can shift things faster than you might think.

Mortgage Rates Surge to the Highest Level in Over Three Months

The Triple Threat: What's Driving This Rate Hike?

I always try to break down these market movements into understandable pieces, and in this case, there are three main culprits behind this recent spike in mortgage rates:

1. The Shadow of Geopolitical Conflict

Let’s be frank, the ongoing war with Iran has cast a long, unsettling shadow over financial markets. When major global conflicts erupt, uncertainty takes hold. Investors get nervous, and that nervousness always translates into higher borrowing costs. It’s like a ripple effect; a shaky global picture makes lenders want more for their money, and that translates to higher mortgage rates for us.

2. Energy Prices: The Inflationary Spark

Directly tied to the geopolitical situation, we’ve seen oil prices skyrocket, pushing past the $100 a barrel mark. This isn't just about the gas you put in your car; high energy prices are a fundamental driver of inflation. Think about it: everything from the food you buy to the materials used to build a house has to be transported. When fuel costs go up, those costs get passed along. This surge in energy prices is feeding fears that inflation won't be as quick to tamedown as we'd hoped.

3. The Federal Reserve's “Wait-and-See” Approach

Up until recently, many of us (myself included!) were anticipating the Federal Reserve to start lowering interest rates, which would almost certainly bring mortgage rates down with them. However, those plans have been put on hold. The Fed, on March 18th, decided to keep the federal funds rate steady at 3.5%–3.75%. This signals a cautious stance, a “wait-and-see” when it comes to future rate cuts. With inflation still a concern and the global situation unstable, the Fed is holding its cards close to its chest, which means less downward pressure on mortgage rates than we’d hoped for.

From the Fed's Perspective: Why the Pause?

I find it crucial to understand the Fed's reasoning. They’re tasked with balancing a lot: keeping inflation in check and fostering economic growth. While they’ve made progress on inflation, the lingering threats of geopolitical instability and those stubborn energy prices mean they’re not ready to declare victory. Their recent decision to hold rates steady suggests they’re looking for more sustained evidence that inflation is truly under control before they start making borrowing cheaper. This cautious approach, while sensible from an economic stability standpoint, directly impacts our ability to afford homes.

How This is Affecting Your Wallet and the Housing Market

So, what does this all mean for you, the potential homebuyer? It’s not just about a number on a screen; it has real-world consequences.

The Application Slump: A Clear Sign of Hesitation

The numbers don’t lie. The week ending March 13th saw a significant drop in mortgage applications – down a whopping 10.9%. Refinance applications took an even bigger hit, falling nearly 26%. This tells me that as borrowing costs have risen, many people are hitting the pause button on their homebuying plans. It’s a natural reaction when the monthly payment suddenly becomes a lot more daunting.

Spring Season Setback: Not the Warm Welcome We Expected

This is the time of year when the housing market usually heats up. Families are looking to move before the new school year, and a lot of buyers are eager to get into a new home for the summer. However, these surging rates are throwing a wrench into that traditional spring buying season. The increased cost of borrowing means buyers have less purchasing power, or they might need to adjust their expectations on the type of home they can afford. It’s a real setback for many who were counting on this period.

The “Locked-In” Homeowner Dilemma

Now, let's talk about inventory. While the good news is that inventory has actually increased by about 20% year-over-year, there’s a catch. Many homeowners who secured mortgages when rates were significantly lower are hesitant to sell. Why would they trade a 3% or 4% rate for a 6% or 7% rate when buying their next home? This “locked-in” effect continues to limit the supply of existing homes on the market, which can keep prices from falling even with higher rates. It’s a bit of a stalemate for some.

Looking Ahead: What Do the Experts Say?

As for the rest of 2026, the outlook is a bit murky, but there are some projections. Agencies like Fannie Mae and the Mortgage Bankers Association are forecasting rates to settle between 6.1% and 6.2% for the year. That’s still higher than what we saw recently, but it suggests a potential stabilization. However, they also emphasize that volatility remains high. This means we could still see ups and downs.

Many economists and Fed officials still believe there's a good chance of at least one more rate cut before the end of 2026, provided inflation continues to trend downwards. This is the crucial “if.” If inflation proves stubborn, or if other global events cause further economic shocks, those rate cuts could be delayed or even cancelled.

My Take: Navigating the Current Climate

From my perspective, this situation demands a patient and informed approach. If you were planning to buy, it's essential to re-evaluate your budget. Can you still afford the home you had in mind with these higher rates, or do you need to look at less expensive options or save for a larger down payment? For those looking to refinance, unless you have a very specific financial situation, refinancing now probably doesn't make much sense.

The key takeaway is that the days of incredibly low mortgage rates might be behind us for a while. We're in a period of adjustment. Staying informed about economic news, understanding the drivers behind rate movements, and working closely with a trusted mortgage professional will be more important than ever as you navigate your homeownership journey. It's a complex time, but with the right knowledge and strategy, you can still make smart decisions.

🏡 Two Rentals With Strong Investor Potential

Pleasant Grove, AL
🏠 Property: 4th Ave (1549 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1549 sqft
💰 Price: $265,000 | Rent: $1,850
📊 Cap Rate: 6.2% | NOI: $1,368
📅 Year Built: 2026
📐 Price/Sq Ft: $172
🏙️ Neighborhood: B+

VS

Pleasant Grove, AL
🏠 Property: 4th Ave (1856 sqft)
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1856 sqft
💰 Price: $410,000 | Rent: $3,200
📊 Cap Rate: 5.8% | NOI: $1,981
📅 Year Built: 2026
📐 Price/Sq Ft: $221
🏙️ Neighborhood: B+

Two Pleasant Grove rentals—one affordable with higher cap rate vs one larger with stronger NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

  • « Previous Page
  • 1
  • …
  • 40
  • 41
  • 42
  • 43
  • 44
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...