Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Today’s Mortgage Rates, March 17: 30-Year Fixed Surges to 6.12% Amid Bond Market Volatility

March 17, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

On Tuesday, March 17, 2026, the dream of ultra-low mortgage rates seems to be fading as quickly as it arrived. According to Zillow, the average 30-year fixed rate is now 6.12%. The 15-year loan is 5.65%. We're seeing rates climb back up to levels we haven't experienced since the holiday season of 2025. This isn't just a random fluctuation; it's a direct response to the choppy waters in the bond market, stirred up by ongoing global events. These unsettling times are sparking inflation worries, pushing up Treasury yields, and ultimately, making borrowing money for a home more expensive.

Today's Mortgage Rates, March 17: 30-Year Fixed Surges to 6.12% Amid Bond Market Volatility

The average rates on Tuesday, March 17, 2026, are as follows (Zillow):

Loan Type Average Rate
30-Year Fixed 6.12%
20-Year Fixed 6.18%
15-Year Fixed 5.65%
5/1 ARM 6.34%
7/1 ARM 6.31%
30-Year VA 5.74%
15-Year VA 5.26%
5/1 VA 5.41%

Seeing these numbers, especially the 30-year fixed rate nudging past 6.10%, is a noticeable shift from just a few weeks ago when we briefly dipped below that important psychological barrier. It feels like we've taken a step back in time, revisiting the mortgage rate environment of late last year.

What's Fueling This Mortgage Rate Surge?

It's easy to just look at the numbers and feel a pang of disappointment, especially if you were hoping to lock in a historically low rate. But understanding why these rates are moving is key to making smart financial decisions. The big driver right now is the escalating conflict in the Middle East. This isn't just a headline; it has a very real impact on the global economy. Specifically, it's causing significant volatility in the bond market.

When there's uncertainty and fear about inflation, investors tend to pull their money out of more stable, lower-yield investments and move towards assets that are seen as safer, or they demand higher returns to compensate for the risk. This pushes up the yields on things like the 10-year Treasury note, which is a fundamental benchmark that mortgage rates follow very closely. We've seen the 10-year Treasury yield climb above 4.25%, and that directly translates to higher borrowing costs for mortgages.

This spike is a significant reversal. Only about two weeks ago, the 30-year fixed rate was hovering around 5.98%. It was a brief moment of relief, a chance for some buyers and refinancers to snag a rate under 6%. Now, we're back to that three-month high territory, mirroring the 6.15% to 6.22% range we saw in mid-to-late December of last year.

While this jump feels significant, it’s worth remembering where we were just a year ago. Back in March 2025, the average 30-year fixed mortgage rate was a much higher 6.65%. So, while today’s rates are certainly not low compared to the recent dip, they are still a welcome improvement from the peaks we experienced in 2025. Thinking about this historical context can help put the current situation into perspective.

Looking Ahead: Forecasts for 2026

So, what does the rest of 2026 hold for mortgage rates? This is the million-dollar question, and honestly, it’s not as clear-cut as we might hope.

Big players in the housing market, like Fannie Mae and the Mortgage Bankers Association (MBA), have been forecasting a relatively stable year for the 30-year fixed mortgage rate, with averages expected to hover around 6.10% for the remainder of 2026. This would imply that today's rates are pretty much what we can expect for a while.

However, the economic picture has become more complicated. The Federal Reserve’s plans for cutting interest rates, which often lead to lower mortgage rates, have been thrown into disarray. The “wartime inflation” concerns – that's the term some economists are using for the inflationary pressures driven by global conflicts and potential supply chain disruptions – are making the Fed hesitate. Instead of a steady stream of cuts, some analysts are now warning that we might see zero Fed rate cuts in 2026, especially if oil prices continue to stay high due to geopolitical tensions.

This is a pretty significant development. For months, the expectation was that the Fed would start easing monetary policy, which would naturally put downward pressure on mortgage rates. If that doesn't happen, or is significantly delayed, it means the rates we're seeing now could persist longer than anticipated. We'll all be watching the Fed’s upcoming meetings very closely for any signals or adjustments to their long-term projections.

What Does This Mean for You as a Borrower?

Navigating the mortgage market today requires a bit of a strategic mindset. Here’s what these current rates and future outlooks might mean for your homeownership plans:

  • Stay Aware of Volatility: The biggest takeaway is that rates are incredibly sensitive to global events. What happens in the Middle East, or anywhere else significant tensions arise, can directly impact your mortgage payment. This means timing is more important than ever.
  • Consider Locking In: With rates back above the 6% mark for the 30-year fixed, and with the uncertainty surrounding future Fed actions, for those who have found a home they love and have a solid pre-approval, now might be a good time to lock in your rate. This gives you certainty and protects you from any further upward swings. It’s a personal decision, of course, but it’s a strategy many people consider when rates are trending up.
  • Keep the Bigger Picture in Mind: Yes, 6.12% feels higher than 5.98%, but it’s still significantly lower than the 6.65% average from last year. If you were priced out or missed the opportunity to buy or refinance in 2025, today’s rates, while elevated from recent lows, still offer possibilities that weren't available not too long ago. Don't let the recent uptick completely discourage you if you've been waiting for a good opportunity.

The Bottom Line

As of March 17, 2026, mortgage rates have taken a notable jump, with the 30-year fixed rate reaching 6.12%. This surge is a direct consequence of global economic anxieties, particularly the conflict in the Middle East, which has sent Treasury yields climbing. While forecasts suggest rates might remain relatively stable around the 6% level for the rest of the year, the possibility of persistent inflation and hesitation from the Federal Reserve on rate cuts means we should all be prepared for continued market choppiness. For borrowers, this environment calls for vigilance, strategic planning, and a keen eye on those economic headlines.

🏡 Two Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

30-Year Fixed Mortgage Rate Drops Steeply by 54 Basis Points

March 17, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Drops Steeply by 54 Basis Points

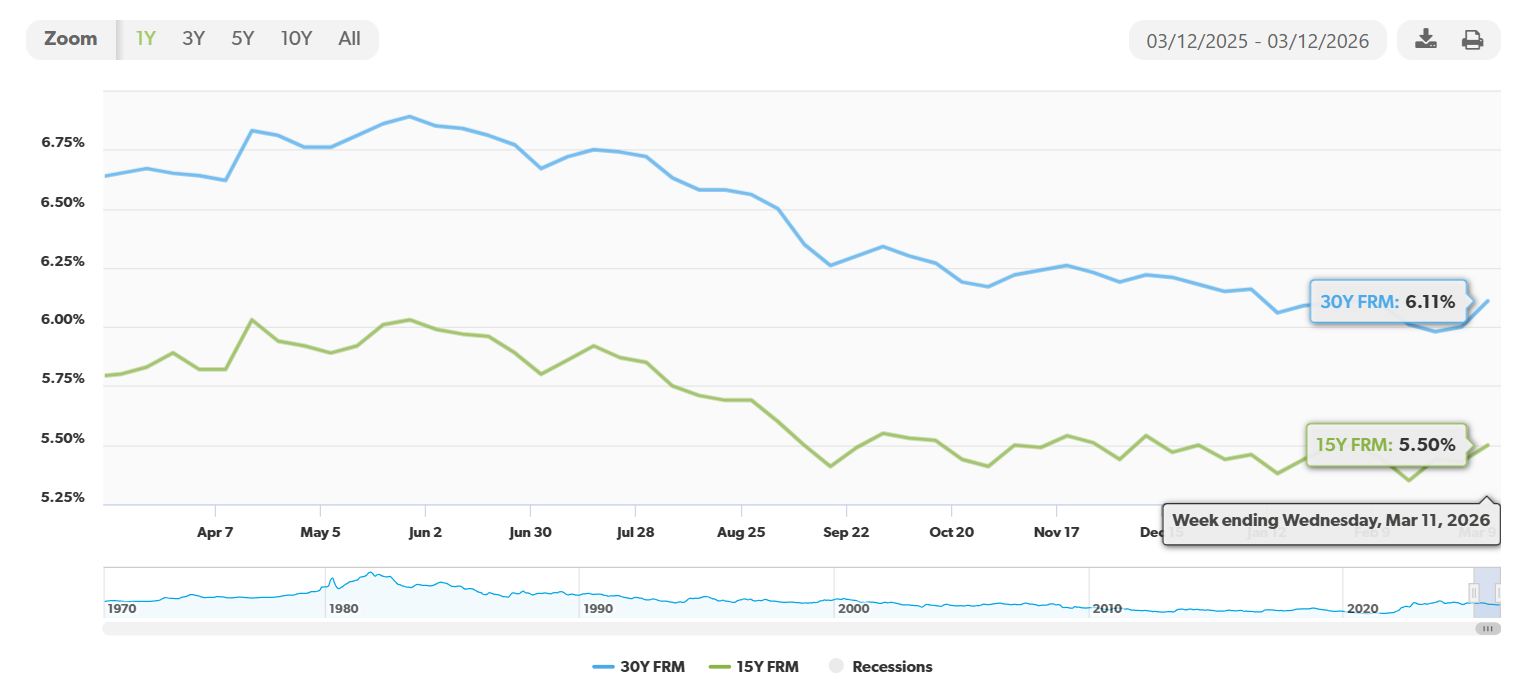
If you've been dreaming of owning a home or looking to refinance your current mortgage, I've got some welcome news for you. The average 30-year fixed mortgage rate has gone down by a significant 54 basis points compared to this time last year. This isn't just a small blip on the radar; it's a notable shift that could make a real difference in your homeownership journey. As of Freddie Mac's Primary Mortgage Market Survey for the week ending March 12, 2026, the average reached 6.11%, a noticeable dip from the 6.65% we saw a year prior. It signals a potential shift that could unlock doors for many aspiring homeowners and provide relief for those looking to adjust their existing loans.

30-Year Fixed Mortgage Rate Drops Steeply by 54 Basis Points

What Exactly is a “Basis Point” and Why Does It Matter?

Before we dive deeper, let's quickly clarify what we mean by “basis points.” Think of it like this: one basis point is equal to one-hundredth of a percent (0.01%). So, a drop of 54 basis points translates to a 0.54% decrease in the mortgage rate. While that might sound small, when you're talking about the cost of borrowing hundreds of thousands of dollars over 30 years, that half-a-percent can add up to many thousands of dollars in savings.

30-Year Fixed Mortgage Rate Drops Steeply by 54 Basis Points
Freddie Mac

The Numbers: A Clearer Picture of the Drop

Freddie Mac's latest report provides some really valuable data, and I've put together a table to make it easy to see the changes. This isn't just about a single week's fluctuation; it's about looking at the bigger picture, including comparisons to last week, last month's average, and, most importantly, last year.

Here's a breakdown from the Primary Mortgage Market Survey® for the U.S. weekly averages as of March 12, 2026:

Mortgage Type Current Avg. (03/12/2026) 1-Week Change 1-Year Change Monthly Avg. 52-Week Avg. 52-Week Range
30-Yr Fixed FRM 6.11% +0.11% -0.54% 6.03% 6.44% 5.98% – 6.89%
15-Yr Fixed FRM 5.50% +0.07% -0.30% 5.43% 5.66% 5.35% – 6.03%

Note on Savings: The most impactful saving comes from the 30-year fixed rate's 0.54% year-over-year drop. Let's look at an example for a $300,000 loan.

  • At 6.65% (last year): Monthly Principal & Interest Payment = ~$1,943
  • At 6.11% (this year): Monthly Principal & Interest Payment = ~$1,827

That's a difference of $116 per month, or over $1,392 per year, in savings on principal and interest alone! Over the life of a 30-year mortgage, that's tens of thousands of dollars back in your pocket. It's this kind of tangible benefit that shows why tracking mortgage rates is so crucial.

Why the Recent Uptick Despite the Yearly Drop?

It's important to note that while the year-over-year comparison is fantastic news, the rate for the week ending March 12, 2026 (6.11%) is slightly up from the previous week (6.00%). This might seem confusing, but it's a common occurrence in the market, and Freddie Mac's Chief Economist, Sam Khater, offers some insight.

He mentions that buyers are still responding positively to rates in this current range, which is why we're seeing increased housing activity. Existing-home sales, for instance, went up 1.7% in February, and purchase applications have also seen an uptick as we head into the spring homebuying season. This resilience from buyers, even with minor weekly fluctuations, is a strong indicator of market health.

What's driving these small weekly swings? Often, it's a mix of factors. In this instance, economic news and global events can play a big role. The mention of “bond market jitters and inflation concerns stemming from the conflict in Iran” is particularly telling. Such geopolitical events can create uncertainty, leading investors to move their money, which in turn affects bond yields and, consequently, mortgage rates. It’s a reminder that the mortgage market doesn't exist in a vacuum.

Homebuyer Resilience: A Sign of a Healthy Market?

I've seen many markets over the years, and what strikes me about this situation is the apparent resilience of homebuyers. Despite the temporary bumps, the fact that activity is picking up suggests that people are seeing value and opportunity at these current rate levels. The spring homebuying season is traditionally a busy time, and it seems like buyers are eager to take advantage of the still-lower rates compared to last year.

This upward trend in existing-home sales and purchase applications is exactly what I’d expect to see when rates have fallen significantly over a longer period. It’s not just about the week-to-week numbers; it's about the sustained availability of more affordable financing.

Looking Back: A Brief Dip Below 6%

It's also worth remembering that rates have recently touched even lower points within the past few months. The data indicates that rates briefly dipped below the 6% threshold in late February, reaching their lowest point in over three years at 5.98%. While we've seen a slight reversal since then, this demonstrates that even more favorable conditions have been within reach. This historical context is crucial for understanding the current market dynamics.

What This Means for You: Potential Impact on Your Homeownership Goals

So, what does this 54 basis point drop in the 30-year fixed mortgage rate really mean for you?

  • For First-Time Homebuyers: This is a golden opportunity. The lower monthly payments can make a home more affordable, potentially allowing you to qualify for a larger loan or simply reduce your monthly burden, freeing up cash for other investments or expenses.
  • For Current Homeowners (Refinancing): If you have an older mortgage with a higher interest rate, now might be the perfect time to explore refinancing. Even if your current rate isn't extremely high, shaving off over half a percentage point can lead to significant savings over the remaining term of your loan. You can also potentially shorten your loan term or even pull out some equity for home improvements or other needs.
  • For Investors: Lower borrowing costs can improve the cash flow on investment properties, making them more attractive.

It's not just about the numbers on paper; it's about how these changes translate into real-world financial benefits. My advice? Don't just read the headlines; take the time to see how this affects your personal financial situation.

The Road Ahead: What to Watch For

While this recent drop is excellent news, the mortgage market is always influenced by a multitude of factors. We'll need to keep an eye on inflation data, Federal Reserve policy, and any further global events that could impact interest rates. However, for now, this significant decrease in the 30-year fixed mortgage rate is something to celebrate and act upon if it aligns with your financial goals.

🏡 Two High‑Yield Rental Properties With Strong Cash Flow

Fort Wayne, IN
🏠 Property: Cinema Crossing
🛏️ Beds/Baths: 6 Bed • 5 Bath • 3012 sqft
💰 Price: $500,000 | Rent: $4,200
📊 Cap Rate: 7.0% | NOI: $2,920
📅 Year Built: 2026
📐 Price/Sq Ft: $167
🏙️ Neighborhood: B-

VS

Port Charlotte, FL
🏠 Property: Arthur Ave
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1914 sqft
💰 Price: $349,900 | Rent: $2,295
📊 Cap Rate: 5.6% | NOI: $1,633
📅 Year Built: 2025
📐 Price/Sq Ft: $183
🏙️ Neighborhood: A+

Indiana’s large 6‑bed rental with higher cap rate vs Florida’s new A+ property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

Mortgage Rates Today, March 17, 2026: 30-Year Refinance Rate Rises by 12 Basis Points

March 17, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Tuesday, March 17, 2026, the average rate for a 30-year fixed-rate mortgage refinance has climbed to 6.72%, marking a 12-basis-point increase from last week and reaching a three-month high. This uptick in borrowing costs comes amidst a nervous market reacting to global events, particularly the recent outbreak of the U.S.–Iran war, which has investors worried about inflation and pushing Treasury yields higher.

It feels like just yesterday we were talking about rates dipping a little, and now we're seeing them tick back up. This is a familiar dance in the mortgage world, where global news can have a pretty quick impact on what you pay to borrow money for your home. For anyone looking to refinance, or even just buy a new place, understanding these movements is key to making smart financial decisions.

Mortgage Rates Today, March 17, 2026: 30-Year Refinance Rate Rises by 12 Basis Points

What's Pushing Rates Higher?

So, what’s behind this sudden jolt in mortgage rates? It’s a combination of factors, but the big one right now is the geopolitical tension stemming from the U.S.–Iran war. When there's uncertainty like this, especially involving major oil-producing regions, investors tend to get nervous. They often flock to safer investments, and this can push up the yields on government bonds, like Treasury notes. Mortgage rates, especially the benchmark 30-year fixed, tend to move in the same direction as these bond yields.

Think of it this way: if investors can get a better return on government bonds because of global worries, mortgage lenders have to offer higher rates to attract enough money to fund home loans. It’s all about supply and demand for cash.

Adding to this, we're seeing concerns about inflation creeping back up. The war is impacting oil prices, and higher energy costs have a domino effect on almost everything we buy. When inflation tickles upward, the Federal Reserve often feels pressure to keep borrowing costs high to try and cool things down.

According to data from Zillow, here’s a snapshot of what refinance rates looked like today:

  • 30-Year Fixed Refinance: 6.72% (up 12 basis points from last week's 6.60%)
  • 15-Year Fixed Refinance: 5.65% (down 16 basis points from 5.81%)
  • 5-Year ARM Refinance: 6.95% (down 19 basis points from 7.14%)

It’s interesting to see that while the 30-year fixed is going up, the 15-year fixed and the 5-year Adjustable-Rate Mortgage (ARM) actually saw slight decreases. This can happen because different loan types are influenced by slightly different parts of the bond market, but the overall trend, especially for longer-term fixed loans, is what most homeowners pay close attention to.

The Federal Reserve's Balancing Act

The Federal Reserve is in a tricky spot right now. They’ve been aiming to keep inflation in check without completely tanking the economy. With these new inflationary pressures from the conflict, it’s highly likely they’ll hold their ground at their upcoming March 18, 2026 meeting.

Before this recent geopolitical flare-up, many analysts thought we might see a few rate cuts from the Fed this year. Now? Those expectations have been significantly scaled back. Some are only predicting one cut, and even that might not happen until December, or potentially not at all. This signals that the Fed is prioritizing stability and fighting inflation over trying to stimulate borrowing and spending with lower rates.

Who is Still Refinancing?

Now, you might think that with rates going up, people would stop trying to refinance altogether. But surprisingly, refinance applications are actually quite active, especially when you compare it to this time last year. Why? Many homeowners locked in some pretty high rates back in 2023 and 2024 when the 30-year fixed was often above 7%. When rates dip even slightly into the mid-6% range, they see it as a golden opportunity to trim their monthly payments.

It’s a game of timing. If you can shave off a good chunk of your interest rate and your loan term, it can still be a smart move.

The Housing Market's Response

On the flip side, what about people looking to buy? It seems like buyers are slowly but surely getting used to the idea of rates being in the 6% range. We saw existing-home sales actually increase by 1.7% in February. This is a positive sign as we head into the spring homebuying season, suggesting that there’s still demand and people are finding ways to make it work, even with higher borrowing costs.

My Take: What Should You Do?

As someone who’s watched the mortgage market for a while, I know how frustrating it can be to see rates fluctuate. My personal advice? If you’re considering a refinance, you need to be strategic.

  • Rate Lock Advisory: Experts are divided right now. Some say wait and see if rates dip again. Others, me included, believe that when rates are this volatile, especially with a major global event and an upcoming Fed decision, it’s worth seriously considering locking in a rate if it meets your financial goals. You don't want to miss a good opportunity only to see rates climb even higher. The next few days will be crucial.
  • The Refinance Rule of Thumb: Remember that old saying? Refinancing usually makes sense if you can lower your rate by at least 0.5% to 1.0%. This helps ensure that the savings you get on your monthly payment over time outweigh the costs of closing the loan. Always do the math personally.
  • Long-Term View: Don't just focus on the daily ups and downs. Consider your long-term financial picture. Will this refinance save you money over the life of your loan? Does it help you meet other financial goals?

In Conclusion

Mortgage rates on March 17, 2026, are showing us that the market is still a bit unpredictable. The 30-year fixed refinance rate sitting at 6.72% is a sharp reminder of the impact that global events and economic concerns can have. While higher rates can feel like a setback, borrower activity remains surprisingly robust, with many homeowners still looking to improve their financial situation. With the Federal Reserve’s meeting on the horizon, the coming days will be a key period for understanding where mortgage rates might be heading as we move further into spring.

🏡 2 New Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 16, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 16: Wartime Inflation and Oil Prices Push Rates Higher

March 16, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Economic conditions in March 2026 have shifted the housing market, with mortgage rates reversing their recent downward trend. As of March 16, 2026, the average 30-year fixed mortgage rate has climbed back above the 6% threshold. According to Zillow, the average 30-year fixed mortgage rate has climbed to 6.08%. This isn't just a small blip; it's a clear signal that economic shifts are really making their presence felt in our housing dreams.

Today's Mortgage Rates, March 16: Wartime Inflation and Oil Prices Push Rates Higher

Where Do We Stand Today?

This recent climb signifies a pretty dynamic turn of events. The optimistic dip below 6% we saw in late February has been short-lived. It's a stark reminder that global events can have a surprisingly direct impact on our local housing markets.

Here’s a snapshot of what things are looking like, courtesy of Zillow:

Loan Type Average Rate (March 16, 2026)
30-Year Fixed 6.08%
20-Year Fixed 6.06%
15-Year Fixed 5.62%
5/1 ARM 6.05%
7/1 ARM 6.03%
30-Year VA 5.67%
15-Year VA 5.32%
5/1 VA 5.24%

As you can see, the longer you plan to pay off your home, the higher the current rate tends to be. The popular 30-year fixed is right in the thick of it, nudging just above that 6% psychological barrier.

What's Stirring Up These Rate Hikes?

It's not just random chance; there are some pretty significant forces at play pushing these rates higher:

  • Oil Prices and Global Turmoil: The big story right now is the disruption in the Middle East. Military actions, particularly involving Iran, have caused major headaches for oil supplies flowing through the Strait of Hormuz. We saw Brent crude prices shoot up to nearly $120 a barrel earlier this month. While it's settled a bit, hovering around $100, the instability is a major concern.
  • The Echo of Wartime Inflation: When oil prices surge, it's like a domino effect for inflation. Think about it – oil is a key ingredient in so many things we use and buy every day. Higher energy costs are directly feeding into expectations that prices will continue to rise, and that's something the markets and the Federal Reserve watch very closely.
  • Bond Market Jitters: All this talk of inflation makes investors nervous. You'll often see them start to sell off their bonds, which can drive up the yield on those bonds. The 10-year Treasury yield, a key benchmark for mortgage rates, has climbed to around 4.25%. Because mortgage rates tend to follow these Treasury yields pretty closely, this is a direct reason why we're seeing our mortgage rates increase.

The Federal Reserve's Next Move (or Lack Thereof)

The folks at the Federal Open Market Committee (FOMC) are meeting this week, specifically on March 17th and 18th. You can bet everyone will be watching closely.

  • Holding Steady: The overwhelming expectation – we're talking a 95% to 99% probability – is that the Fed will keep the federal funds rate exactly where it is, between 3.50% and 3.75%. They've been in this holding pattern for a bit, and it doesn't look like they're ready to budge yet.
  • Rate Cut Timeline Pushed Back: Remember when everyone was thinking the Fed might start cutting rates around June? Those thoughts have largely evaporated. Now, the buzz is that the first rate cut might not happen until September or even December. Some even think if oil prices stay this high, the Fed might decide to hold off on any cuts at all this year. That's a big shift from just a few months ago!
  • The “Dot Plot” Matters: This meeting's Summary of Economic Projections (SEP) will include the updated “dot plot.” This is essentially a look at what individual Federal Reserve officials think interest rates will do over the long term. Given the recent global events, how those dots move will be a crucial indicator of their thinking.

So, What Does This Mean for You?

Hearing about rising rates and economic uncertainty can be a bit daunting, especially if you're in the market for a home or looking to refinance.

  • Expect More Swings: I’d advise borrowers to brace themselves for continued choppiness in rates. Until the global tensions ease up and we get a clearer picture of inflation's path, mortgage rates are likely to be a bit unpredictable.
  • The “Lock-In” Question: This is where things get strategic. If you've found a home you love or are considering refinancing, now might be the time to really think about locking in your rate. Waiting for rates to drop further is a gamble, and the trends we're seeing right now suggest that waiting might cost you more in the long run. I've seen many clients who benefited from locking in when rates seemed stable, only to see them climb significantly afterward.
  • Housing Demand Holds Up: It's interesting, isn't it? Even with these higher rates, the demand for homes hasn't completely collapsed like it did when rates were in the 8% range back in late 2023. This tells me that while affordability is a concern, there are still plenty of motivated buyers out there, and I expect to see solid activity this spring. People are still looking for their piece of the pie.

The Bottom Line

As of March 16, 2026, we're looking at today's mortgage rates that have climbed back above the 6% mark for a 30-year fixed loan, averaging 6.08%. The main culprits behind this uptick are rising oil prices due to international conflicts, the resulting inflationary pressures, and the volatility in the bond market. While we expect the Fed to keep interest rates steady this week, their plans for future cuts have been pushed back. For anyone navigating the mortgage process, this environment really highlights the importance of making a smart, informed decision about when to lock in your rate. It’s a time for strategy, not speculation.

🏡 Two Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 16, 2026: 30-Year Refinance Rate Rises by 13 Basis Points

March 16, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Monday, March 16, 2026, the average rate for a 30-year fixed refinance has nudged up to 6.73%, a 13-basis-point increase from last week, according to data from Zillow. This shift, while seemingly small, is happening in a market that's keeping a close eye on global events and the upcoming Federal Reserve meeting.

Mortgage Rates Today, March 16, 2026: 30-Year Refinance Rate Rises by 13 Basis Points

What's Driving Today's Rates?

It’s not just one thing, but a mix of factors pushing and pulling on mortgage rates.

  • Geopolitical Squalls: We're seeing some real turbulence in the global arena. Reports of military action in Iran are creating uncertainty, which usually sends oil prices climbing. When oil prices go up, it tends to put upward pressure on inflation, and consequently, interest rates, including mortgage rates. Even though there are some signs that the U.S. economy might be cooling down a bit, these international events are keeping mortgage rates stubbornly above the 6% mark.
  • The Fed's Next Move: The Federal Reserve is set to meet on March 17th and 18th. While they don’t directly tell lenders what to charge for mortgages, their decisions on the benchmark interest rate have a big ripple effect. Most experts, myself included, expect them to keep the benchmark rate steady in the 3.50% to 3.75% range. The Fed’s commentary on inflation and the economy during these meetings is what really matters to the bond market, which in turn influences mortgage costs.
  • Treasury Yields' Shadow: If you’ve ever wondered why fixed-rate mortgages seem to march in step with Treasury yields, it’s because they largely do. Specifically, the 10-year Treasury yield is a key indicator. With all the global uncertainty we’re facing, those yields are staying elevated, which makes it more expensive for lenders to borrow money, and that cost gets passed on to us in the form of higher mortgage rates.

A Look at the Refinance Market

Even with rates inching up, the refinance market is surprisingly active.

  • A Resurgence in Refinancing: The Mortgage Bankers Association is reporting a massive 81% jump year-over-year in their Refinance Index. This tells me that a lot of homeowners who locked in rates above 7% back in 2023 and early 2024 are finally seeing a chance to save some serious money by refinancing now. It’s a smart move for them.
  • The “Lock-In” Effect Still Looms: However, I don't think we're going to see a full-blown refinance frenzy. The reality is, a huge number of homeowners – over 80% by my estimate – currently have mortgage rates below 6%. For them, the savings from refinancing might not be worth the hassle and closing costs. They’re pretty happy with their current situation.
  • Tapping into Home Equity: Because so many people are sitting on low mortgage rates, and home values have appreciated significantly, many are turning to other ways to access their home equity. We’re seeing a lot more interest in Home Equity Lines of Credit (HELOCs) and home equity loans. It’s a clever way to get funds without giving up that super-low primary mortgage rate.

What Experts Are Saying About the Rest of 2026

Looking ahead, the general consensus from major players like Fannie Mae and the Mortgage Bankers Association (MBA) is that we can expect relative stability for the rest of the year. They’re forecasting that the average 30-year fixed rate will likely stay hovering around the 6% mark.

Now, it’s my opinion that if inflation continues to cool down as expected and those geopolitical worries subside, we might see rates drift a bit lower, perhaps into the high 5s later in the year. But I wouldn’t bet the farm on it. Stability seems to be the more likely scenario.

What This Means for You

So, what’s the takeaway for anyone thinking about their mortgage?

  • If You Have a High Rate: If you’re one of the folks who refinanced or bought a home in the last couple of years at a rate above 7%, today’s rates present a genuine opportunity to lower your monthly payment and save a lot of money over the life of your loan. It’s worth exploring.
  • Consider Locking In: Given how volatile things can be with global events and economic news, if you find a rate that works for your budget, especially for a refinance, it might be wise to lock it in. Trying to time the market perfectly is a risky game.
  • Equity is Your Friend: If your primary mortgage rate is already fantastic, don’t forget about the equity you’ve built. HELOCs and home equity loans are still very attractive options for accessing that money for renovations, debt consolidation, or other major purchases.

The Bottom Line

On March 16, 2026, mortgage rates for refinancing are holding steady, with the 30-year fixed rate at 6.73%. While global tensions are keeping things a bit elevated, the market is seeing increased activity from those looking to get out from under higher-rate loans. For the foreseeable future, stability seems to be the name of the game, with a small possibility of rates easing if the economic winds blow favorably.

🏡 2 New Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 15, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 15: 30-Year Fixed Rises Above 6% Amid Geopolitical Instability

March 15, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Well, it’s March 15th, 2026, and if you’ve been keeping an eye on mortgage rates, you’ll notice they’ve nudged back up, crossing that 6% mark again. This isn’t a shocker, given the choppy global waters we're navigating. For many of us thinking about buying a home or refinancing, this is the critical question: how do today's mortgage rates affect our plans? As of Sunday, March 15, 2026, the average rate for a 30-year fixed mortgage has settled at 6.08%, according to Zillow.

This is a bit of a climb back from dipping below 6% just a few weeks ago, and it’s a clear signal that the market is still a bit on edge. While we're not seeing the sky-high rates of 2023, this recent upward tick is something worth paying attention to.

Today's Mortgage Rates, March 15: What You Need to Know Right Now

Why the Jump? A Look Under the Hood

It’s easy to just see the numbers, but understanding why rates move is key to making smart decisions. Right now, a couple of big factors are at play.

First, we’re seeing some serious ripples from geopolitical instability. Reports of military actions involving the U.S., Israel, and Iran have sent oil prices spiking to around $89 a barrel. When energy costs go up, it doesn’t just affect your gas tank; it tends to fan the flames of inflation. Higher inflation usually means that the yields on bonds go up, and guess what heavily influences mortgage rates? You got it – those bond yields. It's a domino effect from global events straight to your potential monthly payment.

Second, there's the ever-present Federal Reserve. The Fed is expected to keep its finger on the pause button, holding interest rates steady when they meet on March 17th and 18th. Now, the Fed doesn't directly set mortgage rates, but their signals about inflation and their economic outlook are a big deal. Their cautious approach, especially concerning inflation, is putting a cap on how low mortgage rates can really go.

The Spring Market is Stirring

Even with these rate ups and downs, it's interesting to see that buyer activity hasn't completely stalled. In fact, Zillow data shows that purchase applications actually rose by 7.8% in early March. This tells me that people are still eager to get into the housing market, especially as we head into the more traditional spring buying season. And it makes sense; compared to the 8% plus rates we saw in late 2023, where we are now still feels like a relative bargain for many.

It’s a bit of a balancing act. On one hand, rates have moved up. On the other, they’re still a far cry from the punishing highs of not too long ago. This can create a sense of urgency for some buyers who want to lock in a rate before they potentially climb further.

What the Experts See for the Rest of 2026

So, what’s the crystal ball telling us about the rest of the year? I’ve been following the forecasts from big names in the housing world like Fannie Mae and the Mortgage Bankers Association (MBA), and they seem to be pointing towards a period of relative calm. Their projections suggest that mortgage rates will likely hover in the 6.0% to 6.1% range for the remainder of 2026. This is good news for anyone hoping for some predictability.

However, and this is where my experience kicks in, it’s crucial to remember that forecasts are just that – forecasts. The economic world is full of “wildcards.” We’re talking about potential new trade tariffs, unexpected shifts in the job market, or even further international flare-ups. These could cause rates to dance around a bit more, possibly swinging anywhere from 5.7% to 6.5% throughout the year. So, while stability is the general expectation, don't be surprised by some bumps along the way.

Your Mortgage Rate Game Plan: What It Means for You

If you're in the market for a home or considering refinancing, here’s how I see today's numbers and trends impacting your decision-making:

  • The Opportunity Window is Still Open: While rates are above 6%, they’re still significantly better than the rates of last year. This presents a real chance to secure a more favorable interest rate on a home or a refinance compared to what many experienced in 2023. It's about seizing the moment.
  • Consider Locking It In: Given the current global uncertainties and the ongoing inflation concerns, many financial advisors (and frankly, my own gut feeling) would suggest that locking in your rate sooner rather than later is a smart move. Waiting for that absolute “perfect” bottom might mean missing out on a good rate altogether if the market takes an unexpected turn.
  • The Spring Market is Heating Up: The rise in purchase applications is a clear indicator. We're likely to see increased competition among buyers in the coming months. This means being prepared, pre-approved, and ready to act quickly when you find the right home.

The Bottom Line from My Perspective

As of March 15, 2026, we're seeing mortgage rates climb back above the 6% mark, largely due to global instability and concerns about inflation. This is a point where it's really important to stay informed and make a plan. Zillow's data shows the current averages, and while forecasts suggest general stability around 6% for the rest of the year, remember that unforeseen events can always shake things up.

For anyone looking to buy or refinance, there’s a delicate balance between acting decisively to secure a good rate and being aware of potential market fluctuations. My advice? Get your ducks in a row, understand your options, and make the move that feels right for your financial future. Don’t let the noise distract you from what’s important: securing a home at a manageable cost.

🏡 Two Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 15, 2026: 30-Year Refinance Rate Rises by 19 Basis Points

March 15, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Sunday, March 15, 2026, the 30-year fixed refinance rate has seen a slight bump, rising by 19 basis points to 6.69%, according to data from Zillow. While this is a modest increase, it’s important to remember that overall refinance rates are still sitting close to three-year lows, making it a potentially opportune time for many homeowners to consider refinancing.

This recent uptick in the 30-year fixed refinance rate is something homeowners have been watching closely. Coming in at 6.69%, it's up from last week's 6.50%. Now, 19 basis points might not sound like a lot, but in the world of mortgages, it can be the difference between saving a pretty penny or sticking with your current arrangement.

Mortgage Rates Today, March 15, 2026: 30-Year Refinance Rate Rises by 19 Basis Points

Mortgage Type Interest Rate Change from Last Week
30-Year Fixed 6.69% +19 Basis Points
15-Year Fixed 5.81% –
5-Year ARM 7.12% –

As someone who’s been following the housing market for a while, I can tell you that even small shifts in mortgage rates can have a big ripple effect. The fact that the 30-year fixed rate is climbing, even slightly, is a signal. It tells us that the market isn't entirely settled, and we need to pay attention to the bigger picture.

What's pushing rates around? Well, several factors are at play. The Federal Reserve is always a big one. They're scheduled to have a meeting from March 17-18, 2026. While most folks are expecting them to hold rates steady, any hints they drop about future interest rate cuts can send immediate tremors through the mortgage market. Think of it like a weather forecast – even a mention of possible rain can make people grab their umbrellas.

Beyond the Fed, we’ve got global concerns like oil prices and geopolitical tensions. These can create what advisors are calling “choppy” conditions. In simpler terms, it means there's a bit of uncertainty, and predicting where rates will land next week, let alone next month, is tricky. This is why many experts are advising people not to wait for the absolute perfect moment to refinance. If you've found a rate that works for you, especially if it’s a noticeable drop from what you’re paying now, it might be wise to lock it in.

Are You Eligible? The Refinance Surge Explained

Despite this slight increase, the good news is that the recent period of lower rates has really ignited demand for refinancing. Zillow’s data shows a massive jump in refinance applications, up a staggering 81% year-over-year. That's a huge comeback!

It's not just a few people jumping back in; refinances are now making up almost 40% of all mortgage lending. This is the biggest slice of the pie they've had in nearly two years. This tells me that a lot of homeowners are seeing the value in locking in a better rate.

Who is this good news for? Well, the number of borrowers who are in a good position to refinance has also grown. Zillow reports that there are now 5.4 million borrowers who are eligible for a refinance. This is the largest group we’ve seen since early 2022. If your current mortgage rate is significantly higher than what's available today – say, you’re paying north of 7% – you might be one of these fortunate individuals.

Lenders are also working hard to keep customers. They're currently retaining about one in three refinancing borrowers, which is the best retention rate they’ve seen since 2014. This means banks and mortgage companies are actively trying to keep your business if you're looking to refinance, which could translate to better service and potentially better terms for you.

The 1% Rule and When It Makes Sense to Refinance

So, how do you know if refinancing is the right move for you? I always bring up what’s often called the “1% rule.” Basically, if refinancing your mortgage can lower your interest rate by at least one full percentage point (for example, going from 7.5% down to 6.5%), it’s generally considered a solid move.

Of course, there are costs involved when you refinance. These are called closing costs, and they can add up, typically being around 2% or more of your loan amount. This is why it's crucial to do a little math. You need to figure out your “break-even point.” This is the point in time when the money you save on lower monthly payments will outweigh the closing costs you paid. If you plan on staying in your home for longer than that break-even point, refinancing is usually a smart financial decision.

Looking Ahead: What to Expect

Even with this slight uptick in the 30-year fixed refinance rate, the overall picture for refinancers remains quite positive. We're still in a range where rates are attractive compared to recent years. The strong demand we're seeing, the growing pool of eligible borrowers, and lenders' efforts to hold onto customers all point to refinancing being a major player in the mortgage market for at least the next few months.

For homeowners, this is still a golden window. If you have a mortgage with an interest rate above 7%, taking a look at what you could do today could lead to significant savings each month. It’s always worth exploring, even with that 19-basis-point increase. Keeping an eye on those Fed meetings and the global economic news is wise, but don't let the fear of missing out on a microscopic rate drop stop you from securing savings that can truly make a difference in your budget.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 14, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 14: Global Tensions Push 30-Year Fixed Rate to 6.08%

March 14, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of March 14th, 2026, the mortgage rate for a standard 30-year fixed loan is floating right around 6.08%. It's a bit of a jump from where we were earlier this month, but honestly, it's not entirely surprising given everything going on in the world. Things have been a little tense lately, and that definitely has a ripple effect, even on something as fundamental as buying a home.

We saw rates dip below 6% briefly, which was a welcome sigh of relief for many. However, the global stage has had other plans, and the market is reacting. It’s this constant push and pull that makes my job so fascinating. One minute you’re talking about how affordable it might be to buy, and the next you’re discussing energy prices and international affairs.

Today's Mortgage Rates, March 14: Global Tensions Push 30-Year Fixed Rate to 6.08%

To give you a clearer picture, here’s a quick rundown of how the rates are shaping up today. I always tell my clients to look at the full spectrum, not just the headline 30-year fixed. Sometimes, a different loan term might be a better fit.

Loan Type Interest Rate
30-Year Fixed 6.08%
20-Year Fixed 6.06%
15-Year Fixed 5.62%
5/1 ARM 6.05%
7/1 ARM 6.03%
30-Year VA 5.67%
15-Year VA 5.32%
5/1 VA 5.24%

You can see that the 15-year fixed options, both conventional and VA, are still offering a noticeable break from the longer-term fixed rates. And for our service members and veterans, the VA loan rates are particularly attractive.

Why Are Rates Moving Like This? The Big Picture Drivers

It’s never just one thing, is it? When it comes to mortgage rates, a lot of factors are always at play. This week, though, a couple of big ones are really grabbing the spotlight:

  • Geopolitical Jitters: There's been increased military action involving the U.S. and Israel in Iran. This kind of global instability makes investors nervous. When investors are nervous, they tend to shift their money around, and that often means bond yields get a bit more volatile. Since mortgage rates are closely tied to the bond market (specifically, the 10-year Treasury note), what happens overseas can definitely keep rates from dropping too much, or even push them up.
  • The Price of Oil and the Specter of Inflation: We’ve seen oil prices rocket past $92 a barrel. This is a huge red flag for inflation. Think about it: when fuel gets more expensive, everything that needs to be transported or produced using energy also becomes more expensive. This can create a kind of snowball effect, pushing up the overall cost of goods and services. Central banks, like our Federal Reserve, keep a close eye on inflation, because if it gets out of hand, they often have to raise interest rates to cool things down. And higher interest rates for the Fed generally mean higher mortgage rates for us. It’s a cycle, and right now, the inflation alarm bells are ringing louder.
  • The Federal Reserve's Next Move (or Lack Thereof): Even with some concerning economic news, like the loss of 92,000 jobs in February, the Fed is expected to keep its key interest rate steady at its meeting next week. This is important because the Fed's benchmark rate influences many other borrowing costs. While they’re not raising rates yet, their cautious approach signals they are still trying to balance supporting the economy with controlling inflation. This uncertainty itself can contribute to rate volatility.

Looking Ahead: What Do the Experts Say About 2026?

Predicting mortgage rates is a bit like predicting the weather – you can make educated guesses, but there are always surprises. However, economists and financial institutions have their eyes on the horizon, and their general sentiment for 2026 mortgage rates leans towards continued stability, with some ups and downs.

Here’s what some of the big players are forecasting:

  • Fannie Mae: They’re projecting that 30-year fixed mortgage rates will average around 6% for the rest of 2026 and into 2027. This suggests a period of relative calm, even if we see minor fluctuations.
  • Mortgage Bankers Association (MBA): Their outlook is pretty similar, expecting rates to stick close to 6.10% throughout 2026. It’s not a huge range, which can be good for planning.
  • Morgan Stanley: These folks see a little more potential movement. Their strategists are thinking that if government bond yields soften, we could see rates dip towards 5.50%–5.75% by mid-2026. However, they also anticipate a rebound in the latter half of the year, so it’s not a clear downhill slide.

From my perspective, the consensus is that while we might not see the super-low rates of a few years ago, we're also not likely to see another sharp spike upwards, unless something truly dramatic happens on the geopolitical or inflation front.

A Quick Look Back: How Do Today's Rates Compare?

It’s always helpful to have some historical context. Even though today’s rates are a bit higher than they were a couple of weeks ago, they’re still significantly lower than they were around this time last year. Back in March 2025, the average for a 30-year fixed was around 6.65%. So, while we're not in bargain-basement territory, borrowers today are definitely seeing an improvement compared to last year, which is something to appreciate.

The Bottom Line for March 14, 2026

So, where does that leave us today? Today’s mortgage rates on March 14th, 2026, are holding steady in the low 6% range, with the popular 30-year fixed landing at 6.08%. The global scene is a bit of a wild card, with international tensions and rising oil prices injecting some caution into the market. This is keeping rates from falling further and might even push them up slightly.

However, the good news is that these rates are still an improvement over where we were a year ago. For anyone looking to buy a home or refinance an existing mortgage, this environment still presents opportunities. My advice? Don't just look at the headline rate. Talk to different lenders, understand all the fees, and consider what makes sense for your specific financial situation and your long-term goals. Navigating a market like this requires a bit of patience and a lot of smart choices.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

How Builders Are Lowering Mortgage Rates to Sell Move-In Ready Homes

March 14, 2026 by Marco Santarelli

How Builders Are Lowering Mortgage Rates to Sell Move-In Ready Homes

If you're dreaming of owning a new home in 2026, you might be in luck. Homebuilders are getting creative, offering some seriously attractive incentives, especially when it comes to lowering mortgage rates on their completed, move-in ready properties. This isn't just about a small discount; it’s a strategic move by builders to make owning a brand-new home more accessible despite the current economic climate. In short, builders are stepping in to significantly reduce your monthly mortgage payment on these available homes by essentially pre-paying a portion of your interest.

How Builders Are Lowering Mortgage Rates to Sell Move-In Ready Homes

As someone who’s been following the housing market for a while, I’ve seen trends come and go, but this feels like a significant shift. Housing affordability has been a big hurdle for many potential buyers. With mortgage rates still higher than many are used to, getting into a new home can seem out of reach. That’s where builders are stepping in, using their resources and often their own affiliated mortgage companies to make those dreams a reality for folks who want to move in now.

Why the Sudden Push for Lower Rates?

It boils down to one thing: inventory. Builders have a lot of finished homes – often called “quick move-in” or “spec” homes – that are ready for someone to unpack their bags. These aren't houses they're building from scratch for a specific buyer; they're already built and waiting. When mortgage rates climb, it makes it harder for people to afford those homes. Instead of letting these properties sit, builders are pulling out all the stops to get them sold.

Think about it from their perspective. They’ve invested a ton of money into building these homes. They need to move them to keep their business going. Traditional price cuts can sometimes hurt the value of their other homes in the same neighborhood, so they prefer to offer incentives that don't show up as a reduced base price on public records. Lowering mortgage rates is a brilliant way to do this.

The Secret Sauce: How Builders Are Actually Lowering Your Rate

You might be wondering, “How can they just lower my mortgage rate?” It's a combination of smart financial strategies and leveraging their size. Here's a breakdown of what I'm seeing:

  • Forward Commitments (The “Bulk Buy”): Large builders are like financial powerhouses. They have the scale to go to mortgage lenders or investors and say, “We're going to need a lot of mortgage money.” They'll pre-purchase a huge block of funds at a specific interest rate. This is called a “forward commitment.” They then reserve these lower rates exclusively for buyers who purchase their homes. It’s like they're buying bulk discounts on interest rates and passing some of that savings on to you.
  • In-House Lending Arms: Many of the big builders, like Lennar or D.R. Horton, also own their own mortgage companies. This is a huge advantage. It allows them to move money around internally. Instead of pocketing every bit of profit from the home sale, they can direct some of that profit to their mortgage company to subsidize your interest rate. It’s a way to make the financing part of the deal more attractive.
  • Buying Down the Rate (Paying “Points”): This is a really common method.
    • Permanent Buydowns: Builders will pay “discount points” to the lender. Think of points as upfront fees you'd normally pay to lower your interest rate. The builder is paying these fees for you, on your behalf, which permanently lowers your interest rate for the entire 30-year loan term.
    • Temporary Buydowns (Like 2-1 or 3-2-1): This is another popular option. The builder puts cash into a special account that helps lower your monthly payment for the first few years of your loan. For example, in a “2-1 buydown,” they'll subsidize your payment so your rate is 2% lower in the first year and 1% lower in the second year. While it’s temporary, it can significantly ease your financial burden during those crucial early years of homeownership, making that dream home feel much more affordable right from the start.
  • Protecting Neighborhood “Comps”: As I mentioned, builders are very careful about how they price their homes. They don't want to lower the advertised price of a home because it makes all the other homes in that community look less valuable. By offering a rate buydown, they're giving you a huge financial benefit without officially lowering the sticker price of the house. This helps maintain the perceived value of their entire development.

What Kind of Deals Can You Expect in 2026?

The offers are really varied, but here are some common incentives you'll see:

  • Mortgage Rate Buydowns: This is the star of the show.
    • Temporary Buydowns: You'll often see deals structured as 2-1 or even 3-2-1 buydowns. This means your initial payments are significantly lower.
    • Permanent Buydowns: Some builders are offering to pay for points to lock in a lower rate for the entire 30 years.
  • Target Rates: Many builders are advertising attractive interest rates, often in the high 4% to low 5% range. This is a far cry from current market rates for many buyers.
  • Closing Cost Credits: This is a big one! Builders might offer anywhere from $6,000 to $15,000 (or even more!) to cover your closing costs. This includes fees like loan origination, title insurance, and property taxes, which can add up quickly.
  • Price Reductions: While they try to avoid it, some builders are indeed cutting base prices. Roughly 36% to 40% of builders reported reducing prices by about 5% to 6% in early 2026.
  • Free Upgrades: On top of financial incentives, you might score free upgrades to your design center, get a new appliance package (think refrigerator, washer, and dryer included!), or find homes already finished with desirable fixtures.

Major Players and Their Offers

Here’s a peek at what some of the big builders might be offering:

Builder Notable 2026 Incentives
D.R. Horton Introductory rates as low as 0.99%; base rates around 3.99% in select markets.
Lennar “Ready Set Move” promotion with up to $55,000 in price cuts and $6,000 in closing credits.
PulteGroup Documented 2-1 buydown programs for Conventional and FHA loans.
David Weekley Homes Fixed rates as low as 4.99% for qualified FHA buyers in specific regions.
M/I Homes Fixed-rate incentives around 4.875% with 20% down on select inventory.

Note: These are examples and specific offers vary by location and available inventory.

Insider Tips for Buyers

As someone who’s navigated these waters before, I’ve learned a few things that can help you snag the best deal:

  • Use the Builder's Lender (Usually): This is key. The most aggressive rate buydowns are almost always tied to using the builder's affiliated mortgage company. While you can often use your own lender, you might miss out on the sweetest incentives. It’s definitely worth comparing, though!
  • Focus on Available Inventory: The best deals are typically on homes that are already completed and have been sitting for more than 30 days, or those in the final phases of a development (often called “closeout”). Builders are most eager to move these properties.
  • Compare Apples to Apples: Don't just look at the advertised incentive. Always compare the total price and the monthly payment with and without the incentive. Sometimes, a builder might subtly increase the home's price to offset the incentive. Make sure the deal is truly a win for you.

Price Cut vs. Rate Buydown: A Deeper Look

This is where it gets really interesting. Many buyers think a straight price cut is always better. However, often, a rate buydown provides a more substantial long-term financial benefit. Let's look at a quick example I found that illustrates this:

Imagine a $500,000 home with a $450,000 loan assuming a 7.0% interest rate.

  • Scenario 1: $20,000 Price Cut
    • New Home Price: $480,000
    • Interest Rate: 7.0%
    • Monthly Principal & Interest (P&I): $2,861
    • Monthly Savings: $133
  • Scenario 2: $20,000 Rate Buydown
    • Home Price: $500,000
    • Interest Rate (effectively lowered): 5.5%*
    • Monthly P&I: $2,555
    • Monthly Savings: $439

Note: A $20,000 contribution on a $450k loan typically buys a rate down by ~1.5% for the life of the loan.

What does this show? Even though the dollar amount of the incentive is the same ($20,000), the rate buydown saves you $306 more per month! Over 30 years, that’s a massive difference in how much interest you pay. The price cut saves you money on interest based on the reduced loan principal, but the rate buydown slashes the interest calculation on the entire loan amount.

However, there's a catch: the refinance risk. If rates drop significantly in a few years, the buyer who took the price cut can refinance their slightly lower principal at the new, lower rate. The buyer who took the buydown already used their incentive, and while they can still refinance, they don't have that built-in advantage of a lower starting principal. It’s a trade-off between immediate cash flow and potential future flexibility.

The Takeaway

In 2026, if you're looking for a new construction home, don't overlook the move-in ready options. Builders are genuinely motivated to get these properties sold, and their incentives, particularly those focused on lowering mortgage rates, are some of the most powerful tools they have. By understanding how these incentives work and what to look for, you can potentially lock in a fantastic deal and significantly reduce your monthly housing costs, making that new home dream a very achievable reality. It's a smart time to be a buyer if you're willing to explore these opportunities!

🏡 Two Rental Properties With Strong Cash Flow

Nashville, TN
🏠 Property: Winton Dr
🛏️ Beds/Baths: 3 Bed • 2.5 Bath • 1688 sqft
💰 Price: $360,000 | Rent: $2,100
📊 Cap Rate: 5.5% | NOI: $1,662
📅 Year Built: 2001
📐 Price/Sq Ft: $214
🏙️ Neighborhood: A

VS

Birmingham, AL
🏠 Property: Oak St
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1533 sqft
💰 Price: $172,000 | Rent: $1,425
📊 Cap Rate: 7.9% | NOI: $1,137
📅 Year Built: 1956
📐 Price/Sq Ft: $113
🏙️ Neighborhood: B+

Nashville’s A‑rated rental with stability vs Birmingham’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Drop Unlocking 5.5 Million More Households in 2026
  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: home loan, mortgage, mortgage rates

Mortgage Rates Today, March 14, 2026: 30-Year Refinance Rate Rises by 12 Basis Points

March 14, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

If you're thinking about refinancing your mortgage, listen up: Mortgage rates saw a noticeable bump today, March 14, 2026. Specifically, the popular 30-year fixed refinance rate climbed by 12 basis points to 6.62%. While this might sound like a small move, it’s part of a larger trend influenced by events far beyond our backyards.

Mortgage Rates Today, March 14, 2026: 30-Year Refinance Rate Jumps 12 Basis Points

What's Driving Today's Rate Hike?

So, why the increase? It’s a combination of things, but two big players are making waves: geopolitical tensions in the Middle East and a renewed worry about inflation. These aren't just headlines; they have a direct impact on the costs of borrowing money.

Think about it this way: when there's uncertainty in the world, especially concerning major resources like oil, investors get nervous. They tend to pull their money out of safer investments and look for things that might hold their value better. This often means they sell bonds, and when bond prices drop, their yields (which are closely tied to mortgage rates) go up.

Here’s a quick rundown of the rates as of Saturday, March 14, 2026, according to Zillow:

  • 30-Year Fixed Refinance Rate: Hit 6.62%. This is up from yesterday's 6.65% (a slight dip, but that's yesterday's news!), but a clear 12 basis points higher than last week's 6.50%.
  • 15-Year Fixed Refinance Rate: Saw a minor increase, landing at 5.78%, just a tad higher than yesterday's 5.76%.
  • 5-Year Adjustable-Rate Mortgage (ARM) Refinance Rate: Also ticked up to 7.10%, from 7.08%.

Is Anyone Still Refinancing? (Spoiler: Yes!)

Even with this jump, it's important to remember that the overall demand for refinancing is still pretty darn strong. People are still looking to take advantage of better rates than they might have had a year ago.

  • The Mortgage Bankers Association (MBA) is reporting an incredible 81% increase in refinance activity compared to this time last year. That’s a massive jump!
  • Looking at the very short term, refinance applications were pretty much steady, only growing by 0.5% as of March 11. This suggests people are pausing to see what happens next.
  • Despite the recent uptick in rates, refinancing still makes up a healthy 57.8% of all mortgage applications. That tells me a lot of people are still finding value in it.

The Big Picture: What's Shaking the Market?

Let's break down the bigger forces at play. As I mentioned, the Middle East conflict is a major concern. This isn't just about headlines; it's about real economic impact.

  • Oil Prices Soaring: The ongoing war in the Persian Gulf has pushed oil prices higher than $92 a barrel. When oil prices go up, pretty much everything else gets more expensive, fueling those inflation worries.
  • Bond Yields Reacting: The government's 10-year Treasury yield, a key benchmark for mortgage rates, is currently hovering around 4.24%. This number is sensitive to all sorts of global news.
  • The Fed's Next Move: The Federal Reserve is expected to keep interest rates on hold at their upcoming meeting next week. However, if inflation keeps making people uneasy, it might push back any plans for rate cuts later in 2026.
  • Lender Costs Going Up: It’s not just about the Fed. The market for mortgage-backed securities (MBS) is a bit choppy. When this market gets volatile, it means lenders have to build in a bit more room for error, which translates to higher rates for us consumers, even when Treasury yields are stable.

My Take: Should You Lock or Should You Wait?

This is the million-dollar question, isn't it? Based on what I'm seeing, here’s my personal take, informed by years of watching these trends:

  • Consider Locking: With all this volatility and the Fed meeting on the horizon, if you've found a rate you're happy with, locking it in might be a smart move to protect yourself against further increases. There's no crystal ball, but the signs point to potential continued upward pressure.
  • Shop Around Aggressively: I can't stress this enough: rates are NOT created equal. Different lenders will offer you different deals. I always tell people to talk to at least three different lenders. I’ve seen firsthand how this can save you a full percentage point, which is huge over the life of a loan.
  • Refinance Windows Still Exist: If you took out your mortgage when rates were higher, say above 7% in early 2025, you might still be in a fantastic position to refinance even with today's slight increase. Don't miss out on potential savings because you think rates have gone up too much.

The Bottom Line

Mortgage rates took a step higher on March 14, 2026, with the 30-year fixed refinance rate hitting 6.62% after rising 12 basis points. Global instability and inflation worries are definitely playing a role, keeping rates from dropping further. However, the desire to refinance remains strong compared to last year. For homeowners, especially those with older, higher-rate mortgages, opportunities are still out there. But in this choppy market, being smart about when you lock and who you get quotes from is absolutely key.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 13, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

  • « Previous Page
  • 1
  • …
  • 42
  • 43
  • 44
  • 45
  • 46
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...