Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Why Are Mortgage Rates Currently Experiencing Low Volatility?

June 14, 2025 by Marco Santarelli

Why Are Mortgage Rates Currently Experiencing Low Volatility?

Wondering why your dreams of homeownership might actually be within reach? You're not alone! Many are keeping a close eye on mortgage rates, and the big question is: Why are mortgage rates currently experiencing low volatility? As of June 2025, the U.S. mortgage market shows surprising stability, with rates barely budging. This relative calm is largely due to a blend of steady economic conditions, improvements in the housing market, and a calmer pace of home price increases.

Why Are Mortgage Rates Currently Experiencing Low Volatility?

Right now, it's a refreshing change from the roller-coaster we've seen in recent years! Let's dive into the factors contributing to this period of stability and what it means for you, whether you're a first-time buyer or looking to refinance.

Current Mortgage Rate Snapshot

Let's take a look at where mortgage rates stand as of June 12, 2025, according to the Primary Mortgage Market Survey. Seeing the numbers helps put things in perspective.

Mortgage Type Current Rate 1-Week Change 1-Year Change Monthly Average 52-Week Average 52-Week Range
30-Year Fixed Rate Mortgage 6.84% -0.01 -0.11 6.86% 6.69% 6.08% – 7.04%
15-Year Fixed Rate Mortgage 5.97% -0.02 -0.20 6.00% 5.88% 5.15% – 6.27%

As you can see, the changes are minimal. We're talking fractions of a percentage point! This lack of dramatic movement is what we mean by “low volatility.”

The Foundation: A Strong Labor Market

One of the biggest drivers of mortgage rates, and the overall economy, is the health of the labor market. After all, people need jobs to buy houses! Here's what the recent data tells us:

  • Unemployment Rate: The unemployment rate stood at 4.1% in May 2025. That's not just a number; it represents a steady environment where more people are working and earning money. It's also down 0.1% from the previous month and 0.6% compared to a year ago. This suggests a consistent and positive trend.
  • Job Growth: The economy added around 250,000 jobs in the last quarter. That's a significant boost, giving people greater confidence in their financial future.
  • Wage Growth: Wages have increased by about 3.2% year-over-year. This means people have more disposable income, which can translate into a greater ability to afford a home.

A strong labor market creates a domino effect. When people are employed and wages are rising, consumer confidence goes up, and they're more likely to make big purchases like homes. This also assures lenders that borrowers are more likely to repay their loans, reducing risk, and helping to keep rates steady.

More Borrowers Are Emerging: Mortgage Applications Are Rebounding

Numbers from the Mortgage Bankers Association (MBA) tell an interesting story. People are actively pursuing mortgages:

  • Overall Increase: Mortgage applications rose by 1.1% for the week ending May 9, 2025. This indicates growing interest in the housing market.
  • Purchase Power: The seasonally adjusted Purchase Index, which tracks applications for buying homes, jumped by 2%. Unadjusted, it was a whopping 18% higher than the same week last year. This is a significant indicator that more people are planning to buy homes.
  • Refinancing Considerations: Refinance applications dipped slightly by 0.4%, but they're still 44% higher than last year. Homeowners are clearly watching rates and looking for opportunities to save money.
  • Government-Backed Loans: Government purchase applications showed a surge, up almost 5% from the previous week and a dramatic 40% year-over-year. This suggests greater access to homeownership for those who might otherwise struggle to qualify.

More mortgage applications, especially for purchases, suggest a healthier housing market where buyers feel more secure about their financial futures.

Recommended Read:

Mortgage Rates This Week Remain Stable With 30-Year FRM at 6.84%

The Takeawa

Key Factors Behind the Low Volatility

So, summing up:

1. Stable Economic Conditions

Stable economic conditions are crucial in fostering a predictable mortgage rate environment. Key considerations:

  • Continuous job growth and steady employment rates enhance consumer confidence and stability, leading to a consistent interest in the housing market.
  • Managed inflation and consistent economic policies reduce the need for drastic monetary adjustments, contributing to stable mortgage rates.

2. Improving Housing Inventory

An uptick in housing availability is leveling the playing field for buyers.

  • The number of homes for sale has risen by about 15% year-over-year. More supply means less upward pressure on prices. This gives buyers more choices and time to make decisions.
  • An increase in housing inventory provides a broader range of options, potentially lowering the demand for each property and contributing to stable pricing. Increased market depth allows prospective buyers more time to review options and make informed decisions.

3. Slower Home Price Growth

The rate at which home prices are increasing has slowed down.

  • Home prices increased by only 3.4% annually, as per the latest reports. This is a more manageable pace compared to the rapid growth we saw in previous years. This makes homeownership more accessible and reduces the urgency for buyers to rush into decisions.

4. External Market Factors

External factors such as geopolitical stability can significantly influence buyer and lender sentiments.

  • No significant economic crises or global events occurred that impacted market stability
  • Stable international relations limit investor uncertainty and support secure lending practices.

Why it matters: Implications For Potential Borrowers and Homebuyers

For those navigating the market, here is what you need to know:

  • Greater Affordability: Consistent rates give buyers confidence. You can budget and plan without worrying about a sudden jump in your monthly payments.
  • More Encouraging Purchase Activity: The current trend indicates an opportune climate to consider first-time purchases or upgrades.
  • Government Support: Increased accessibility to government-backed loans is opening doors, providing more financial support to those who need it.

My Final Thoughts

Overall, the combination of a strong labor market, increasing housing inventory, a slowdown in home price growth, and wider economic stability is creating a more predictable and buyer-friendly environment.

I think we're headed for a sustained period of relative stability in the mortgage market. The economic signals are generally positive, and the housing market is gradually finding a better balance. But, as always, it's important to stay informed, do your research, and consult with a mortgage professional to find the best options for your individual circumstances.

Invest in Real Estate in the Top U.S. Markets

Investing in turnkey real estate can help you secure consistent returns with fluctuating mortgage rates.

Expand your portfolio confidently, even in a shifting interest rate environment.

Speak with our expert investment counselors (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates

Today’s Mortgage Rates – June 14, 2025: Rates Drop Slightly Across the Board

June 14, 2025 by Marco Santarelli

Today’s Mortgage Rates - June 14, 2025: Rates Drop Slightly Across the Board

As of June 14, 2025, mortgage rates have seen a slight upward movement. According to Zillow, the average 30-year fixed mortgage rate is currently at 6.94%, which is an increase of 2 basis points from the previous day's rate of 6.92%. Remarkably, this rate is down 5 basis points from the previous week's average of 6.99%. The average 30-year fixed refinance rate stands at 7.18%, reflecting a modest 6 basis point increase from last week. These fluctuations are essential for anyone considering home purchasing or refinancing.

Today’s Mortgage Rates – June 14, 2025: Rates Drop Slightly

Key Takeaways

  • Current 30-Year Fixed Rate: 6.94%
  • Current 30-Year Fixed Refinance Rate: 7.18%
  • Comparison: Rates have slightly increased this week.
  • 15-Year Fixed Mortgages: 6.02%, up by 2 basis points.
  • Market Outlook: Predictions suggest rates may stabilize in the mid-to-upper 6% range.

Mortgage rates are pivotal in determining your monthly payments when purchasing a home or refinancing an existing mortgage. On June 14, 2025, the 30-year fixed mortgage rate specifically drew attention because it marks a crucial point for potential homeowners. While there is a noticeable increase from the previous day, it's important to contextualize these figures against the backdrop of fluctuating economic conditions and governmental policies.

Current Mortgage Rates Overview

The following table summarizes the recent mortgage rates across different loan types:

Loan Type Rate 1W Change APR 1W Change
30-Year Fixed Rate 6.94% down 0.04% 7.39% down 0.05%
20-Year Fixed Rate 6.53% down 0.30% 6.96% down 0.28%
15-Year Fixed Rate 6.02% down 0.05% 6.31% down 0.06%
10-Year Fixed Rate 6.03% up 0.10% 6.13% down 0.04%
7-Year ARM 7.58% down 0.24% 8.08% down 0.15%
5-Year ARM 7.29% down 0.33% 7.67% down 0.33%

Source: Zillow

Government Loan Rates

Additionally, when discussing government loans such as FHA and VA loans, here's an insightful summary based on recent data:

Loan Type Rate 1W Change APR 1W Change
30-Year Fixed Rate FHA 7.00% up 0.08% 8.02% up 0.08%
30-Year Fixed Rate VA 6.40% down 0.05% 6.56% down 0.10%
15-Year Fixed Rate FHA 5.75% up 0.06% 6.72% up 0.04%
15-Year Fixed Rate VA 5.97% down 0.01% 6.32% 0.00%

Current Refinance Rates

For homeowners looking to refinance, the situation is as follows:

Loan Type Rate 1W Change APR 1W Change
30-Year Fixed Refinance Rate 7.18% up 0.06% 7.39% down 0.05%
20-Year Fixed Refinance Rate 6.53% down 0.30% 6.96% down 0.28%
15-Year Fixed Refinance Rate 6.12% up 0.12% 6.31% down 0.06%
10-Year Fixed Refinance Rate 6.03% up 0.10% 6.13% down 0.04%
5-Year ARM Refinance Rate 5.97% 0.00% 6.45% 0.00%

What Influences Mortgage Rates?

The fluctuations in mortgage rates aren't random; various factors play a critical role:

  • Federal Reserve Policy: The actions of the Federal Reserve often have a ripple effect on mortgage rates. When the Fed adjusts its benchmark rate, it can influence mortgage rates but not always in a direct manner. For instance, if the Fed raises rates to combat inflation, mortgage rates typically follow suit, although the correlation may vary.
  • Inflation: Typically, higher inflation correlates with increased mortgage rates. When inflation is high, lenders demand higher rates to compensate for the diminishing purchasing power of future payments. This correlation means that if inflation persists or accelerates, we may see mortgage rates push upwards.
  • Economic Growth: A thriving economy often leads to higher mortgage rates as demand surges. When people feel financially secure, they're more likely to buy homes, increasing demand for loans. Conversely, a sluggish economy can push rates downward due to decreased demand for home loans.
  • Investor Sentiment: The health of the mortgage-backed securities market can also shape mortgage rates. If investors feel optimistic about the economy's direction, they buy mortgage-backed securities, driving rates down. On the flip side, if uncertainty looms, rates might increase as investors pull back.
  • Supply and Demand: Ultimately, the basic economic principle of supply and demand applies to mortgage rates. If more people want to buy homes (high demand), lenders can increase rates. If fewer people are looking to buy (lower demand), lenders may offer lower rates to stimulate the market.

Future Predictions on Mortgage Rates

Looking forward, experts have divided opinions about the trajectory of mortgage rates. While current trends show a slight uptick, several forecasts suggest that rates may stabilize in the near future.

  • According to Freddie Mac, rates are expected to hover around 6.08% to 7.04% throughout 2025, implying a very modest downward trend towards the year-end. This range suggests a stabilization, meaning buyers could experience fewer shocks in their mortgage costs as the year progresses.
  • Notably, J.P. Morgan forecasts a slight easing, with rates projected to settle around 6.7% by the year’s end, while the National Association of Realtors suggests an average of 6.4% for the year. These projections offer a glimmer of hope for potential homeowners who are wary of rising rates.
  • The insights from the Mortgage Reports indicate that the anticipated trajectory for June 2025 shows mortgage rates stabilizing, with analysts believing the 30-year rate may hover around 6.8% to 6.9%. This represents a potential for borrowers to find consistent terms, albeit at a level that's still considered high relative to years prior.

Considering these forecasts, it becomes clear that while rates may fluctuate slightly, there is an overarching trend towards stabilization. However, borrowers should remain vigilant and consult with mortgage professionals to understand the most current conditions affecting their specific situations.

Read More:

Mortgage Rates Trends as of June 13, 2025

Will Mortgage Rates Go Down in June 2025: Expert Forecast

Mortgage Rate Forecast 2025: When Will Rates Go Below 6%?

Refinancing Scenarios for Homeowners in 2025

With the current landscape of mortgage rates, homeowners might wonder if it's the right time to refinance. Like purchasing a home, refinancing comes with its own set of calculations. It's always wise to weigh the costs of refinancing against potential savings.

Suppose you currently have a 30-year fixed mortgage at a rate of 7.5% and you're considering refinancing to the current rate of 7.18%. Here's how you can evaluate whether refinancing is beneficial:

  1. Calculate Your Savings: Use the interest savings to inform your decision. For instance, on a loan amount of $300,000, the difference in monthly payment can be calculated.
    • Current Monthly Payment:
      • Using a 7.5% rate results in approximately $2,096.55 monthly.
    • New Monthly Payment:
      • At 7.18%, this decreases to around $2,056.24 monthly.
    • Monthly Savings:
      • $2,096.55 – $2,056.24 = $40.31 saved each month.
  2. Evaluate Closing Costs: Keep in mind that refinancing typically incurs closing costs ranging from 2% to 5% of the loan amount. In this case, if your closing costs are about $6,000, it would take approximately 149 months (a little over 12 years) to break even on those costs by saving $40.31 a month.
  3. Adjust for Future Market Changes: If forecasts suggest rates will dip further, you might also factor that into whether you should wait to refinance. Ultimately, this will depend on your personal financial circumstances and future plans regarding homeownership.
  4. Consult with a Financial Advisor: Given the intricacies involved, it's essential to rise above the numbers and seek professional insight, as they can offer personalized advice compensating for fluctuating market conditions.

Summary:

As an observer of the mortgage market, it is evident that understanding how today's mortgage rates impact your financial decisions is crucial. The data reveals a nuanced picture: while certain rates have increased this week, the overall trend suggests a steady landscape where informed decisions can lead to optimal financial outcomes.

It's imperative to remain vigilant about the changing rates and consult reliable sources as you consider your next steps in homeownership or refinancing.

Invest Smarter in a High-Rate Environment

With mortgage rates remaining elevated this year, it's more important than ever to focus on cash-flowing investment properties in strong rental markets.

Norada helps investors like you identify turnkey real estate deals that deliver predictable returns—even when borrowing costs are high.

HOT NEW LISTINGS JUST ADDED!

Connect with a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now 

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

Mortgage Rates This Week Remain Stable With 30-Year FRM at 6.84%

June 13, 2025 by Marco Santarelli

Mortgage Rates This Week Remain Stable With 30-Year FRM at 6.84%

Are you thinking about buying a home or refinancing your current mortgage? Then you're probably glued to your screen, constantly checking the mortgage rates this week ending to see where things stand. Well, here's the bottom line: For the week ending June 12, 2025, mortgage rates remained essentially flat, with only slight fluctuations. Let's dive into the details and what this means for you.

Mortgage Rates This Week Ending: U.S. Weekly Averages

Well, I can tell you that stability can be just as important as a big drop. We are in National Homeownership Month, and this stability with an improving inventory is good news. According to the Primary Mortgage Market Survey from Freddie Mac, here's a look at the U.S. weekly averages as of June 12, 2025:

  • 30-Year Fixed-Rate Mortgage (FRM): 6.84%
  • 15-Year Fixed-Rate Mortgage (FRM): 5.97%

Let's break that down further.

Understanding the 30-Year Fixed-Rate Mortgage

The 30-year FRM is the workhorse of the mortgage world. It's the most popular choice for homebuyers, thanks to its predictable monthly payments amortized over three decades. Here's a closer look at where it stands this week:

  • Current Rate: 6.84%
  • One-Week Change: Down 0.01 percentage points
  • One-Year Change: Down 0.11 percentage points
  • Monthly Average: 6.86%
  • 52-Week Average: 6.69%
  • 52-Week Range: 6.08% – 7.04%

Even though there was a tiny dip of just 0.01%, the bigger picture shows that rates are hovering within a tight range. In fact, this almost negligible change indicates a steady hold. The fluctuations are minimal when we compare it with the 52-week range showing us the consistency of the mortgage rates.

The 15-Year Fixed-Rate Mortgage: A Faster Path to Ownership

The 15-year FRM is a less common choice. This is because there is a high premium to pay monthly, however, it can be a smart move if you can afford the higher monthly payments. You build equity faster and save significantly on interest over the life of the loan. Here's what you need to know:

  • Current Rate: 5.97%
  • One-Week Change: Down 0.02 percentage points
  • One-Year Change: Down 0.2 percentage points
  • Monthly Average: 6%
  • 52-Week Average: 5.88%
  • 52-Week Range: 5.15% – 6.27%

Again, just as with the 30-year, we see rates remaining steady. And in my opinion, if you're financially secure and want to pay off your mortgage faster, the 15-year FRM is definitely worth considering.

So, What Does “Essentially Flat” Really Mean?

When economists say mortgage rates are “essentially flat,” it means they haven't moved significantly enough to cause a major shift in the housing market. In real terms, this stability is a relief. It gives buyers and lenders some breathing room to assess things without the added pressure of constantly rising rates.

National Homeownership Month: An Encouraging Sign

As we noted earlier, we're currently in National Homeownership Month. Alongside stable rates and a consistent mortgage marketplace, this offers an encouraging outlook given the combination of the following factors:

  • Rate stability
  • Improving inventory
  • Slower house price growth

Why are Mortgage Rates Important?

This might seem obvious, but it's worth reiterating: mortgage rates have a huge impact on affordability. Even a slight increase can significantly increase your monthly payments and the total amount you pay over the life of the loan. Here's how rates affect you:

  • Monthly Payments: Higher rates mean higher monthly payments.
  • Purchasing Power: When rates go up, your purchasing power goes down, meaning you might qualify for a smaller loan or need to adjust your budget.
  • Refinancing: Rates influence whether it makes sense to refinance your existing mortgage.

My Two Cents: What to Consider in Today's Market

As someone who's watched the market for years, here's my advice:

  1. Don't Wait for the “Perfect” Rate: Trying to time the market is a fool's errand. Rates fluctuate, and waiting for the absolute bottom can mean missing out on a great home.
  2. Focus on Affordability: Before you fall in love with a house, figure out what you can comfortably afford each month.
  3. Shop Around: Don't settle for the first rate you're offered. Get quotes from multiple lenders to ensure you're getting the best deal.
  4. Consider Your Long-Term Goals: Think about how long you plan to stay in the home and whether a 15-year or 30-year mortgage makes more sense for your financial situation.
  5. Work with a Professional: A good mortgage broker or financial advisor can guide you through the process and help you make informed decisions.

Looking Ahead:

While it's impossible to predict the future, most experts believe that mortgage rates will probably continue to fluctuate within a relatively narrow range in the coming months. Economic data, inflation reports, and Federal Reserve policies will all play a role in determining where rates ultimately land.

The Takeaway:

Mortgage rates this week ending remained pretty much where they were. It's crucial to stay informed, consult with professionals, and make decisions that align with your financial goals.

Invest in Real Estate in the Top U.S. Markets

Investing in turnkey real estate can help you secure consistent returns with fluctuating mortgage rates.

Expand your portfolio confidently, even in a shifting interest rate environment.

Speak with our expert investment counselors (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates This Week

U.S. States With Lowest Mortgage Rates Today – June 13, 2025

June 13, 2025 by Marco Santarelli

States With Lowest Mortgage Rates Today – June 13, 2025

Looking to snag the best mortgage rate possible? As of today, June 13, 2025, the states with the cheapest 30-year new purchase mortgage rates are New York, Colorado, California, Connecticut, Washington, D.C., Massachusetts, and Washington, where average rates range from 6.73% to 6.80%. But remember, this is just a snapshot, and securing the best rate for you requires a bit more digging.

States With Lowest Mortgage Rates Today – June 13, 2025

The world of mortgages can seem like a maze of numbers, terms, and fine print. As someone who's spent years navigating this field, I understand how overwhelming it can be. That's why I'm here to break down today's mortgage rate situation, state by state, and give you the insights you need to make smart decisions. This analysis is based on the latest data from Investopedia, offering a clear understanding of the current mortgage rates.

Why Do Mortgage Rates Vary By State?

You might be wondering, “Why doesn't everyone just get the same rate?” It's a fair question! Several factors contribute to the variation we see across different states:

  • Lender Presence and Competition: Not all lenders operate in every state. Where there's less competition, rates may be higher.
  • State-Level Regulations: State laws governing mortgages can differ, impacting lender costs and, consequently, rates.
  • Credit Score Averages: States with higher average credit scores might see slightly better rates overall, as lenders perceive less risk.
  • Average Loan Sizes: If the average loan size in a state is larger, lenders might adjust rates accordingly to manage their portfolios.
  • Risk Management Strategies: Each lender has its own approach to risk. Some might be more aggressive in offering lower rates to attract business, while others might prioritize profitability.

The Highs and Lows: A State-by-State Breakdown

Let's dive into the specifics. Earlier, I mentioned the states with the lowest rates. Here's a quick recap and comparison of the highest too.

States with the Lowest 30-Year Fixed Mortgage Rates (New Purchase) – June 13, 2025

  • New York: 6.73%
  • Colorado: 6.75%
  • California: 6.76%
  • Connecticut: 6.77%
  • Washington, D.C.: 6.78%
  • Massachusetts: 6.79%
  • Washington: 6.80%

States with the Highestr 30-Year Fixed Mortgage Rates (New Purchase) – June 13, 2025

  • West Virginia: 6.95%
  • Alaska: 6.97%
  • North Dakota: 6.98%
  • Mississippi: 6.99%
  • Wyoming: 7.00%
  • Rhode Island: 7.01%

It's crucial to remember that these are just averages. Your individual rate will depend on your unique financial situation.

National Mortgage Rate Trends: Where Are We Heading?

It's not just about individual states; the national picture matters too. Here's a look at where national average mortgage rates stand right now, according to Zillow:

  • 30-Year Fixed (New Purchase): 6.87%
  • FHA 30-Year Fixed: 6.95%
  • 15-Year Fixed: 5.91%
  • Jumbo 30-Year Fixed: 6.84%
  • 5/6 ARM: 7.13%

Rates on 30-year new purchase mortgages have been incrementally dropping for the past week, recovering from a surge, and are down from a high of 7.15% in May. While rates dipped to 6.50% in March, their lowest average of 2025, and 5.89% in September of the past year, we need to keep a close watch on the market.

Understanding the Fine Print: “Teaser Rates” vs. Actual Rates

You've probably seen those super-low mortgage rates advertised online. They can be tempting, but it's important to understand what you're really getting. These “teaser rates” often come with strings attached:

  • Points: You might have to pay points (an upfront fee) to get that low rate.
  • Ultra-High Credit Scores: The rate might only be available to borrowers with near-perfect credit.
  • Small Loan Amounts: Some lenders offer lower rates on smaller loans.

The rate you actually secure will be based on your credit score, income, down payment, and other factors. Don't be afraid to ask lenders for a Loan Estimate to see the full picture.

Read More:

States With the Lowest Mortgage Rates on June 11, 2025

Are Mortgage Rates Expected to Go Down Soon: A Realistic Outlook

What Drives Mortgage Rate Fluctuations?

Understanding the factors that influence mortgage rates is like understanding the financial weather forecast. Several key elements are at play.

  • The Bond Market: Look into the 10-year treasury yields in the bond market and watch for changes there.
  • The Federal Reserve (The Fed): The Fed is still purchasing bonds to a degree but at a tapered volume. The Fed has been incrementally cutting rates – starting with a cut of 0.50 percentage points and following with two more cuts of 0.25 points each. Keep in mind that the Fed has eight scheduled rate-setting meetings per year that could result in a hold announcement.
  • Competition: This is true across all types of loan offerings, more competition will drive costs down.
  • Inflation: Higher inflation will cause mortgage rates to increase.

What Can You Do to Get the Best Rate?

Okay, so you know where rates are and why they change. Now, let's talk about what you can do to land the best possible rate.

  • Shop Around. Shop Around. Shop Around! I can't stress this enough. Get quotes from multiple lenders – banks, credit unions, online lenders – and compare them carefully.
  • Boost Your Credit Score: Even a small improvement in your credit score can make a big difference in your interest rate. Pay bills on time, reduce your credit card balances, and correct any errors on your credit report.
  • Save for a Larger Down Payment: A bigger down payment means less risk for the lender, which can translate to a lower rate.
  • Consider a Shorter Loan Term: 15-year mortgages typically have lower interest rates than 30-year mortgages, although your monthly payments will be higher.
  • Be Prepared to Negotiate: Don't be afraid to ask lenders if they can match or beat a competitor's offer. You might be surprised at their willingness to work with you.

The Bottom Line:

The mortgage market is constantly evolving. What's true today might not be true tomorrow. Stay informed, do your research, and work with trusted professionals who can guide you through the process. Buying a home is one of the biggest financial decisions you'll ever make. Take your time, and make sure you're making the right choice for you.

Invest in Real Estate in the Top U.S. Markets

Investing in turnkey real estate can help you secure consistent returns with fluctuating mortgage rates.

Expand your portfolio confidently, even in a shifting interest rate environment.

Speak with our expert investment counselors (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

Today’s Mortgage Rates – June 13, 2025: A Big Drop in Rates From Last Week

June 13, 2025 by Marco Santarelli

Today’s Mortgage Rates - June 13, 2025: A Big Drop in Rates From Last Week

As of June 13, 2025, mortgage rates have shown fluctuations, with the average 30-year fixed mortgage rate currently remaining at 6.88%, which marks a substantial decrease of 11 basis points from last week's average of 6.99%. The national average for the 15-year fixed mortgage has risen slightly to 5.96%, while the 5-year adjustable-rate mortgage (ARM) rate has decreased to 7.17%. Here are more details about the current mortgage rate trends across various loan types.

Today’s Mortgage Rates – June 13, 2025: A Big Drop in Rates From Last Week

Key Takeaways

  • 30-Year Fixed Mortgage Rate: 6.88%, down from 6.99%
  • 15-Year Fixed Mortgage Rate: 5.96%, up from 5.94%
  • 5-Year ARM Rate: 7.17%, down from 7.21%
  • Current Refinance Rates: 30-Year fixed refinance at 7.08%, down from 7.09%
  • Market Outlook: Rates expected to remain stable or slightly decrease through 2025

Current Mortgage Rates

Mortgage Rates fluctuate regularly based on various economic indicators, market conditions, and lender strategies. The following table outlines the average rates for various types of home loans as of June 13, 2025:

Loan Type Rate (%) 1W Change (%) APR (%) 1W Change (%)
30-Year Fixed Rate 6.88 -0.11 7.32 -0.13
20-Year Fixed Rate 6.55 -0.27 6.79 -0.45
15-Year Fixed Rate 5.96 +0.02 6.25 -0.11
10-Year Fixed Rate 6.03 +0.10 6.13 -0.04
7-Year ARM 6.64 -1.17 7.51 -0.72
5-Year ARM 7.17 -0.45 7.84 -0.16

Source: Zillow

A fixed-rate means your interest rate remains constant throughout the loan's duration, making it simpler to plan payments. On the other hand, ARMs might start lower, but they can increase after an introductory period, leading to unexpected fluctuations in monthly payments.

What Are Current Refinance Rates?

For those looking to refinance, the rates have also seen some changes. The current refinance rates are as follows:

Refinance Loan Type Rate (%) 1W Change (%) APR (%) 1W Change (%)
30-Year Fixed Refinance 7.08 -0.01 7.32 -0.13
15-Year Fixed Refinance 5.99 +0.07 6.25 -0.11
5-Year ARM Refinance 7.69 0.00 – –

Source: Zillow

The 30-year fixed refinance rate has decreased by 1 basis point, now resting at 7.08%, down from last week's 7.09%. This decline can be beneficial for homeowners wishing to reduce their current mortgage payments, tap into equity for home improvements, or consolidate debt.

Understanding Mortgage Refinancing Costs

When refinancing, it’s essential to consider not only the rate change but also the costs involved. Refinancing entails several expenses which may offset any potential savings from a lower rate:

  • Origination Fees: This is a fee charged by the lender for evaluating and preparing your mortgage. It can range from 0.5% to 1% of the total loan amount.
  • Appraisal Fees: Typically costing between $300 to $700, these fees assess the property's value to ensure it meets the loan amount criteria.
  • Closing Costs: Generally ranging from 2% to 5% of the loan amount, closing costs include various fees, such as title insurance and attorney fees.
  • Prepayment Penalties: If your original mortgage has a prepayment penalty for paying off the loan early, this could significantly impact your refinancing decision.

For example, if you're refinancing a $300,000 loan, the closing costs could range from $6,000 to $15,000, which you need to weigh against the savings of a lower interest rate. An astute borrower would aim to evaluate the break-even point, which is the time it takes for the savings from lower monthly payments to surpass the costs associated with refinancing.

How to Find the Best Mortgage Rates in 2025?

Finding the ideal mortgage rate requires diligence. Here are several strategies to ensure you secure the best possible rate in 2025:

  1. Research Multiple Lenders: Different lenders offer various rates and terms, so it’s necessary to shop around. Websites like Bankrate and Zillow provide comprehensive comparisons of rates from various lenders.
  2. Check Your Credit Score: Your credit score plays an essential role in determining your mortgage rate. A higher credit score typically translates to lower rates. Before applying, check your credit report and work to enhance your score as needed.
  3. Stay Informed on Market Trends: Pay attention to economic news and market trends, as these factors can influence mortgage rates. Understanding cycles in inflation, employment rates, and economic growth can gauge when to lock in a favorable rate.
  4. Consider Loan Types: Review different loan types such as FHA, VA, conventional, and ARMs. Each loan type has its requirements, benefits, and potential risks.
  5. Consult a Mortgage Broker: Mortgage brokers have access to a wide array of lenders and can often negotiate better rates on your behalf. They can filter through numerous options to find a mortgage that aligns with your financial situation.

Read More:

Mortgage Rates Trends as of June 12, 2025

Will Mortgage Rates Go Down in June 2025: Expert Forecast

Mortgage Rate Forecast 2025: When Will Rates Go Below 6%?

Mortgage Rates Outlook for the Rest of 2025

Looking ahead, mortgage rates are expected to remain steady with varying forecasts predicting slight fluctuations. According to the National Association of REALTORS®:

  • Forecast for 2025:
    • Existing Home Sales: Expected to see an increase of 6%
    • New Home Sales: Anticipated to rise by 10%
    • Median Home Prices: Projected to increase by 3%
    • Expected Mortgage Rate: Anticipated to settle at around 6.4%

Fannie Mae’s forecast also supports a softening of rates, predicting an end-of-year rate of 6.1%, down from 6.2% previously. Meanwhile, the Mortgage Bankers Association projects 30-year rates to stabilize near 6.7% through the summer months.

Freddie Mac, on the other hand, notes that while buyers may hope for a decrease in rates, it is more probable that they will remain elevated throughout 2025. High rates might deter some potential buyers, yet they might prompt others to act earlier due to the ongoing uncertainty in the market.

This current high-rate environment could encourage homeowners wishing to sell to enter the housing market sooner rather than later, leading to increased activity in home sales despite the overall level of sales still remaining below historical averages. According to Freddie Mac, the “rate lock-in” phenomenon—where homeowners feel stuck with their low-rate mortgages—may gradually decrease, allowing more inventory to hit the market.

Prices are also anticipated to appreciate, although at a more moderate pace compared to recent years. The home price growth, coupled with a projected increase in home sales, is likely to drive purchase volumes higher than in 2024. Slightly lower rates in 2025 should translate to increased refinancing activity as well, which is good news for lenders and potential borrowers alike.

In summary, today's mortgage rates reflect a complex web of economic factors and market strategies. Understanding these dynamics is crucial for anyone considering buying or refinancing a home in June 2025, as small changes in rates can have significant long-term financial impacts.

Invest Smarter in a High-Rate Environment

With mortgage rates remaining elevated this year, it's more important than ever to focus on cash-flowing investment properties in strong rental markets.

Norada helps investors like you identify turnkey real estate deals that deliver predictable returns—even when borrowing costs are high.

HOT NEW LISTINGS JUST ADDED!

Connect with a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now 

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

Mortgage Interest Rates Graph Over the Past One Year

June 12, 2025 by Marco Santarelli

Mortgage Interest Rates Graph Over the Past One Year

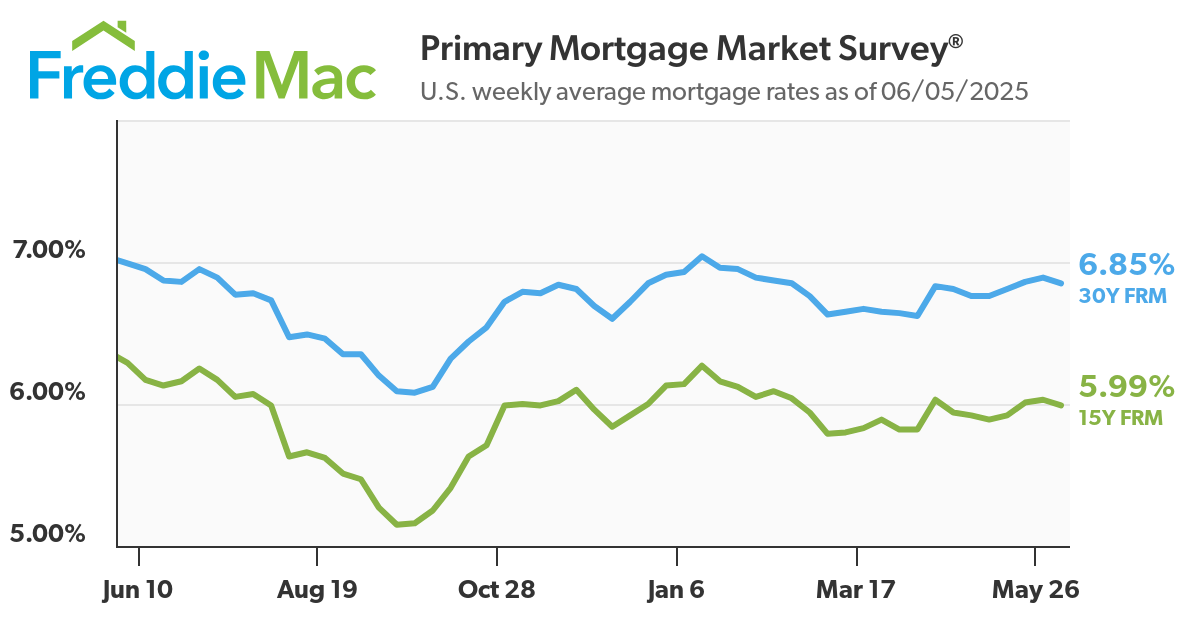
Have you ever wondered how much the cost of borrowing money to buy a house has changed over the last year? It's a big question, and if you're thinking about buying a home – or even just keeping an eye on the economy – understanding the trends in mortgage interest rates is super important. Over the past year, as shown in the mortgage interest rates graph over the past year, we've seen some interesting movements that can really impact what you pay each month for your mortgage.

Let's dive into what the data tells us and what it might mean for you.

Mortgage Interest Rates Graph Over the Past One Year

What the Latest Data Shows

As of June 5, 2025, the average interest rate for a 30-year fixed-rate mortgage (also known as a 30-Yr FRM) stood at 6.85%. Looking back, according to Freddie Mac's data, this is a slight decrease from the previous week (-0.04%) and also a bit lower than where we were a year ago (-0.14%).

mortgage interest rates graph
Source: Freddie Mac

For those considering a shorter loan term, the 15-year fixed-rate mortgage (15-Yr FRM) averaged 5.99%. This also saw a decrease of 0.04% from the week before and a more significant drop of 0.3% compared to this time last year.

Here's a quick summary:

Loan Type Current Rate (06/05/2025) Weekly Change Yearly Change
30-Yr FRM 6.85% -0.04% -0.14%
15-Yr FRM 5.99% -0.04% -0.30%

It's encouraging to see that rates have come down a little recently. For anyone looking to buy a home, this can make a real difference in their monthly payments and overall affordability. The fact that inventory is reportedly improving and house price growth is slowing down adds to this positive news for potential homebuyers.

A Deeper Dive into the Past Year's Trends

Looking at the mortgage interest rates graph since past one year (from June 5, 2024, to June 5, 2025), we can see the journey these rates have taken. The blue line represents the 30-year fixed rate, and the green line shows the 15-year fixed rate.

  • Fluctuations are Normal: What stands out immediately is that mortgage rates don't stay still. They go up and down based on a whole bunch of economic factors. You can see periods where both the 30-year and 15-year rates were climbing, and other times where they were on a downward trend.
  • Peak and Valley: The 30-year fixed rate touched a high of 7.04% within the past 52 weeks and a low of 6.08%. For the 15-year fixed rate, the range was between 6.27% and 5.15%. These are significant swings that could change your mortgage payment by a noticeable amount.
  • Impact of Economic Events: While the graph itself doesn't tell us why the rates moved the way they did, I know from my experience in following the market that things like inflation reports, decisions by the Federal Reserve (the Fed) about interest rates, and the overall health of the economy play a big role. When the economy is strong, and inflation is a concern, mortgage rates tend to rise. When the economy slows down, or there are worries about a recession, rates often fall.

Thinking About the Bigger Picture

It's easy to get caught up in the week-to-week changes, but it's important to think about the broader context. Over the past year, the housing market has been navigating a period of adjustment. After the very low interest rates we saw a few years ago, rates climbed quite sharply. This naturally had an impact on home affordability and the number of people looking to buy.

Now that rates seem to be stabilizing and even coming down a bit, it could signal a more balanced market. Sellers might need to be more realistic with their prices, and buyers might find more opportunities.

My Thoughts

Having followed the housing market for a while, I can tell you that trying to perfectly time when to buy based solely on interest rates is incredibly difficult – almost like trying to catch a falling knife! There are so many factors at play.

However, understanding the trends, like the ones we see in Freddie Mac's mortgage interest rates chart, can help you make more informed decisions. For example:

  • If rates are trending downward and you're in a stable financial position, it might be a good time to consider locking in a rate. Even a small decrease in the interest rate can save you thousands of dollars over the life of a 30-year loan.
  • If rates are high, it might be worth exploring adjustable-rate mortgages (ARMs) or focusing on improving your credit score to qualify for a better rate. Of course, ARMs come with their own set of risks, so it's crucial to understand how they work.

It's also worth remembering that your personal financial situation – your income, debts, and credit score – will significantly influence the mortgage rate you actually qualify for.

Read More:

Dave Ramsey Predicts Mortgage Rates Will Probably Drop Soon in 2025

Mortgage Rates Rise Back to 7% Once Again in June 2025

Mortgage Rate Forecast 2025: When Will Rates Go Below 6%?

Looking Ahead

Predicting where mortgage rates will go next is always a challenge. Economic forecasts can change, and unexpected events can happen. However, by keeping an eye on the mortgage interest rates graph since past one year and staying informed about economic news, you can get a sense of the general direction things might be heading.

The recent decrease in rates, combined with potentially improving inventory, could create a more favorable environment for homebuyers in the coming months. Of course, this is just my take based on the current data and my understanding of the market. It's always a good idea to talk to a financial advisor or a mortgage professional for personalized advice.

Summary:

The mortgage interest rates graph over the past year provides a valuable snapshot of how the cost of borrowing for a home has fluctuated. While we've seen some decreases recently, it's a reminder that rates are dynamic and influenced by a variety of economic factors. For anyone involved in the housing market, whether as a buyer, seller, or homeowner, staying informed about these trends is key to making sound financial decisions.

Invest Smarter in a High-Rate Environment

With mortgage rates remaining elevated this year, it's more important than ever to focus on cash-flowing investment properties in strong rental markets.

Norada helps investors like you identify turnkey real estate deals that deliver predictable returns—even when borrowing costs are high.

HOT NEW LISTINGS JUST ADDED!

Connect with a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now 

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Interest Rates Graph, Mortgage Rate Trends, mortgage rates

States With Lowest Mortgage Rates Today – June 12, 2025

June 12, 2025 by Marco Santarelli

States With Lowest Mortgage Rates Today – June 12, 2025

Looking for the best mortgage rates? As of today, June 12, 2025, the states boasting the lowest 30-year new purchase mortgage rates are New York, Massachusetts, Colorado, California, New Jersey, Washington, Texas, Florida, and Virginia. These states currently register average rates between 6.79% and 6.89%. Figuring out where to buy a home is tough enough; finding the lowest mortgage rate shouldn't be!

States With Lowest Mortgage Rates Today – June 12, 2025

I know what you're thinking: “Why do rates even change from state to state?” Well, let's dive in and see what impacts the mortgage rates and which states have the best deals right now.

Why Mortgage Rates Differ by State

Mortgage rates aren't uniform across the United States. Several factors play a role in these geographic variations. Here are a couple of main reasons that could affect the rate:

  • Lender Presence: Not all lenders operate in every state. The competitive landscape can change based on which lenders are actively trying to gain market share in a specific region. More competition often leads to lower rates.
  • State-Level Regulations: Mortgage regulations can vary significantly from state to state. These regulations can affect the cost of doing business for lenders and, consequently, the rates they offer.
  • Credit Score Averages: States with higher average credit scores might see slightly better rates, as lenders perceive borrowers as less risky.*
  • Average Loan Size: The average size of mortgages can impact rates since bigger the amount more the risk involved. If a state has a trend for taking bigger loans, there could be a rise in rate of interest.
  • Risk Management Strategies: Different lenders have varying approaches to risk. Some might be more aggressive in offering lower rates to attract borrowers, while others might be more conservative.

These variations can significantly impact what you will ultimately pay for your mortgage. It always pays to be informed!

The Best Bang for Your Buck: States With the Lowest Mortgage Rates

Alright, let's get down to brass tacks. According to Investopedia, as of today, here's the breakdown of the states offering the most attractive 30-year new purchase mortgage rates:

  • New York: The Empire State is starting to look enticing.
  • Massachusetts: Chowda' and low rates? Sounds like a good deal.
  • Colorado: The Rocky Mountain High is in Mortgage rate here
  • California: Surprisingly, the Golden State makes the cut.
  • New Jersey: The Garden State is home to big savings on mortgages.
  • Washington: Escape to the great Northwest.. and save some money doing so.
  • Texas: Everything's bigger in Texas. Including savings, apparently.
  • Florida: The Sunshine State continues to get brighter.
  • Virginia: The Old Dominion lives up to its nickname.

These states are currently offering average rates between 6.79% and 6.89%. Now, keep in mind this is just a snapshot in time and factors such as market volatility impact on rate of interest, but it gives you a solid starting point for your research.

The Other Side of the Coin: States With Higher Mortgage Rates

On the flip side, some states are seeing less favorable mortgage rates today. These states might have a combination of the factors mentioned above, leading to higher borrowing costs. For June 12, 2025, the states with the highest 30-year new purchase mortgage rates include:

  • Alaska: Maybe the cost of living up north is just higher in general.
  • West Virginia: Rates are among the highest in the nation.
  • Mississippi: Buyers should be aware of these high rates.
  • North Dakota: High rates are hitting this wheat-growing region.
  • Maine: Rates are less than ideal in this coastal state.
  • Kansas: Mortgage rates are pretty expensive here.
  • New Mexico: Rates are not favorable for new home purchases.
  • South Dakota: Home buyers may want to think twice.
  • Wyoming: Rates are sky high during this period.

These states are registering refinance averages between 6.99% and 7.08%. If you're in one of these states, don't despair! Shopping around and improving your credit score can still help you secure a better rate.

Decoding National Mortgage Rate Trends

It's not just about state-specific rates. The national mortgage rate scene plays a big role. As of today, June 12, 2025, the national average for a 30-year new purchase mortgage is around 6.91%.

We've seen some movement in recent months. 30-year rates had dropped every day this week, fully erasing last week's two-day surge. The rates also witnessed an all time high mid-May, when the flagship average climbed to a one-year high of 7.15%. However, things can change quickly!

Here's a quick look at how rates have fluctuated this year:

  • March: 30-year rates hit their lowest average of 2025 at 6.50%.
  • September (Previous Year): Rates plunged to a two-year low of 5.89%.

Understanding these trends can help you time your mortgage application strategically, but remember that trying to time the market perfectly is almost impossible.

To get a better picture, here are the national averages for different loan types, as provided by the Zillow:

Loan Type New Purchase Rate
30-Year Fixed 6.91%
FHA 30-Year Fixed 7.03%
15-Year Fixed 5.98%
Jumbo 30-Year Fixed 6.90%
5/6 ARM 7.15%

What's Driving These Fluctuations?

So, what's behind these ups and downs in mortgage rates? It's a complex mix of factors, including:

  • Bond Market: Mortgage rates often follow the trajectory of the bond market, especially the 10-year Treasury yield.
  • Federal Reserve (The Fed): The Fed's monetary policy, particularly its bond-buying programs and decisions about the federal funds rate, can significantly impact mortgage rates.
  • Lender Competition: Competition among lenders can drive rates down as they try to attract borrowers and stay more competitive.

Remember the period between November 2021 and July 2023 and the aggressive measure taken by the Fed to combat the inflation? The Fed decided to raise the interest rate upto 5.25 percentage points over the period of sixteen months.

Read More:

States With the Lowest Mortgage Rates on June 11, 2025

Are Mortgage Rates Expected to Go Down Soon: A Realistic Outlook

Calculating Your Potential Mortgage Payment

Okay, enough with the macroeconomics. Let's get practical. How do you figure out what your monthly mortgage payment might look like? Check out this example:

  • Home Price: $440,000
  • Down Payment: $88,000 (20%)
  • Loan Term: 30 years
  • APR (Interest Rate): 6.67%

Based on these figures, your estimated monthly payment would be around $2,649.04. Keep in mind this includes principal, interest, property taxes, and homeowners insurance. You will also need to consider things like Private Mortgage Insurance (PMI) if your down payment is less than 20%.

Don't forget that rates, insurance, and taxes are subject to change. Make sure you get the most updated information before making any decisions.

Shopping Around is Key

No matter what state you're in, shopping around for the best mortgage rate is an absolute must. Don't just take the first offer you get. Get quotes from multiple lenders and compare them carefully.

Here are a few tips for getting the best mortgage rate:

  • Improve Your Credit Score: A higher credit score can qualify you for a lower rate.
  • Save for a Larger Down Payment: Putting more money down can reduce the lender's risk and potentially lower your rate.
  • Consider Different Loan Types: Explore options like adjustable-rate mortgages (ARMs) or government-backed loans (FHA, VA) to see if they offer better terms.
  • Negotiate Fees: Don't be afraid to negotiate with lenders on fees like origination fees or points.

The Bottom Line

Mortgage rates are a moving target. While certain states currently offer lower rates, the overall market is constantly changing. By understanding the factors that influence rates and shopping around for the best deal, you can position yourself to save money on your home purchase. Staying informed is the key tool to crack the best mortgage options.

Invest in Real Estate in the Top U.S. Markets

Investing in turnkey real estate can help you secure consistent returns with fluctuating mortgage rates.

Expand your portfolio confidently, even in a shifting interest rate environment.

Speak with our expert investment counselors (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

Today’s Mortgage Rates – June 12, 2025: Rates Are Notably Down Amid Economic Shifts

June 12, 2025 by Marco Santarelli

Today’s Mortgage Rates - June 12, 2025: Rates Are Down Amid Economic Shifts

Mortgage rates are a vital indicator of the health of the housing market and have a profound impact on consumer purchasing power, refinancing decisions, and overall economic confidence. As of June 12, 2025, mortgage rates have shown signs of slight decline, sparking cautious optimism among prospective homebuyers and current homeowners.

Today’s Mortgage Rates – June 12, 2025: Rates Are Notably Down Amid Economic Shifts

The latest data from Zillow shows a subtle but noteworthy dip in mortgage rates compared to prior weeks. After months of relatively elevated rates, even small decreases can make a substantial difference in affordability for many homebuyers.

National Average Mortgage Rates

Loan Type Current Rate Change from Last Week APR APR Change
30-Year Fixed 6.91% -0.08% 7.34% -0.11%
15-Year Fixed 5.97% -0.03% 6.25% -0.11%
5-Year ARM 7.30% No change 7.83% -0.17%

Key Observations:

  • The national average for 30-year fixed-rate mortgages fell slightly from 6.99% last week to 6.91%.
  • The 15-year fixed mortgage rate slipped below 6% for the first time in weeks.
  • The 5-year ARM rate remains steady, but its APR slightly improved, reflecting marginally better borrowing costs.

This slight decline could stem from a mix of market reactions to economic data releases, inflation trends, and investor expectations for Federal Reserve monetary policy.

Detailed Mortgage Rates by Loan Type

Mortgage rates are not uniform; they differ by loan program, loan term, and borrower qualifications. Below is a breakdown of rates across the major loan categories:

Conforming Loan Rates

Program Rate Weekly Change APR Weekly APR Change
30-Year Fixed 6.91% -0.08% 7.34% -0.11%
20-Year Fixed 6.31% -0.51% 6.73% -0.51%
15-Year Fixed 5.97% -0.09% 6.25% -0.11%
10-Year Fixed 5.93% No Change 6.26% +0.09%
7-Year ARM 6.64% -1.17% 7.51% -0.72%
5-Year ARM 7.30% -0.32% 7.83% -0.17%

The 7-year ARM and 20-year fixed loans show the steepest weekly decline, signaling lender competition in these niches.

Government-Backed Loans

Program Rate Weekly Change APR Weekly APR Change
30-Year Fixed FHA 6.81% -0.11% 7.83% -0.11%
30-Year Fixed VA 6.36% -0.09% 6.57% -0.09%
15-Year Fixed FHA 5.70% +0.01% 6.67% 0.00%
15-Year Fixed VA 5.89% -0.08% 6.24% -0.09%

Government loans consistently offer slightly better rates for qualified borrowers due to backing by federal agencies, which reduces lender risk.

Jumbo Loans

Program Rate Weekly Change APR Weekly APR Change
30-Year Fixed Jumbo 7.30% -0.12% 7.76% -0.04%
15-Year Fixed Jumbo 6.54% -0.23% 6.82% -0.19%
7-Year ARM Jumbo 7.53% No Change 8.06% No Change
5-Year ARM Jumbo 7.16% -0.51% 7.77% -0.28%

Insights:

  • Jumbo loan rates remain higher than conforming loans, reflecting greater lender risk due to larger loan amounts.
  • Adjustable-rate jumbo loans have also shown downward movement, which could appeal to high-income borrowers seeking smaller payments in early years.

Factors Influencing Current Mortgage Rates

Understanding what drives mortgage rates helps borrowers anticipate trends and make better decisions.

Federal Reserve Monetary Policy

While mortgage rates do not directly track the Fed’s federal funds target rate, Fed policy heavily influences long-term interest rates through bond markets. Currently, the Federal Reserve is in a holding pattern, waiting on further economic data to determine if rate cuts are warranted. If the Fed cuts rates later this year, mortgage rates could fall in response.

Inflation and Economic Data

Mortgage rates generally rise with inflation since lenders demand higher yields to offset declining purchasing power. Recent inflation trends showing moderating price increases have contributed to downward pressure on mortgage rates.

Bond Market Movements

Mortgage rates closely correlate to yields on 10-year Treasury notes. Increased demand for safe-haven Treasuries can drive yields lower, leading to better mortgage rate offers.

Housing Market Conditions

A slowdown in home sales and price appreciation can indirectly influence rates by altering lender risk appetite and competition.

How To Get The Best Mortgage Rates Today

Securing the lowest possible rate requires more than timing the market. Here are actionable tips to optimize your mortgage application:

1. Strengthen Your Credit Profile

Your credit score is one of the most significant factors affecting your mortgage rate. Steps include:

  • Paying down credit card balances.
  • Avoiding new credit inquiries.
  • Correcting errors on your credit report.
    Lenders reward higher credit scores with lower interest rates because those borrowers are statistically less risky.

2. Maintain Stable Income and Employment

Verifiable and steady income reassures lenders, sometimes resulting in better loan offers.

3. Save for a Larger Down Payment

Higher down payments reduce loan-to-value ratios, decreasing lender risk and unlocking better rates and loan programs.

4. Shop and Negotiate with Multiple Lenders

Don’t settle for the first offer — get rate quotes from banks, credit unions, mortgage brokers, and online lenders. Compare not only interest rates but also APRs and closing costs to understand the total cost.

5. Consider Points and Loan Terms

Paying mortgage points upfront can reduce the interest rate. Additionally, choosing a shorter loan term (e.g., 15 years) usually yields lower rates, though monthly payments increase.

6. Lock Your Rate at the Right Time

Once you find a favorable rate, lock it to protect against upward volatility during the underwriting process. Rate lock durations vary, so ask your lender about options.

Will Mortgage Rates Go Down?

Predicting future mortgage rates remains inherently uncertain but analysis from expert organizations provides insight:

Expert Forecasts for 2025 and Beyond

  • Fannie Mae expects the 30-year fixed mortgage rate to average near 6.1% by the end of 2025.
  • Freddie Mac reports rates have ranged from 6.08% to 7.04% during early 2025.
  • The National Association of Realtors projects an average 6.4% in 2025, gradually falling to 6.1% in 2026.
  • Realtor.com anticipates rates dropping slightly to 6.2% toward year-end.

Factors That Could Lower Rates:

  • Federal Reserve rate cuts if economic growth slows.
  • Continued moderation in inflation, easing bond yields.
  • Increased demand for mortgage-backed securities (MBS) supporting loan pricing.

Risks That Could Keep Rates Elevated:

  • Persistent inflation pressures.
  • Robust economic growth driving bond yields higher.
  • Global economic instability increasing market volatility.

Read More:

Mortgage Rates Trends as of June 11, 2025

Will Mortgage Rates Go Down in June 2025: Expert Forecast

Mortgage Rate Forecast 2025: When Will Rates Go Below 6%?

Understanding Current Refinance Rates

Refinancing remains an important strategy for many homeowners seeking to capitalize on falling rates or adjust loan terms.

Refinance Rates Snapshot as of June 12, 2025

Loan Type Refinance Rate Weekly Change APR Weekly APR Change
30-Year Fixed 7.09% -0.06% 7.40% -0.10%
15-Year Fixed 6.00% -0.01% 6.26% -0.03%
5-Year ARM 7.81% +0.87% 8.10% +0.15%
30-Year Fixed FHA 6.53% -0.16% 7.55% -0.17%
30-Year Fixed VA 6.71% +0.13% 6.93% +0.16%

Refinance rates tend to be slightly higher than purchase mortgage rates due to underwriting risk and fees. The 5-year ARM refinance rate saw a notable increase, reflecting possible changes in adjustable rate market demand.

Should You Refinance Your Mortgage in 2025?

Refinancing is not a one-size-fits-all solution. Consider your individual financial situation:

When to Refinance:

  • Lower Interest Rates: Refinancing makes sense when current rates are at least 0.5% to 1% lower than your original mortgage. This gap helps offset closing costs and makes monthly payments more affordable.
  • Shortening Loan Term: Refinancing to a shorter-term loan can save thousands in interest over the life of the mortgage, though monthly payments increase.
  • Switching from ARM to Fixed: Homeowners concerned about future rate hikes may refinance from an adjustable-rate mortgage to a fixed-rate loan for payment stability.
  • Cash-Out Refinancing: Accessing equity through refinancing can fund home improvements, college tuition, or debt consolidation but increases loan balance and monthly payments.

Important Considerations:

  • Calculate the break-even point to determine how long it will take for the savings to cover refinancing costs.
  • Evaluate the impact on your credit score, which may dip temporarily after refinancing.
  • Assess your plans for staying in the home; refinancing is more beneficial if you plan to keep the property long term.

Meeting with a mortgage advisor for a personalized analysis is highly recommended.

Key Takeaways

  • Mortgage rates across the board are trending slightly downward as of June 12, 2025, providing opportunities for buyers and refinancers.
  • Rates vary considerably by loan type, with government-backed loans generally offering more favorable terms.
  • Economic factors, Federal Reserve policy, and inflation continue to be primary drivers of mortgage rate fluctuations.
  • Borrowers can secure better rates through strong credit, diligent lender shopping, and prudent financial planning.
  • Expert forecasts suggest modest rate declines in the latter half of 2025 but expect some ongoing volatility.
  • Refinancing remains a powerful tool if rates are favorable and long-term savings surpass refinancing costs.

Summary

As of mid-2025, mortgage rates demonstrate a modest easing, with the 30-year fixed rate averaging 6.91%. This environment offers a cautiously optimistic outlook for homebuyers and homeowners seeking to refinance. Understanding the numerous factors that influence rates, from Federal Reserve decisions to inflation data, empowers consumers to navigate the housing finance landscape more effectively.

Securing the best mortgage rate requires preparation, credit strength, and market insight, while the decision to refinance hinges on individual financial goals and current rate comparisons. Although uncertainty remains regarding the pace of future rate declines, staying informed and proactive will enable borrowers to capitalize on opportunities as the year progresses.

Invest Smarter in a High-Rate Environment

With mortgage rates remaining elevated this year, it's more important than ever to focus on cash-flowing investment properties in strong rental markets.

Norada helps investors like you identify turnkey real estate deals that deliver predictable returns—even when borrowing costs are high.

HOT NEW LISTINGS JUST ADDED!

Connect with a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now 

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

States With Lowest Mortgage Rates Today – June 11, 2025

June 11, 2025 by Marco Santarelli

States With Lowest Mortgage Rates Today – June 11, 2025

Looking for the best deal on a mortgage? As of today, June 11, 2025, the states with the lowest 30-year new purchase mortgage rates are New York, Colorado, California, Virginia, Connecticut, and New Jersey, closely followed by Florida and Texas. These states boast average rates ranging from 6.82% to 6.93%. Let's dive into why this is the case and what it means for you.

States With Lowest Mortgage Rates Today – June 11, 2025

Why Do Mortgage Rates Vary By State?

This isn't just some random occurrence – several factors contribute to these differences. As someone who's followed the mortgage market for years, I can tell you that it's rarely simple. Here's a breakdown of the key influences:

  • Lender Presence: Not every bank or mortgage company operates in every state. The level of competition among lenders can significantly impact rates. If there are more lenders vying for your business, you're more likely to get a better deal.
  • Credit Scores: Average credit scores vary state by state. States with higher average credit scores tend to see slightly better rates overall. It's all about perceived risk for the lender.
  • Average Loan Size: The size of the average mortgage loan can also play a role. States with higher property values might see lenders adjusting rates accordingly.
  • State Regulations: Each state has its own set of regulations governing the mortgage industry. These regulations can influence how lenders operate and, consequently, the rates they offer.
  • Lender Risk Management: Ultimately, it boils down to how lenders manage risk. Some lenders might be more aggressive in certain markets, offering lower rates to attract more business.

The Cheapest Vs. The Most Expensive: A Tale of Two Economies

While some states are enjoying rates below 7%, others aren't so lucky. According to Investopedia's report, the states with the highest 30-year new purchase mortgage rates today are Alaska, West Virginia, Mississippi, Kansas, North Dakota, Arkansas, South Dakota, and Wyoming, averaging between 7.02% and 7.10%. That's a pretty significant difference, and it could impact your ability to afford a home in those states.

It's important to note that these are just averages. Your individual rate will depend on your unique financial situation.

National Mortgage Rate Trends: A Bird's Eye View

Let's take a step back and look at the bigger picture. According to Zillow, the national average for a 30-year new purchase mortgage currently sits at 6.96%. This is lower than the mid-May high of 7.15%, which is encouraging. Here's a quick summary of recent trends:

  • Current Average (June 11, 2025): 6.96%
  • Mid-May 2025 High: 7.15%
  • March 2025 Low: 6.50%
  • September (Two-Year) Low: 5.89%

As you can see, rates have been fluctuating quite a bit. It's a good reminder that the mortgage market is dynamic and influenced by many external forces. Staying informed is key!

A Quick Look at National Averages for Different Loan Types

Here's a table showing the current national averages for various loan types:

Loan Type New Purchase Rate
30-Year Fixed 6.96%
FHA 30-Year Fixed 7.10%
15-Year Fixed 6.01%
Jumbo 30-Year Fixed 6.94%
5/6 ARM 7.15%

Understanding Teaser Rates

You've probably seen those incredibly low mortgage rates advertised online. Be careful! Those are often “teaser rates” designed to grab your attention. They might require you to:

  • Pay points upfront (effectively pre-paying interest)
  • Have an exceptionally high credit score
  • Qualify for a smaller-than-typical loan

In reality, the rate you actually get will depend on your individual circumstances, including your credit score, income, debt-to-income ratio, and down payment. So, it's essential to compare real offers, not just be swayed by advertised rates.

How to Shop Around for the Best Mortgage Rate

  • Check with local banks and credit unions: They sometimes have better deals than larger, national lenders.
  • Obtain quotes from 3-5 different lenders: Don't settle for the first offer you get. Comparisons can save you money.
  • Negotiate aggressively: Let lenders know that you are shopping around and are very willing to move on to the next competitive lender if they can't compete.
  • Understand all the fees involved: Don't just focus on the interest rate. Look at the total cost of the mortgage, including origination fees, appraisal fees, and other closing costs.

Read More:

States With the Lowest Mortgage Rates on June 10, 2025

Are Mortgage Rates Expected to Go Down Soon: A Realistic Outlook

Decoding the Mortgage Payment Puzzle

A mortgage payment is more than just principal and interest. It also includes:

  • Principal: The amount you borrow
  • Interest: The cost of borrowing the money
  • Property Taxes: Taxes levied by your local government
  • Homeowners Insurance: Covers damage to your home

Use a mortgage calculator to estimate your monthly payment based on different loan scenarios.

Mortgage Calculator Example

  • Home Price: $440,000
  • Down Payment: $88,000 (20%)
  • Loan Term: 30 years
  • APR: 6.67%

Estimated Monthly Payment: $2,649.04/month

Breakdown:

  • Principal & Interest: $2,264.38
  • Property Taxes: $256.67
  • Homeowners Insurance: $128.00
  • Mortgage Interest*: $463,176.16
  • Total Mortgage Paid*: $815,176.16

The Forces Behind Mortgage Rate Fluctuations

Understanding what causes mortgage rates to rise or fall can help you make informed decisions about when to buy or refinance. Here are the main factors:

  • The Bond Market: Mortgage rates tend to follow the movement of 10-year Treasury yields. Basically, if bond yields rise, mortgage rates often follow suit, and vice versa.
  • The Federal Reserve (The Fed): The Federal Reserve's monetary policy plays a significant role. Actions like buying bonds or adjusting the federal funds rate can indirectly influence mortgage rates.
  • Competition Among Lenders: When lenders are competing fiercely for business, they might lower rates to attract borrowers.
  • Inflation: High inflation can push rates higher as lenders demand a greater return to offset potential losses in purchasing power.

The Bottom Line

Navigating the mortgage market can feel overwhelming, but knowledge is power. By understanding the factors that influence mortgage rates and shopping around for the best deal, you can increase your chances of securing an affordable home loan. Keep an eye on the states with the lowest mortgage rates and be prepared to act when the time is right.

Invest in Real Estate in the Top U.S. Markets

Investing in turnkey real estate can help you secure consistent returns with fluctuating mortgage rates.

Expand your portfolio confidently, even in a shifting interest rate environment.

Speak with our expert investment counselors (No Obligation):

(800) 611-3060

Get Started Now

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

Today’s Mortgage Rates – June 11, 2025: A Steady Drop in Rates Across the Board

June 11, 2025 by Marco Santarelli

Today’s Mortgage Rates - June 11, 2025: A Steady Drop in Rates Across the Board

As of June 11, 2025, mortgage rates have shown a slight decrease, with the national average for a 30-year fixed mortgage rate at 6.95%, down from 6.96% last week. This trend indicates that rates have been easing over the past several weeks, which could be beneficial for potential homebuyers and those considering refinancing their existing loans.

Today’s Mortgage Rates – June 11, 2025: A Steady Drop in Rates Across the Board

Key Takeaways:

  • The 30-year fixed mortgage rate is down to 6.95%.
  • The 15-year fixed mortgage rate has also decreased to 6.02%.
  • The current 30-year fixed refinance rate has increased to 7.26%.
  • Mortgage rates are expected to remain stable, with potential for gradual decreases later in the year based on economic conditions and Federal Reserve policies.

Current Mortgage Rates

Understanding today’s mortgage rates requires us to differentiate between fixed and adjustable-rate mortgages as well as the terms of the loans. Below, we summarize the current mortgage and refinance rates, primarily based on data provided by Zillow.

Mortgage Rates Overview

Loan Type Current Rate 1 Week Change APR 1 Week Change
30-Year Fixed 6.95% Down 0.04% 7.38% Down 0.06%
20-Year Fixed 6.23% Down 0.59% 6.75% Down 0.50%
15-Year Fixed 6.02% Down 0.04% 6.30% Down 0.06%
10-Year Fixed 6.16% Up 0.23% 6.52% Up 0.35%
7-Year ARM 8.41% Up 0.60% 8.75% Up 0.52%
5-Year ARM 7.34% Down 0.28% 7.86% Down 0.14%

(Source: Zillow)

Current Refinance Rates

For refinancing, rates have diverged from the primary mortgage rates, with the 30-year fixed refinance rates climbing higher this week.

Loan Type Current Rate 1 Week Change APR 1 Week Change
30-Year Fixed 7.26% Up 0.08% 7.38% Down 0.06%
20-Year Fixed 6.23% Down 0.59% 6.75% Down 0.50%
15-Year Fixed 6.26% Up 0.23% 6.30% Down 0.06%
10-Year Fixed 6.16% Up 0.23% 6.52% Up 0.35%
7-Year ARM 8.41% Up 0.60% 8.75% Up 0.52%
5-Year ARM 6.94% 0.00% 7.86% Down 0.14%

(Source: Zillow)

Market Trends and Economic Influences

Understanding the current mortgage rates requires us to look at the broader economic landscape. Mortgage rates are often influenced by various factors, including inflation, employment rates, and monetary policies set forth by the Federal Reserve.

Interest Rates and Inflation

Inflation significantly impacts mortgage rates. As inflation rises, lenders tend to increase rates to safeguard their profits. Conversely, a decrease in inflation could mean lower mortgage rates. Recent indicators, such as the Consumer Price Index (CPI), suggest that inflation is gradually declining, which raises hopes for a reduction in mortgage rates in the coming months.

Historical Context of Mortgage Rates

In the past few years, mortgage rates have fluctuated considerably due to shifts in economic conditions. Historically, anything below 7% could be regarded as favorable. With the average 30-year fixed mortgage rate currently at 6.95%, buyers have the opportunity to lock in relatively low rates when compared to the highs seen in previous years.

Federal Reserve's Role

The Federal Reserve exerts significant influence over mortgage rates through its monetary policies. The expectation is that the Federal Reserve will maintain its current stance on interest rates in its next meeting, signaling a pause on increases in the short term. Such stability can lead to more predictable mortgage rates for borrowers.

Economic Growth and Unemployment

The state of economic growth plays a large role in mortgage pricing. Current indications suggest a sluggish economy, which could contribute to further declines in mortgage rates. The unemployment rate remains low, but wage growth has been inconsistent, limiting consumer spending power.

Refinancing Considerations

Refinancing may be an attractive option, especially as mortgage rates decline. However, potential borrowers must consider various factors before making this decision:

Pros:

  • Lower Monthly Payments: A reduced interest rate means lower monthly payments, allowing for increased cash flow.
  • Equity Access: Refinancing can allow homeowners to tap into available equity for upgrades or consolidating debt.
  • Shorter Loan Terms: Moving to a shorter-term loan could result in paying less interest over the loan's lifetime.

Cons:

  • Closing Costs: Borrowers need to be aware that refinancing comes with closing costs that may negate some savings from lower rates.
  • Resetting of Terms: Refinancing could reset the loan term, potentially increasing the overall interest paid over time.
  • Impact on Credit: The refinance process typically involves a hard credit inquiry, which can temporarily affect credit scores.

Read More:

Mortgage Rates Trends as of June 10, 2025

Will Mortgage Rates Go Down in June 2025: Expert Forecast

Mortgage Rate Forecast 2025: When Will Rates Go Below 6%?

Predictions for Mortgage Rates in 2025

Looking ahead, several predictions indicate that mortgage rates may continue to drop throughout 2025. Various financial institutions offer different forecasts, but there appears to be a general consensus that:

  • Mid-2025 Targets: Predicted rates could fall between 5.5% to 6.5% for the average 30-year fixed-rate mortgage.
  • End-of-Year Projections: By the end of 2025, rates may stabilize around 6.0%, offering favorable terms for both homebuyers and those considering refinancing.

Rate Predictions for 2025

Forecast Period Expected Rate (%) Sources
Mid-2025 5.5% – 6.5% Freddie Mac, Fannie Mae
End-2025 6.0% Freddie Mac, Bankrate
End-2026 6.2% Fannie Mae

Factors Influencing Homebuyers Today

Several related topics are important to discuss in the context of today's mortgage rates. Understanding these elements can help prospective homebuyers make more informed decisions:

Housing Market Inventory

The housing market has seen fluctuations in inventory levels, impacting home prices and mortgage rates. A decrease in available homes often results in a competitive market, keeping prices elevated. It’s vital for buyers to stay abreast of local inventory trends, especially as construction rates increase or slow.

Impact of Current Events

Global events can significantly affect the housing market and mortgage rates. For instance, geopolitical tensions, trade agreements, or significant economic policies can create ripples throughout the economy. Potential homeowners should consider how such factors might influence their purchasing power or the interest rates they are offered.

Technological Influences

Technology in the real estate and mortgage sectors has improved accessibility and efficiency in securing loans. Online platforms make it easier for borrowers to compare mortgage rates, access mortgage calculators, and complete applications. Understanding how to leverage these technological advancements can be beneficial for modern homebuyers looking to secure the best possible rates.

Summary:

In summary, mortgage rates today are showing a slight decrease, indicating potential advantages for homebuyers or those considering refinancing. Monitoring economic indicators and Federal Reserve policies will be crucial in understanding future mortgage rate movements.

Invest Smarter in a High-Rate Environment

With mortgage rates remaining elevated this year, it's more important than ever to focus on cash-flowing investment properties in strong rental markets.

Norada helps investors like you identify turnkey real estate deals that deliver predictable returns—even when borrowing costs are high.

HOT NEW LISTINGS JUST ADDED!

Connect with a Norada investment counselor today (No Obligation):

(800) 611-3060

Get Started Now 

Also Read:

  • Will Mortgage Rates Go Down in 2025: Morgan Stanley's Forecast
  • Expect High Mortgage Rates Until 2026: Fannie Mae's 2-Year Forecast
  • Mortgage Rate Predictions 2025 from 4 Leading Housing Experts
  • Mortgage Rates Forecast for the Next 3 Years: 2025 to 2027
  • 30-Year Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Mortgage Rate Forecast for the Next 5 Years
  • Why Are Mortgage Rates Going Up in 2025: Will Rates Drop?
  • Why Are Mortgage Rates So High and Predictions for 2025
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Interest Rate, mortgage, Mortgage Rate Trends, mortgage rates, Mortgage Rates Predictions, Mortgage Rates Today

  • « Previous Page
  • 1
  • …
  • 115
  • 116
  • 117
  • 118
  • 119
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...