Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Today’s Mortgage Rates, February 23: Rates Remain Stable With No Major Volatility

February 23, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're looking to buy a home or refinance an existing mortgage, you're probably wondering about the numbers. Well, as of Monday, February 23, 2026, I'm seeing a slight nudge upward in mortgage rates, but overall, things are holding pretty steady compared to last week. Zillow reports that the national average for a 30-year fixed purchase mortgage is sitting at 5.875%, and the 15-year fixed is at 5.375%.

Both have crept up just a hair since last Monday. While these are small shifts, they signal a cautious approach to borrowing costs, and importantly, they're still a far cry from the peak rates we saw in 2025. This means potential buyers and those thinking about refinancing can get a clearer picture of what to expect when looking for a loan right now.

Today’s Mortgage Rates, February 23: Rates Remain Stable With No Major Volatility

Current Purchase Loan Rates

Here’s a snapshot of what lenders are generally offering for purchase mortgages today, based on Zillow's national averages for February 23, 2026. Keep in mind that your actual rate can differ based on your credit score, down payment, and other factors.

Also, over the past few days, mortgage rates have been like a calm lake with just a few ripples – we’ve seen very little movement, just a minor upward creep. It’s not enough to cause any alarm bells, but it’s worth noting.

Loan Type Interest Rate APR
30-Year Fixed 5.875% 6.032%
20-Year Fixed 6.000% 6.203%
15-Year Fixed 5.375% 5.657%
10-Year Fixed 5.250% 5.682%
30-Year FHA 5.625% 6.307%
30-Year VA 5.625% 5.906%
30-Year Jumbo 5.875% 6.031%
7/6 ARM 5.625% 6.168%

Note: APR (Annual Percentage Rate) reflects the total cost of borrowing, including fees and other charges, giving you a more complete picture than just the interest rate alone.

Weekly Trend Comparison

Looking back at last Monday, February 16, 2026, rates have edged up just a tiny bit:

  • 30-Year Fixed: Increased by 0.025% (from 5.85% to 5.875%)
  • 15-Year Fixed: Increased by 0.015% (from 5.36% to 5.375%)

These are very small bumps. In my experience, when rates are this stable, it’s often a sign that either the Federal Reserve has signaled a holding pattern, or the market is digesting various economic data without any major surprises.

Market Context: Where Do We Stand?

Even with these modest increases, the current rates are still looking pretty good when you compare them to last year. Remember in 2025 when the average 30-year fixed rate was floating around 6.85%? We're significantly below that now.

Fannie Mae is predicting that the 30-year fixed rate will pretty much hover around the 6% mark for the rest of 2026. This suggests we're in a relatively calm period for borrowing costs, which is welcome news for anyone entering the housing market. It means more predictability, which is always a plus when making such a huge financial decision.

What Borrowers Should Know

Based on the numbers I'm seeing today, here’s what I think different types of borrowers should be aware of:

  • Homebuyers: If you're looking to buy, rates still under 6% are a big win compared to the higher rates of last year. This helps make that dream home more affordable each month.
  • Refinancers: Even with these tiny rate increases, if you have an older mortgage with a rate significantly above 6.5%, refinancing today could still save you a good chunk of money over the life of your loan. It's always worth checking if you can snag a better deal.
  • VA and FHA Borrowers: For those using government-backed loans, good news! VA and FHA loans are staying competitive. The 30-year VA loan at 5.625% and the 30-year FHA loan at 5.625% offer excellent value.
  • ARM Borrowers: Adjustable-rate mortgages (ARMs) are priced very closely to fixed-rate loans right now. This means the typical appeal of ARMs—lower initial payments for potential long-term savings—isn't as strong. If you value payment stability, a fixed-rate mortgage might be a better bet.

Why Aren't Rates Dropping More Dramatically?

Even though we aren't seeing wild swings, there are a few economic forces at play that are keeping rates from dipping much lower. From my perspective, these are the key factors:

  • Mixed Economic Signals: The job market is still pretty robust, and people are generally seeing steady wage growth. When the economy is doing well like this, it tends to put a little upward pressure on interest rates. The thinking is, if the economy isn't cooling down fast enough, the Federal Reserve might not feel the urgency to slash rates aggressively.
  • Treasury Yield Fluctuations: Mortgage rates tend to move in lockstep with the 10-year Treasury yield. Right now, that yield has been hanging around 4.08%. A small uptick in these yields over the weekend is directly contributing to that tiny increase we're seeing in Zillow's mortgage rates. It's a very direct connection.
  • Geopolitical Uncertainty: Believe it or not, global events can impact your mortgage rate. Tensions in the Middle East, for instance, or even major international trade talks (like those rumored about Greenland, for example) can make some investors nervous. They tend to move their money into safer investments, which can help stabilize rates. However, it also adds a layer of unpredictability to day-to-day market movements.
  • Policy Impact Fading: Remember that $200 billion mortgage-backed securities purchase program announced back in early January? Its initial downward push on rates seems to be wearing off. Now, the market is sort of trading within its existing bands, without a strong new catalyst to drive rates significantly lower or higher.

Overall, many experts are describing this period as a “balanced interest-rate environment.” We’re seeing progress on inflation, but that's being balanced out by a strong job market. This combination is keeping rates near three-year lows without a clear sign of a major shift in either direction for this week. For borrowers, this means it's a good time to lock in a rate if you find one you're happy with, rather than waiting for a dramatic drop that may not materialize.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 23: 30-Year Refinance Rate Rises by 4 Basis Points

February 23, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of February 23, 2026, the national average 30‑year fixed refinance rate is holding steady at 6.47%, a modest increase of just 4 basis points from last week's average. This suggests a period of relative calm in the mortgage market, offering a predictable environment for homeowners looking to refinance.

Mortgage Rates Today, February 23: 30-Year Refinance Rate Rises by 4 Basis Points

It’s understandable why you’d be checking “mortgage rates today.” We all want to know if now is the right moment to refinance our homes or secure that new home loan. The numbers we see, even small changes like those few basis points, can really add up, affecting how much we pay each month and how much interest we shell out over the life of the loan.

Current Refinance Rates on February 23, 2026

Let's break down what the rates look like right now, according to Zillow:

  • 30‑year fixed refinance rate: 6.47% (up 4 basis points from last week)
  • 15‑year fixed refinance rate: 5.56% (no change)
  • 5‑year ARM refinance rate: 6.99% (stable from yesterday, a bit higher than last week)

For those of you who, like me, are keeping a close eye on these numbers, you’ll see that the big headlines here are stability and slight movement. The 30-year fixed, the most popular choice for many, is barely budging. The 15-year fixed is still holding its ground, and the adjustable-rate mortgage (ARM) is a bit higher but not dramatically so.

What These Rates Mean for You

When we talk about refinancing, the goal is usually to save money. So, what does this current rate environment mean for your wallet?

  • The 30-Year Fixed at 6.47%: This rate offers a good amount of predictability for homeowners who like knowing exactly what their payment will be for the next three decades. If your current rate is significantly higher than this, refinancing could still be a smart move to lower your monthly bills.
  • The 15-Year Fixed at 5.56%: For folks who want to own their homes outright sooner and save on total interest paid, this rate is still a very attractive option. It’s a great way to build equity faster, but of course, the monthly payments will be higher than a 30-year loan.
  • The 5-Year ARM at 6.99%: Honestly, compared to the fixed rates, ARMs look a bit less appealing right now. With their potential to jump up after the initial period, they carry more risk, especially when fixed rates are this stable. I'd say proceed with caution if you're thinking about an ARM.

The Mortgage Market's Pulse

It's not just about the raw numbers; it's about why the numbers are where they are. The slight increase in the 30-year fixed rate likely reflects lenders being a bit more cautious. They're watching the economic winds very closely. However, the overall stability tells me the market is in a bit of a “wait-and-see” mode. There aren't huge swings that should make anyone panic or rush into a decision. This gives us all a chance to make a more considered choice.

The Big Picture: Policy vs. Inflation

For anyone trying to make sense of mortgage rates, and frankly, a lot of other financial news, the biggest driving force right now is the push and pull between what the Federal Reserve is doing and what inflation is doing. After cutting rates three times in late 2025, the Fed decided to hold them steady at their January 2026 meeting. But here's the twist that came out in meeting minutes released on February 18: some people at the Fed are talking about possibly raising rates again if inflation doesn't cool down. That's a big deal because it could signal a shift in their strategy.

Here’s what I think is important to remember:

  • The “Lock-In” Effect is Real: You've probably heard this term a lot. Generally, refinancing makes financial sense if the rate you're being offered today is at least 0.5% to 1% lower than your current mortgage rate. Right now, this means a lot of people who got their mortgages between 2023 and 2025, when rates were higher, are the ones who stand to benefit most from refinancing.
  • Government Actions Can Help: There's talk of a $200 billion program to buy mortgage bonds. If this happens, it could help push mortgage rates down a bit by making them more attractive compared to other investments, like the 10-year Treasury yield.
  • Rate Drops Aren't Expected to Be Huge: The general feeling is that mortgage rates will likely drift down slowly throughout 2026, maybe settling just under 6% for the 30-year fixed. Big, dramatic drops? Those probably won't happen unless we hit a serious economic downturn, a recession.

What Homeowners Should Really Consider

Beyond the headline rate, there are other things to keep in mind, especially for those of you evaluating if refinancing is worth it.

  • Don't Forget Closing Costs: Refinancing isn't free. You'll have fees, often ranging from 2% to 6% of your loan amount. It's crucial to do the math and figure out how long it will take for your monthly savings to cover these costs. I always advise aiming for a break-even point within two to three years. If it takes longer, it might not be worth the hassle.
  • Tap Into Your Home Equity Wisely: The “lock-in” effect I mentioned? It means many homeowners are sitting on historically low mortgage rates (think below 5% or even 4% from the pandemic era). For these folks, refinancing their entire mortgage might not make sense. Instead, if you need cash, options like home equity lines of credit (HELOCs) or second mortgages (which are currently around 8%) might be a better way to access your home's value without giving up that super-low first mortgage rate.
  • Inventory is Still Tight: This “lock-in” effect is also a huge reason why there aren't many homes for sale. People with those cheap mortgages aren't eager to sell and then buy a new home with a much higher interest rate. This impacts the entire housing market.

In Summary

For February 23, 2026, mortgage refinance rates are showing a stable picture. The 30‑year fixed rate at 6.47% is the key number to watch, and it’s not moving much. This steadiness is good news for borrowers who want to make informed decisions without feeling pressured by sudden market shifts.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 22, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, February 22: Buyers Get Affordable Financing Across Fixed and VA Loans

February 22, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

On February 22, 2026, today's mortgage rates are looking remarkably favorable, hovering near multi-year lows. According to Zillow's latest data, the average rate for a 30-year fixed mortgage is a compelling 5.86%, making this a prime time for many to enter the housing market or lock in better terms.

These kinds of rates don’t come around every day. We’ve seen some wild swings in the past few years, but right now, things are settling into a rhythm that's genuinely beneficial for borrowers. It’s not just about the headline number; it’s about what that number translates to in terms of affordability and long-term savings.

Today’s Mortgage Rates, February 22: Buyers Get Affordable Financing Across Fixed and VA Loans

What the Numbers Mean for You

Seeing a number like 5.86% for a 30-year fixed mortgage is significant. It means that the cost of borrowing money for your home is more manageable than it has been in quite some time. But what about other loan types? Zillow’s data gives us a broader picture:

Here’s a breakdown of the average rates across popular loan products as of February 22, 2026, according to Zillow:

Loan Product Average Rate (%) Notes
30‑year fixed 5.86% The go-to for stability and predictable monthly payments.
20‑year fixed 5.82% A good middle ground: faster equity, slightly lower rate.
15‑year fixed 5.41% Pay off your home sooner, save big on interest.
5/1 ARM 5.97% Rate fixed for 5 years, then adjusts annually.
7/1 ARM 6.10% Rate fixed for 7 years, then adjusts annually.
30‑year VA 5.50% Excellent option for veterans and service members.
15‑year VA 5.06% For eligible borrowers looking to build equity faster.
5/1 VA 5.24% Adjustable-rate option for VA-eligible borrowers.

What jumps out to me? The fact that the 30-year fixed rate is under 6% is a huge deal. It makes long-term homeownership feel much more attainable. The slight difference between the 30-year fixed at 5.86% and the 20-year fixed at 5.82% is minimal, so for some, the extra $200-$30 you might shave off a payment over 20 years versus 30 might be worth it for faster equity. And the 15-year fixed at 5.41%? That’s a fantastic rate for those who can comfortably afford the higher monthly payments and want to be mortgage-free quicker.

Why Are Rates So Favorable Right Now? A Deeper Dive

It’s easy to see the numbers, but understanding why they are what they are gives you more power in your financial decisions. Several key factors are influencing these mortgage rates:

  • The Federal Reserve's Strategy: Remember how the Federal Reserve has been working to bring inflation under control? After making a few rate cuts in late 2025, they’ve held steady. This past January 2026 meeting, they kept the federal funds rate between 3.50% and 3.75%. The minutes from their February 18 meeting showed that officials are patiently waiting for more solid evidence that inflation is sticking to their 2% target. This cautious approach is crucial. When the central bank signals stability or potential future cuts, it tends to lower borrowing costs across the economy, including mortgages. I always tell people to pay attention to the Fed minutes – they are like a roadmap for future economic moves.
  • Treasury Yields: Mortgage rates have a very close relationship with the yields on 10-year Treasury notes. Think of it like this: lenders often bundle and sell mortgages as investments. If they can get a better return on safer government bonds, they might need to charge more for mortgages. Conversely, when Treasury yields go down, mortgage rates often follow. We’ve seen the 10-year Treasury note recently dip to around 4.06%. This downward pressure is a significant reason why mortgage rates have become more affordable.
  • Government Housing Initiatives: There was some buzz in early January 2026 about a proposed $200 billion mortgage-backed securities purchase program from the Trump administration. Initially, this news helped drive rates lower, as it signaled a commitment to supporting the housing market. However, like many policy announcements, the immediate impact can fade. Experts suggest we’re now in a more stable, “wait-and-see” period, where the market has digested that news and is reacting more to ongoing economic data rather than immediate policy shifts.

What Experts Are Predicting for the Rest of 2026

Forecasting the future is tricky, but looking at what major institutions are saying can offer some perspective. The general consensus is that for the rest of 2026, we’re likely to see mortgage rates stay within a relatively narrow band.

  • Fannie Mae and the Mortgage Bankers Association (MBA) are predicting that the average 30-year fixed rate will hover around 6.1% for most of the year. This suggests a period of relative stability, where borrowing might not get significantly cheaper, but it's unlikely to skyrocket either.
  • Morgan Stanley strategists have a slightly more optimistic outlook. They believe there’s a possibility of rates dipping towards 5.50%–5.75% by mid-2026 if those 10-year Treasury yields continue their downward trend. However, they do anticipate a modest increase in the latter half of the year.

From my vantage point, these forecasts highlight that while we're in a good spot now, it's wise to consider acting if you find a rate that meets your needs. Waiting for the absolute lowest point can be a gamble, and securing a solid rate today might be more beneficial than chasing a speculative drop.

The Impact on Homebuyers and Refinancers

This current rate environment has significant implications for people like you and me:

  • For Homebuyers: When the 30-year fixed rate is 5.86%, the monthly payment for a given loan amount is considerably lower than when rates were in the 7s or 8s. This improved affordability can make the dream of homeownership a reality for more people. Your purchasing power increases, meaning you might be able to afford a slightly larger home or a more desirable location. It’s a tangible benefit that directly impacts your budget.
  • For Refinancers: If you took out a mortgage in 2024 or 2025 when rates were higher (think 7% or more), refinancing now could lead to substantial savings. Zillow noted that refinance applications have more than doubled in the past year, which makes perfect sense. People are actively looking to lower their monthly payments and reduce the total interest paid over the life of their loan. Even a half-percent or one-percent decrease can save you tens of thousands of dollars over 15 or 30 years. It’s a smart financial move if your current rate is significantly higher than today’s offerings.
  • For VA Borrowers: The rates offered for VA loans, both fixed and adjustable, are consistently among the lowest available. With the 30-year VA rate at 5.50% and the 15-year VA at 5.06%, these are truly standout options. If you’re a veteran or active-duty service member, it’s almost always worth exploring a VA loan first, as it can offer exceptional value.

My Take: Don't Let Opportunity Slip By

As I see it, the mortgage market on February 22, 2026, presents a solid opportunity. Rates are down from recent highs, offering improved affordability for buyers and significant savings potential for refinancers. While perfect certainty is impossible, the Fed’s stable stance and the current Treasury yield environment suggest that locking in a rate near the current levels is a prudent move for many.

My advice? If you’ve been on the fence about buying or refinancing, now is the time to get serious. Talk to a mortgage professional, get pre-approved, and understand what rate you can qualify for. Don’t let the perfect be the enemy of the good. A solid rate today is much better than waiting for a slightly lower rate tomorrow that might never materialize.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 22: 30-Year Refinance Rate Drops by 17 Basis Points

February 22, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

If you're looking to refinance your home, today's news is a welcome one: the national average 30-year fixed refinance rate has dropped significantly, falling by 17 basis points to 6.31% as of February 22, 2026, according to Zillow. This dip offers a much-needed breath of fresh air for many homeowners after a period of seesawing rates.

Mortgage Rates Today, February 22: 30-Year Refinance Rate Drops by 17 Basis Points

What Today's Rate Drop Means for You

Let's break down this move. A 17-basis-point drop might sound small on paper, but when you're talking about a 30-year loan, it can translate into thousands of dollars saved over the life of your mortgage. This move back down to 6.31% is a positive development, especially when you consider that last week's average was 6.48%. For homeowners who have been sitting on the fence, waiting for a better opportunity to refinance and potentially lower their monthly payments or get cash out, this might be the signal they've been waiting for.

It's also important to note the movement in other refinance products. While the 30-year fixed rate declined, the 15-year fixed refinance rate saw a minor increase, nudging up 2 basis points to 5.56%. Similarly, the 5-year Adjustable-Rate Mortgage (ARM) refinance rate climbed 6 basis points to 7.03%. This mixed movement paints a picture of a market that's still finding its equilibrium.

Diving Deeper: Why Rates Are Moving Like This

Understanding why mortgage rates change is key to making smart financial decisions. It’s not just about one number; it’s about a complex interplay of economic forces.

  • Mixed Economic Signals: Right now, the economy is sending us some pretty mixed messages. On one hand, we're seeing signs of a cooling labor market, which is generally good for keeping inflation in check. Also, declining oil prices (hovering around $66.22 per barrel) can ease some inflationary pressures. However, persistent inflation concerns are still hanging around, preventing a more significant drop in interest rates. It's like trying to steer a ship with one hand pulling the sails in and the other pushing them out – a delicate balance.
  • Impact of Government Programs: Remember that $200 billion mortgage-backed securities purchase program that kicked off in January 2026? That was designed to help lower rates, and it did, for a while. However, experts are starting to say that its biggest impact might be fading. This is common; government interventions can provide a temporary boost, but the underlying economic fundamentals eventually take over.
  • Bond Market Buzz: Mortgage rates are closely tied to the bond market, particularly the yields on U.S. Treasury bonds. When Treasury yields go down, mortgage rates tend to follow. The fluctuations we're seeing are a reflection of investors’ reactions to all these different economic signals.

Looking Ahead: What Experts Are Saying for 2026

So, what’s the crystal ball telling us for the rest of 2026? The general consensus among housing authorities suggests a period of relative stability, but with a few different opinions on the exact numbers.

  • Fannie Mae's Crystal Ball: They are predicting that 30-year fixed mortgage rates will likely stay close to 6.0% for the remainder of the year. This would be great news for borrowers if it holds true.
  • MBA's Forecast: The Mortgage Bankers Association (MBA) is looking for rates to trade within a range of 6.0% to 6.5%. This offers a bit more of a buffer and acknowledges the potential for some upward movement.
  • Morgan Stanley's Optimism: More on the optimistic side, Morgan Stanley suggests that if the 10-year Treasury yield manages to fall to 3.75%, we could potentially see rates dip to the 5.50%–5.75% range by mid-2026. That would be a significant drop and a fantastic opportunity for many.

From my perspective, these forecasts are helpful benchmarks, but it’s crucial to remember they are just that – predictions. The economy is a dynamic entity, and unforeseen events can always shift the trajectory.

Refinance Options: A Quick Rundown

Let’s quickly recap the rates reported by Zillow for February 22, 2026, and what they mean:

Loan Type Rate (February 22, 2026) Change from Previous Week What it Means for You
30-Year Fixed 6.31% ↓17 basis points Excellent opportunity to lower long-term payments.
15-Year Fixed 5.56% ↑2 basis points Still competitive for faster equity building, but a slight rise.
5-Year ARM 7.03% ↑6 basis points Less attractive due to volatility and higher starting cost compared to fixed.

Why This Matters for Homeowners

For homeowners, especially those who secured their mortgages when rates were at their peak (around the 7% mark in early 2025, for instance), this current environment presents a prime window to potentially reduce their annual mortgage payments substantially. Even a seemingly small reduction in your interest rate can add up to thousands of dollars saved over the next 15 or 30 years. It could mean the difference between just making ends meet and having a little extra breathing room in your budget.

Implications for Borrowers Today

  • Those Looking to Refinance: The drop in the 30-year fixed rate to 6.31% is your headline. If your current rate is higher, it’s definitely worth exploring if refinancing makes sense for you. Consider what your goals are: are you looking to lower your monthly payment, shorten your loan term, or tap into your home equity?
  • Homeowners Focused on Quick Equity: The slight increase in the 15-year fixed rate to 5.56% keeps this option very attractive for those who want to pay off their mortgage faster and build equity more quickly. The change is minimal, so it’s still a strong contender.
  • Borrowers Considering ARMs: With the 5-year ARM rate climbing to 7.03%, fixed-rate mortgages are looking more appealing by comparison. ARMs can be great in certain situations, but the current trend suggests predictability and stability are currently favoring fixed rates.

My Take: Don't Wait Too Long, But Be Prepared

In my experience, the mortgage market rarely stays in one place for too long. While today’s news is good, it’s wise to act on opportunities when they arise. However, acting doesn't mean rushing into anything blindly. Before you jump into refinancing, I always recommend:

  1. Knowing Your Current Mortgage: What's your current interest rate, and how much time is left on your loan?
  2. Understanding Your Financial Goals: What do you want to achieve with a refinance?
  3. Shopping Around: Don't settle for the first offer you get. Compare rates and fees from multiple lenders.
  4. Calculating the Break-Even Point: How long will it take for the savings from your lower payment to recoup the closing costs of the refinance?

Today, February 22, 2026, brings a notable drop in the 30-year fixed refinance rate to 6.31%, offering a significant opportunity for homeowners to potentially lower their long-term borrowing costs.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 20, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, February 21: 30-Year Fixed at 5.86%, 15-Year Climbs to 5.41%

February 21, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Today, mortgage rates have seen a small bump over the weekend but are holding steady below the crucial 6% mark, suggesting that borrowing costs remain quite favorable. According to data from Zillow, the popular 30-year fixed mortgage rate now stands at 5.86%, a slight rise of five basis points, while the 15-year fixed rate has nudged up to 5.41%. This stability, even with minor fluctuations, offers a breathing room for potential homeowners and those looking to reduce their monthly payments that we haven't seen consistently in recent years.

Today’s Mortgage Rates, February 21: 30-Year Fixed at 5.86%, 15-Year Climbs to 5.41%

What the Numbers Tell Us: Today's Average Rates

Let's break down exactly where things stand for various loan types on this particular day, February 21, 2026. These averages, as reported by Zillow through their lender marketplace, give us a clear snapshot:

Loan Term Interest Rate
30-Year Fixed 5.86%
20-Year Fixed 5.82%
15-Year Fixed 5.41%
5/1 Adjustable-Rate Mortgage (ARM) 5.97%
7/1 Adjustable-Rate Mortgage (ARM) 6.10%
30-Year VA Loan 5.50%
15-Year VA Loan 5.06%
5/1 VA Loan 5.24%

As you can see, the 30-year fixed rate has edged up, but it's still firmly below 6%. The 15-year fixed rate has also seen a small increase. Interestingly, both the 5/1 and 7/1 ARMs are currently hovering slightly above the 30-year fixed rate, which might make traditional fixed-rate mortgages a more attractive option for those prioritizing payment predictability. For our nation's veterans and active-duty military, VA loans continue to be a fantastic option, with rates remaining quite appealing, especially for the 15-year term.

Deeper Dive: Market Insights and What They Mean

These figures aren't just random numbers; they're influenced by a number of factors. The slight uptick over the weekend likely reflects a bit of market rebalancing. However, it’s crucial to remember that compared to the higher rates we experienced not too long ago, current borrowing costs are still considerably more manageable.

  • The 30-Year Fixed at 5.86%: This is the workhorse for most homebuyers. It offers the comfort of knowing your monthly principal and interest payment will stay the same for three decades. The stability it provides is invaluable, especially in uncertain economic times. Even a small increase here is worth noting, but the fact it's holding below 6% is the real story.
  • The 20-Year Fixed at 5.82%: This option is often overlooked, but it presents a nice middle ground. You get a slightly shorter loan term than the 30-year, leading to faster equity build-up, and your rate isn't dramatically higher. For some, this balance is perfect.
  • The 15-Year Fixed at 5.41%: This is the speedster for building equity. While the monthly payments will be higher than a 30-year loan, you'll pay significantly less in interest over the life of the loan and own your home free and clear much sooner. Many homeowners I’ve spoken with who are eyeing early retirement or financial freedom consider this the gold standard if they can manage the payment.
  • Adjustable-Rate Mortgages (ARMs): The 5/1 ARM at 5.97% and the 7/1 ARM at 6.10% are a reminder that these loans come with a trade-off. Initially, they might offer a lower rate than fixed mortgages, but after the fixed period ends, your rate can adjust up (or down) based on market conditions. Right now, with fixed rates so competitive, ARMs might be less appealing unless you have a very specific plan to move or refinance before the adjustment period.
  • VA Loans: I’ve always been impressed by the value these loans bring to our service members. Rates like 5.50% for the 30-year and an outstanding 5.06% for the 15-year are incredibly competitive. It’s a tangible way the government supports those who have served, and it’s a smart financial move for eligible borrowers.

Navigating the Federal Reserve's Influence and Other Key Factors

Understanding what’s driving these rates is as important as knowing the numbers themselves. One of the biggest players is, of course, the Federal Reserve.

The Federal Reserve “Pause”: As of their January 2026 meeting, the Fed decided to keep the federal funds rate steady in the 3.5%–3.75% range. This followed a series of three rate cuts late last year. However, there's some debate among policymakers about whether to continue cutting rates in March. The concern is “sticky” inflation, meaning inflation that’s proving harder to bring down than expected. This hesitation by the Fed can lead to a cautious approach from lenders, influencing mortgage rates.

Refinance Opportunity Abounds: It’s no surprise that refinance activity has more than doubled over the past year. When rates dipped towards 6%, many homeowners who purchased between 2023 and 2025 saw a golden opportunity to slash their monthly payments. I’ve heard from clients whose new payments are hundreds of dollars less each month, freeing up significant cash flow. If you’re in this group, it's worth checking if today's rates still offer a compelling reason to refinance.

Inventory and Price Pressures: This is a critical point. Even with more favorable rates, the housing market is still constrained by a lack of available homes. Economists are warning that if interest rates continue to fall, it could spark a renewed surge in buyer competition. This intensified demand, coupled with limited supply, could potentially push home prices up again, potentially negating some of the savings gained from lower mortgage rates. It's a delicate balancing act.

Policy Watch: Government initiatives can also play a role. The current administration is reportedly looking at ways to ease borrowing costs. A specific mention of a potential $200 billion purchase of mortgage-backed securities by Fannie Mae and Freddie Mac is designed to inject liquidity into the market and potentially lower rates further. These are significant policy moves to watch.

What Does This Mean for You?

Let’s translate these market movements into actionable advice for different groups of people:

  • For Homebuyers: If you’re looking to make your first purchase or move up, rates still hovering below 6% are a definite advantage. Locking in a long-term fixed product at these levels can provide significant savings and peace of mind. Don't forget to put your best foot forward with your credit score and down payment, as these can dramatically affect the rate you're offered.
  • For Refinancers: While the rates have ticked up slightly, they are still a far cry from the highs of recent years. If you bought your home between 2023 and 2025, it's highly probable that refinancing now could lead to noticeable savings. I always advise getting a few quotes to compare.
  • For VA Borrowers: You continue to be in a strong position. VA loan rates are consistently among the most competitive. If you’re an eligible veteran or service member, exploring these options is a no-brainer.

Wrapping Up Today's Rates

On February 21, 2026, the mortgage rate environment remains more than just favorable; it’s an opportunity. The slight uptick in rates isn't a cause for alarm but a sign of a dynamic market. With the benchmark 30-year fixed rate at 5.86% and specialized options like VA loans offering even lower costs, there are clear advantages for both those looking to buy and those aiming to lower their current payments through refinancing.

Market Outlook: Many experts are calling this period “The Great Housing Reset.” The general consensus is that rates will likely stick around the low-6% to high-5% range for much of 2026. My advice from years of observing these markets is always to shop around thoroughly. The difference in offers between lenders can be substantial, sometimes as much as a full percentage point, depending on your specific financial profile.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 21: 30-Year Refinance Rate Rises by 77 Basis Points

February 21, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

The 30-year fixed refinance rate shot up by a significant 77 basis points today, February 21, 2026, landing at 7.25%, according to Zillow’s latest data. This sudden jump means that getting a new mortgage to replace an existing one just became a lot more expensive for many homeowners.

Mortgage Rates Today, February 21: 30-Year Refinance Rate Rises by 77 Basis Points

Let's break down what happened today, February 21, 2026, according to Zillow. The big story is the 30-year fixed refinance rate. It went from a much more palatable 6.44% yesterday to a hefty 7.25% today. That’s an 81 basis point jump in a single day! If you’re doing the math, that's a huge difference, especially when you're talking about borrowing hundreds of thousands of dollars over three decades.

This isn't just a minor wobble; it’s a serious climb that erases the progress seen over the past week. Compare today’s 7.25% to the average of 6.48% from last week, and you see that 77 basis point increase starkly. It means the cost of borrowing for homeowners looking to refinance has gone up considerably, and quickly.

It wasn't just the 30-year fixed rate that decided to take a hike. Other popular refinance options also saw increases:

  • 15-year fixed refinance rate: This jumped from 5.52% to 5.99%, a rise of 47 basis points. While still lower than the 30-year rate, that increase makes it less attractive than it was yesterday.
  • 5-year Adjustable-Rate Mortgage (ARM) refinance rate: This one actually held steady at 7.00%. While it didn't go up, it’s still a pretty high rate, and staying stagnant at that level doesn't offer much comfort.

Why the Big Jump? Market Insights You Need to Know

So, what’s behind this sudden surge? When we see rates move this much, this fast, it usually means the lending market is reacting to bigger economic shifts. Think of lenders as super-sensitive thermometers for the economy. They see changes in inflation, bond markets, and the general economic outlook, and they adjust mortgage rates accordingly.

The sharp rise in the 30-year fixed refinance rate to 7.25% tells me lenders are likely feeling pressure from inflation concerns and adjustments in the broader bond market. When Treasury yields, especially those of longer-term bonds, start climbing, mortgage lenders have to raise their rates to make lending profitable and competitive. It’s a domino effect.

  • For the 30-Year Fixed: At 7.25%, this rate is hitting levels we haven't seen in a while. For homeowners who were hoping to snag a lower payment, this increase makes it much harder to find significant savings. It really hammers home the idea that timing is everything in the refinance game, and today, the timing wasn't on the borrower's side.
  • For the 15-Year Fixed: While 5.99% is still better than many rates we’ve seen in recent years, the gap between this and the 30-year rate has narrowed. This means the decision between a shorter, faster repayment with potentially lower interest overall and a longer, more flexible payment becomes a tougher calculation.
  • For the 5-Year ARM: The fact that the 5-year ARM rate stayed at 7.00% while fixed rates soared is interesting. It suggests that the market for ARMs might be a bit more stable or that lenders see them as less of a risk right now. However, at 7.00%, they're still quite expensive and offer less predictability than a fixed rate.

Putting It All Together: The Economic Picture

This isn't happening in a vacuum. The climb in mortgage rates is a symptom of tightening financial conditions. When bond yields go up, it’s usually because investors are demanding higher returns, often due to an expectation of higher inflation or a stronger economy that can handle higher borrowing costs. Lenders, in turn, pass these higher costs onto consumers in the form of higher mortgage rates.

This whole environment is a signal for borrowers to be cautious. Refinancing opportunities that seemed so generous just a few days ago are suddenly less appealing. Remember those multi-year lows we saw earlier in February? It feels like a distant memory now.

What This Means for You: Real-World Implications

I’ve been following the mortgage market for a while, and I can tell you that these kinds of sharp movements can throw a wrench into people’s financial plans. Here’s how today's rate changes might affect different homeowners:

  • Homeowners Considering Refinancing: If you were on the fence about refinancing, today’s jump is a big wake-up call. The potential savings you might have seen yesterday are significantly reduced, or even gone. My advice? Don't panic, but definitely keep a close eye on rates. You might need to be more patient or adjust your expectations. Locking in a rate is a big decision, and you want to do it when the market is more favorable.
  • Those Focused on Shorter Terms: The 15-year fixed rate at 5.99% is still a good option for those who can afford the higher monthly payments and want to build equity faster. However, the fact that it's closer to the 30-year rate means you need to really weigh the pros and cons carefully. Are you saving enough with the 15-year to justify the increased monthly cost?
  • Borrowers Opting for ARMs: While the 5-year ARM rate remaining at 7.00% offers some stability, it’s crucial to remember that this rate will eventually adjust. If you think rates might fall in five years, an ARM could pay off, but if they go up, your payments could skyrocket. Right now, with fixed rates also elevated, the predictability of a fixed-rate mortgage might be more appealing to some, even at a higher initial cost.

Beyond the Headlines: A Deeper Look at Refinance Trends

It's also important to look at the bigger picture of refinancing activity. Even with today's rate hike, refinance applications have been strong. Zillow data suggests that refinances currently make up a significant portion of mortgage applications, around 57.4%, which is up from earlier in February. And the Mortgage Bankers Association (MBA) reported a 7% rise in refinance applications just last week. This shows that despite fluctuations, many homeowners are still trying to take advantage of what they perceive as good opportunities, or perhaps are needing to access home equity.

Looking ahead to 2026, industry experts from TransUnion and the MBA are forecasting growth in refinance originations, but at a slower pace than we saw in 2025. This is logical. As the pool of homeowners with ultra-low rates from years past shrinks, the opportunities for massive savings through refinancing become fewer.

And that's the reality we're living in. While rates have dipped from their absolute highest points, persistent inflation and a strong job market mean that rates probably won't be plummeting below 6.0% for the 30-year fixed anytime soon, especially in this first quarter of 2026. Many homeowners are also getting creative, using Home Equity Lines of Credit (HELOCs) or home equity loans to tap into their home's value without losing their incredibly low primary mortgage rates, a strategy that makes a lot of sense for many.

Key Takeaways: Navigating Today's Mortgage Maze

So, to wrap it up, today, February 21, 2026, was a tough day for anyone looking to refinance their mortgage. The 30-year fixed refinance rate's sharp increase to 7.25% is a stark reminder that the market is dynamic and often unpredictable.

  • The 77-basis point jump in the 30-year fixed refinance rate is significant.
  • Other refinance options, like the 15-year fixed, also saw increases, though perhaps not as dramatic.
  • The 5-year ARM remained steady but at an elevated price point.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 20, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Mortgage Rates Drop to a 3-Year Low — Is Now the Best Time to Refinance?

February 20, 2026 by Marco Santarelli

Mortgage Rates Drop to a 3-Year Low — Is Now the Best Time to Refinance?

When you see headlines about mortgage rates hitting a multi-year low, it's a moment worth paying attention to, especially for homeowners. According to Freddie Mac, the average 30-year fixed mortgage rate has dipped to 6.01%, a mark we haven't seen since September 2022. This isn't just a small blip; it's a significant drop that's making a real difference for many. For many, this is the time to seriously consider refinancing.

Mortgage Rates Drop to a 3-Year Low — Is Now the Best Time to Refinance?

For months, we've been watching rates hover, sometimes inching up, sometimes taking small dips. But this recent slide, fueled by what looks like cooling inflation and a surprisingly strong jobs report, is significant. It's making it cheaper for people to borrow money to buy homes, and perhaps more importantly for us right now, it's making it cheaper for existing homeowners to adjust their current loans through refinancing. In fact, we're already seeing refinance activity more than double compared to this time last year, which tells you the market is buzzing.

But is it the right time for you? That's the million-dollar question, and unfortunately, there's no single “yes” or “no” answer that fits everyone. It really boils down to your own financial situation, what rate you currently have, and how long you plan on staying in your home. Let's break down what you need to consider.

Understanding Your Refinance Break-Even Point

Refinancing isn't free. There are always closing costs, which can add up. Think of it like buying a new pair of shoes – you want to make sure you wear them enough to get your money's worth. For refinancing, these costs typically fall somewhere between 2% and 6% of your loan amount. That might sound like a lot, but if you're saving a good chunk of money each month on your mortgage payment, those costs can be recouped.

The key is to figure out your break-even point. This is the number of months it will take for your monthly savings from the new loan to cover all the costs you paid to get that new loan.

You can calculate it with a simple formula:

Total Closing Costs ÷ Monthly Savings = Months to Break Even

As a general rule of thumb, and something I’ve seen ring true across many financial discussions, most experts agree that a payback period of 36 months (or less) is ideal. If it takes longer than three years to recoup your costs, you might be better off waiting for even lower rates or sticking with your current loan.

Finding That “Sweet Spot” Rate Drop

There was an old saying in the mortgage world: wait for rates to drop a full percentage point or even two before you even think about refinancing. While that might have been true with smaller loan amounts years ago, today’s mortgages are often much larger. This means even a smaller rate drop can make a big difference.

Here’s what I’m seeing as a good benchmark:

  • A 0.75% Drop: This is often considered the sweet spot. With a 0.75% decrease in your interest rate, most homeowners can reach their break-even point in under three years, which is fantastic.
  • A 0.50% Drop: Even a half-percentage point drop can be worthwhile, especially if you have a shorter loan term, like a 15-year mortgage, or if you can find a no-closing-cost refinance option. These options usually have a slightly higher interest rate, but they can still be beneficial due to the immediate savings.

Considering Your Specific Situation

Your personal circumstances are the most important factor. Let’s look at a few common scenarios:

  • Recent Buyers (2023-2024): If you bought a home in the last year or two, chances are you locked in a rate that was higher than today’s 6.01%. For those with rates above 7%, refinancing down to around 6% could mean serious monthly savings. We're talking roughly $334 per month on average for many homeowners who refinance from a 7% rate down to a 6% rate. That’s money back in your pocket for other goals or simply for some breathing room.
  • Removing PMI: Private Mortgage Insurance (PMI) is something many homeowners have to pay if they put down less than 20% when they bought their home. If your home's value has gone up since you purchased it, and you now have 20% equity, refinancing can be a great way to get rid of that monthly PMI payment. This alone can add anywhere from $100 to $200 to your monthly savings, on top of any rate reduction. It’s a win-win situation!
  • Long-Term Owners with Pandemic-Era Rates: Now, if you were one of the lucky ones who secured a mortgage during the pandemic, with a rate below 5% (maybe even under 4%!), refinancing now is likely not a good idea. In this case, refinancing to a 6.01% rate would actually increase your monthly payments. It’s important to know when to leave well enough alone.

What's Next for Mortgage Rates?

Predicting interest rates is like trying to predict the weather. However, based on current economic indicators and forecasts, the general consensus is that rates will likely continue to fluctuate within the 5.9% to 6.4% range throughout 2026. Some experts believe rates might even dip a little lower towards the end of the year.

The temptation to wait for the absolute lowest possible rate is always there. I get it. But there’s a risk in waiting too long. By waiting for a potentially small further drop, you could miss out on locking in substantial immediate savings that are available right now. The difference between 6.01% and, say, 5.9% might seem appealing, but the savings you could be accumulating for the next year while you wait might be more significant than that tiny future rate difference.

My advice? Do your homework. Run the numbers for your specific situation. Talk to a trusted mortgage professional. If refinancing can save you money each month and you can recoup your costs within a reasonable timeframe (ideally under three years), then this incredibly low rate environment might just be the opportunity you’ve been waiting for.

Build Wealth With Smart Real Estate Moves

The 1% refinance rule is back in focus for 2026, but real estate investors know that cash flow and appreciation often outweigh short‑term rate changes. Turnkey rentals remain a proven path to passive income regardless of mortgage shifts.

Norada Real Estate helps investors secure turnkey properties designed for immediate ROI and long‑term growth—so your portfolio thrives whether you refinance or stay the course.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Speak with an Investment Counselor Today (No Obligation):
(800) 611-3060
Or Request a Callback / Fill Out the Form Online

Contact Us

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Recommended Read:

  • Does the 1% Rule Say It’s Time to Refinance Your Mortgage in 2026?
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, Feb 20: Rates Hit Lowest in Over 3 Years, 30-Year Fixed Falls to 6.01%

February 20, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you've been watching the housing market, you'll be happy to know that as of February 20, 2026, mortgage rates have hit their lowest point in over three years, with the popular 30-year fixed rate dropping to an impressive 6.01%. This is fantastic news for anyone looking to buy a home or even refinance their existing mortgage. It means your monthly payments could be significantly lower than you might have expected, and it's a reflection of some positive economic shifts. This downward trend is a welcomed change, largely fueled by cooling inflation and a drop in longer-term Treasury yields.

Today’s Mortgage Rates, Feb 20: Rates Hit Lowest in Over 3 Years, 30-Year Fixed Falls to 6.01%

What Are Today's Mortgage Rates Saying?

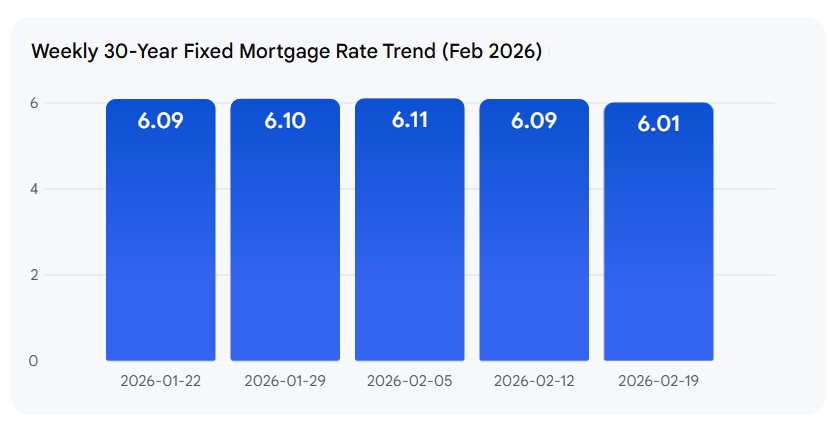
Let's break down what this means for you. According to Freddie Mac, the most common type of mortgage, the 30-year fixed-rate, saw its average fall to 6.01% for the week ending February 19th. That's down from 6.09% the week prior. For those considering a shorter loan term, the 15-year fixed-rate is looking even more attractive, dropping to 5.35% from 5.44% last week.

Weekly 30-Year Fixed Mortgage Rate Trend (Feb 2026)

Comparing this to last year, the difference is pretty striking. This time in 2025, the average for a 30-year fixed was around 6.85%. That means today's rates are nearly a full percentage point lower, saving you a substantial amount of money over the life of your loan.

Now, Zillow Home Loans also provides its own snapshots of national average mortgage rates, and their data for February 20, 2026, echoes this positive trend. It’s always good to compare different sources, and Zillow’s numbers reinforce that rates are trending downwards compared to the same time last year.

Here’s a look at Zillow’s data:

Loan Type Interest Rate APR
30-Year Fixed 5.875% 6.038%
20-Year Fixed 6.000% 6.202%
15-Year Fixed 5.375% 5.640%
10-Year Fixed 5.250% 5.660%
30-Year Jumbo 5.875% 6.054%
7/6 ARM 5.625% 6.164%

Specialty Loan Types also see benefits:

  • 30-Year FHA loans are averaging around 5.625% interest (6.306% APR).
  • For eligible military members, 30-Year VA loans are also at 5.625% interest (5.905% APR).

And for anyone looking to refinance, national averages for 30-year fixed refinances are holding steady, typically around 5.97%. This is a key takeaway – these lower rates aren't just for new buyers.

Why Is This Happening? The Economic Clues

It’s not magic; it’s economics at play. The primary driver behind this dip is the news on inflation. We’re seeing inflation cool down, which is exactly what the Federal Reserve watches closely. When inflation is in check, it reduces the pressure on the Fed to keep interest rates high.

Another significant factor is the slide in the 10-year Treasury yield. Mortgage rates often move in sync with these longer-term government bond yields. When yields on Treasury bonds fall, it generally signals lower borrowing costs for lenders, which they then pass on to consumers in the form of lower mortgage rates.

Mortgage Activity: A Refinance Rush and Eager Buyers

This change in rates isn't going unnoticed. The data shows a significant surge in refinancing applications. Last week alone, applications jumped by 7%, and the increase compared to a year ago is a staggering 132%. In fact, refinances now make up a hefty 57.4% of all mortgage applications. It’s clear that homeowners are recognizing these multi-year lows and are rushing to take advantage of potentially reducing their monthly payments or shortening their loan terms.

On the flip side, purchase applications have actually seen a slight dip of 3% last week. Now, don't let that discourage you. While lower rates are a huge draw, sometimes other factors can temper immediate buying enthusiasm. The persistent issue of limited housing supply in many areas and ongoing price pressures can still make finding the right home a challenge, even with more affordable financing.

However, there's a lot of optimism for the housing market in 2026. Many experts are predicting a real “thaw” in the housing market. They expect a significant increase in market fluidity, with sales volume potentially jumping by nearly 10% in certain regions. This is partly because the prolonged effect of the extremely low pandemic-era rates is starting to fade for some homeowners, making them more willing to sell and move.

What's Next for Mortgage Rates?

Looking ahead, the Federal Reserve's stance is crucial. They recently paused rate cuts in January after a series of reductions in late 2025. While more cuts are certainly possible later in 2026, many Fed officials are taking a wait-and-see approach, wanting to ensure inflation continues its downward path.

Interestingly, we've also seen some government intervention. Recent announcements about direct government purchases of mortgage-backed securities have helped in suppressing rates. This kind of action directly influences the availability and cost of mortgages.

So, what’s the forecast? Major agencies like Fannie Mae and the Mortgage Bankers Association are predicting that mortgage rates will remain relatively stable throughout much of 2026. They expect them to hover in the 6.0% to 6.3% range. This suggests that while we might not see drastic drops, the current lower levels could be here for a while, offering a consistent window of opportunity.

From my experience, these kinds of stable, lower rates are a sweet spot. They provide predictability for buyers and planners without the wild swings that can make financial decisions stressful. It’s a good time to get pre-approved and start exploring your options if homeownership or refinancing is on your mind.

Key Takeaways for Feb 20, 2026:

  • Rates are Low: The 30-year fixed-rate average is at a multi-year low of 6.01% (Freddy data).
  • Refi Boom: Homeowners are actively refinancing, with applications up significantly.
  • Buying Market Nuance: Purchase demand is a bit slower due to supply and price issues, but future market fluidity is expected.
  • Economic Drivers: Cooling inflation and lower Treasury yields are pushing rates down.
  • Outlook: Rates are expected to remain relatively stable in the 6.0%-6.3% range for most of 2026.

This is a moment to pay attention and act if it aligns with your financial goals. Whether you're dreaming of a new home or looking to improve your current mortgage, the current rate environment is a powerful ally.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 20: 30-Year Refinance Rate Drops by 10 Basis Points

February 20, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of today, February 20, 2026, homeowners looking to refinance certainly have a reason to feel a little more optimistic. The 30-year fixed refinance rate has dipped by 10 basis points, settling at 6.38%, offering a welcome, albeit modest, improvement for those seeking to lock in a long-term mortgage. This slight decrease, reported by Zillow, signals a continued effort to make borrowing more accessible for the long haul, even as other mortgage products hold steady.

This little downward tick today is a good reminder to keep an eye on what's happening, because opportunities to save money often sneak up on us.

Mortgage Rates Today, February 20: 30-Year Refinance Rate Drops by 10 Basis Points

What Does Today's Rate Movement Mean for You?

Let's break down what these numbers actually mean for us homeowners.

  • The 30-Year Fixed Refinance Rate at 6.38%: This is the headline news, and for good reason. A 10 basis point drop, while not earth-shattering, is a positive step. It means that if you've been thinking about refinancing your 30-year mortgage, the cost to do so just got a tiny bit cheaper. Over 30 years, even this small reduction can shave off a decent chunk of change from your total interest payments. It also means more predictability and peace of mind, as your monthly payment will remain the same for the entire life of the loan.
  • The 15-Year Fixed Refinance Rate Remains at 5.51%: This rate has held firm, which is great news for those who prefer to pay off their homes faster. A 15-year mortgage typically comes with a lower interest rate overall compared to a 30-year loan, and also means you build equity much quicker. If you're on this track, stability is a good thing, ensuring you can continue on your path to becoming mortgage-free sooner.
  • The 5-Year ARM Refinance Rate at 7.06%: It's interesting to see that adjustable-rate mortgages (ARMs) are still sitting at a higher rate. This highlights that while fixed rates are showing a slight improvement, ARMs are currently presenting a less attractive option for many. With ARMs, your rate is fixed for an initial period, and then it can (and often does) adjust based on market conditions, making it harder to budget for the long term. The current gap suggests that fixed-rate loans, especially the 30-year, are looking more appealing right now.

A Deeper Dive: Why Are Rates Shifting?

It's not just random chance that mortgage rates move. A lot of economic factors are at play, and understanding them can help us make smarter decisions. The data from Zillow tells us a couple of key things that are influencing these numbers.

First, there's been a significant surge in refinancing activity. You read that right – applications for refinancing have more than doubled over the past year compared to February 2025. We saw a 7% jump just in the week ending February 13th. This tells me that a lot of homeowners are actively seeking to lower their monthly payments, and this demand can actually influence the rates lenders offer. When more people are refinancing, lenders compete for that business.

What's really driving this “refi wave”?

  • Softer Economic Data: Reports on retail sales and home sales haven't been as robust as some predicted. When the economy cools a bit, it generally leads to lower interest rates because there's less demand for borrowing across the board.
  • Dropping Treasury Yields: Specifically, the 10-year Treasury yield, which is a major benchmark for mortgage rates, has been on the decline. Mortgage lenders often use these Treasury yields as a guide for setting their own rates.
  • Government Support: This is a big one that often doesn't get enough attention. Fannie Mae and Freddie Mac are stepping in by purchasing a substantial amount ($200 billion) of mortgage-backed securities. Think of this as injecting money into the system. By buying these securities, they help keep the market liquid and can encourage lenders to offer lower borrowing costs. It's a way the government tries to keep the housing market humming.

The “Golden Handcuffs” and Who Benefits Most

Here's something I've observed that really shapes the current market: the “golden handcuffs.” Many homeowners who secured mortgages during the ultra-low rate period of the pandemic (think rates below 4%) are hesitant to move or refinance. They're locked into incredibly cheap rates, and even if current rates are lower than the highs we saw last year, they might not be low enough to justify giving up their sub-4% deal. This means fewer homes are for sale, which tightens inventory.

So, who is actively refinancing?

It's primarily homeowners who took out mortgages in 2024 or early 2025, when rates were hovering closer to 7%. For these individuals, the current rates in the low 6% range represent significant potential savings. Refinancing now allows them to shave off valuable percentage points and reduce their monthly payments, and over the long term, that's a substantial financial win.

What Does This Mean for Your Mortgage Decision?

If you've been on the fence about refinancing, today's slight drop in the 30-year rate is a good cue to take a closer look.

  • Calculate Your Potential Savings: Even a 10 basis point drop can matter. Get a quote and see what your new monthly payment would be. Don't forget to factor in closing costs, but if the savings over a few years outweigh those costs, it might be worth it. My personal rule of thumb is if I can recoup my closing costs within, say, two to three years, it's usually a smart move.
  • Consider Your Goals: Are you looking for the lowest possible monthly payment for the long haul? The 30-year fixed at 6.38% is looking more attractive. Do you want to pay off your home faster and build equity quickly? The stable 15-year fixed at 5.51% remains the strong contender.
  • ARM Caution: Given that the 5-year ARM is still north of 7%, it seems prudent for most to stick with the predictability of a fixed-rate mortgage unless you have a very specific, short-term plan for the home and are comfortable with potential payment increases down the line.
  • Keep an Eye on the Future: While rates are showing some positive movement now, the economic future is never 100% certain. Experts are generally predicting rates to stay relatively low or even drift slightly lower for the rest of 2026, but unexpected events like inflation spikes tied to trade policies could always cause some turbulence.

The Bottom Line

Today, February 20, 2026, presents a potentially favorable environment for homeowners looking to refinance. The 6.38% rate for a 30-year fixed refinance offers a tangible opportunity to lower your monthly payments and save money over time. While other rates are holding steady, this modest decline in the long-term rate is worth exploring. It's a reminder that even small shifts in the market can create valuable opportunities to improve your financial situation. Don't miss out on doing your homework to see if refinancing makes sense for your specific circumstances.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 19, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, Feb 19: Rates Move Higher, 30-Year Fixed Rises by 11 Basis Points

February 19, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Mortgage rates edged slightly higher today on February 19, 2026, reflecting cautious adjustments in the lending environment. According to Zillow, the 30‑year fixed mortgage rate rose 11 basis points to 5.89%, while the 15‑year fixed rate increased 4 basis points to 5.38%. Despite these upticks, the 30‑year loan remains near a three‑year low, offering borrowers continued access to historically favorable terms. Let me walk you through what these numbers mean, drawing insights from the latest data.

Today’s Mortgage Rates, February 19: Rates Move Higher, 30-Year Fixed Rises by 11 Basis Points

What the Numbers Are Saying Today

So, let's break down the core figures from Zillow. On February 19, 2026, here’s where we stand:

  • The 30-year fixed mortgage rate is sitting at 5.89%. This is up 11 basis points, which is a small tick up. What's great is that this is still very close to a three-year low, meaning affordability for many is still quite good.
  • The 15-year fixed rate is at 5.38%. This one saw a smaller increase, just 4 basis points. This is always a popular option for those who want to build equity faster and pay less interest over the life of the loan.

Your Mortgage Rate Options on February 19, 2026 (According to Zillow)

It's always helpful to see all the options laid out. Here’s a simple table showing the rates we're looking at today:

Loan Type Interest Rate
30-year fixed 5.89%
20-year fixed 5.79%
15-year fixed 5.38%
5/1 ARM 5.99%
7/1 ARM 5.79%
30-year VA 5.38%
15-year VA 5.08%
5/1 VA 4.98%

Note: Rates can vary based on your individual creditworthiness, down payment, and other factors. This table provides a general overview.

Digging Deeper: What These Rates Mean for You

Seeing the numbers is one thing, but understanding the why and the impact is where the real value lies. Based on my experience in this field, these small shifts are often driven by a few key economic players.

  • The 30-Year Fixed at 5.89%: This is the workhorse of the mortgage world. For most borrowers, this rate offers a good balance of a manageable monthly payment and a fixed rate that won't change for the entire life of the loan. The fact that it's hovering near a multi-year low means that while it ticked up today, it’s still significantly better than what many borrowers have seen in the past decade. This stability is a huge win for long-term financial planning.
  • The 15-Year Fixed at 5.38%: If you're looking to become mortgage-free faster or have the financial flexibility to handle slightly higher monthly payments, the 15-year fixed is a fantastic choice. You'll pay substantially less interest over time compared to a 30-year loan. The small increase here doesn't diminish its appeal for those prioritizing rapid equity building.
  • Adjustable-Rate Mortgages (ARMs): You'll notice the 5/1 ARM at 5.99% and the 7/1 ARM at 5.79% are slightly higher than their fixed-rate counterparts currently. Traditionally, ARMs offer a lower introductory rate, but with fixed rates this competitive, the immediate savings on an ARM might not be as compelling unless you have a very specific, short-term plan for the property. It's a good reminder that the perceived “deal” on an ARM needs careful consideration of future rate hikes.
  • VA Loans: A Real Deal for Our Heroes: I'm always impressed by the rates offered to our veterans and service members through VA loans. The 5/1 VA ARM at a remarkable 4.98% is a testament to the value placed on those who serve. These loans continue to be incredibly competitive, often with no down payment required and a significantly lower interest rate. It's a genuine benefit worth exploring if you qualify.

The Economic Pulse Behind Today's Rates

Why did rates nudge up today? It's rarely just one thing. Think of it like a complex recipe: a pinch of this, a dash of that.

  • Federal Reserve's Careful Steps: The minutes released yesterday (February 18, 2026) from the January Federal Open Market Committee (FOMC) meeting were telling. The message from the Fed officials was clear: they're not in a hurry to start cutting their key interest rates. Some even mentioned the possibility of raising rates again if inflation doesn't cool down as expected. This cautious stance from the central bank naturally makes markets a bit more reserved, which can put upward pressure on borrowing costs like mortgages.
  • A Stronger Job Market: While we're all hoping for lower rates, the economy is showing some resilience. The unemployment rate holding steady at a rather low 4.3% in January is a sign of a healthy job market. When more people are employed and earning, the economy is seen as more robust, which can lead investors to demand slightly higher returns on their investments, including mortgage-backed securities. This is why we aren't seeing rates plummet as some might have hoped.
  • Refinancing is Still Hot (Relatively): Even though rates went up a little today, they are still significantly lower than the 6.9% we saw in early 2025. This gap means many homeowners who locked in higher rates last year are still finding it very beneficial to refinance. This consistent demand for refinancing helps keep the mortgage market active.
  • Treasury Yields: The Barometer: The 10-year Treasury yield is like the weather forecast for mortgage rates. It rose slightly to 4.095% after the Fed's cautious remarks. Since mortgage rates generally follow the direction of Treasury yields, this uptick in the bond market contributed to the slight increase in mortgage rates we're seeing today.

What This Means for You and Your Homeownership Dreams

So, is today a good day to buy or refinance? My honest opinion is: yes, for many.

  • For Homebuyers: The slight increase doesn't erase the fact that rates are historically low. You're still getting excellent purchasing power. This means your monthly payments are manageable, and you can potentially afford a slightly larger home or a more desirable location than you might have anticipated a year or two ago. It’s a great time to lock in a rate that offers long-term financial comfort.
  • For Refinancers: If you have a mortgage from before rates started their recent decline, you are likely sitting on a goldmine of savings. Even with the small uptick today, the difference between your current rate and today's rates could translate into thousands saved over the life of your loan.

It’s crucial to get personalized quotes, of course, but the overall picture is still very encouraging.

Wrapping Up Today's Mortgage Rate Picture

February 19, 2026, presents a mortgage market that is showing slight upward movement, with the 30-year fixed rate at 5.89% and the 15-year fixed at 5.38%. However, the narrative is one of continued opportunity. These rates are largely holding near multi-year lows, offering a golden window for both new homebuyers and those looking to improve their current mortgage terms. My takeaway is that while the market is always dynamic, today's rates provide a solid foundation for achieving your homeownership goals with confidence and long-term financial benefit.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

  • « Previous Page
  • 1
  • …
  • 48
  • 49
  • 50
  • 51
  • 52
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...