Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Mortgage Rates Today, February 19: 30-Year Refinance Rate Drops by 15 Basis Points

February 19, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

If you've been thinking about refinancing your home, today, February 19, 2026, might be a great day to seriously consider it. The national average 30‑year fixed refinance rate has dropped to 6.33%, according to Zillow. That's a noticeable dip – down 9 basis points from yesterday and a significant 15 basis points lower than the average we saw last week. This move is making longer-term, fixed-rate mortgages more attractive for homeowners looking to save some money.

Mortgage Rates Today, February 19: 30-Year Refinance Rate Drops by 15 Basis Points

What's Happening with Refinance Rates Right Now?

It's always a bit of a mixed bag in the mortgage world, and today is no exception. While the big news is the drop in the 30-year fixed rate, other loan types are doing something different.

Here's a quick look at the numbers as of February 19, 2026, from Zillow:

Loan Type Rate Change from Previous Day Change from Last Week
30-Year Fixed Refi 6.33% Down 9 basis points Down 15 basis points
15-Year Fixed Refi 5.58% Up 9 basis points Up 9 basis points
5-Year ARM Refi 7.03% Up 7 basis points Up 7 basis points

As you can see, the 15‑year fixed refinance rate nudged up to 5.58%, and the 5‑year adjustable-rate mortgage (ARM) refinance rate also climbed slightly to 7.03%. This tells me that while longer-term stability is becoming more affordable, lenders might be a bit more cautious about shorter-term borrowing.

Digging Deeper: Market Insights and What It Means for You

This drop of 15 basis points (which is 0.15%) in the 30-year fixed rate is more than just a number; it's genuinely good news for homeowners. In my experience, seeing the long-term rate move like this often signals a moment when refinancing makes real financial sense.

  • The 30-Year Fixed: At 6.33%, this rate is looking much more appealing than it did just a week ago. It offers that peace of mind that your monthly payment won't change for the next 30 years, and now it comes with a lower price tag.
  • The 15-Year Fixed: Even though it went up a bit, 5.58% is still a fantastic rate if you're looking to pay off your home faster. Your monthly payments will be higher than a 30-year loan, but you'll save a ton on interest over the life of the mortgage.
  • The 5-Year ARM: The rise to 7.03% is a good reminder that ARMs can be much more unpredictable. You might get a lower rate to start, but you have to be ready for that rate to go up later. With the current rates, the stability of a fixed loan seems like a much safer bet for most people right now.

Why Are Rates Moving? Looking at the Bigger Economic Picture

These shifts in mortgage rates don't happen in a vacuum. They're tied to what's happening in the broader economy. Right now, we're seeing Treasury yields soften. When investors feel a bit uneasy about the economy, they often flock to safer investments like U.S. Treasury bonds. This increased demand drives up bond prices and, as a result, pushes down their yields. Since mortgage rates tend to follow these Treasury yields, that's why we're seeing borrowing costs ease up.

On the flip side, lenders are pushing shorter-term rates up. This could be their way of saying they're a bit concerned about inflation or future interest rate hikes, so they're pricing those adjustable products to reflect that caution. It's a balancing act the market is constantly performing.

How Much Can a 15 Basis Point Drop Actually Save You?

Some people might look at a 15 basis point drop and think, “That's not much.” But trust me, over the long haul of a mortgage, it adds up significantly. Let's break it down with a realistic example:

Imagine you have a $300,000 mortgage balance.

  • If your rate drops by 0.15%, your monthly payment could decrease by about $25 to $30.
  • Now, think about that savings over 30 years. That's roughly $9,000 to $10,800 you'd be keeping in your pocket instead of paying it all to the bank in interest.

That kind of money can make a real difference, whether it's for saving for a down payment on another property, investing, or just having a little extra breathing room in your budget.

A Surge in Refinancing Activity Last Week

It's not just me seeing this opportunity. Zillow's data also shows that mortgage refinance applications exploded last week. They climbed 7% compared to the week before and were a whopping 132% higher than they were at this time last year.

  • Refinancing is Dominating: Last week, a significant 57.4% of all mortgage applications were for refinancing. That's up from the previous week's 56.4%. This shows that tons of homeowners who locked in higher rates (think above 7%) in late 2024 or early 2025 are now jumping at the chance to get into this lower, sub-6.2% environment.
  • Millions Have Good Reason to Refi: Zillow estimates that about 4.8 million homeowners are in a position to lower their monthly payments by refinancing right now. That's the highest number of eligible homeowners we've seen since early 2022!
  • Why the Purchase Market is Slow: Interestingly, even with all this refinancing excitement, the market for buying new homes is still a bit sluggish. A lot of existing homeowners are happy where they are with their super-low mortgage rates from years past (like under 4%) and are hesitant to sell. This “locked-in” feeling contributes to the tight housing inventory we're all seeing.

What's Next? Expert Predictions for Mortgage Rates

Looking ahead, experts from Fannie Mae and the Mortgage Bankers Association (MBA) have some thoughts. They generally expect mortgage rates to hang around 6.0% through the rest of 2026. While there's always a chance the Federal Reserve could make more interest rate cuts later in the year that could push rates even lower, their current focus seems to be on letting the earlier cuts settle in before making any big new moves.

What This Means for You as a Borrower

So, what should you take away from all this?

  • If You're Thinking About Refinancing: The drop in the 30-year fixed refinance rate to 6.33% is a clear signal. It's a great time to get a lower monthly payment and lock in long-term savings. Don't wait too long to explore your options!
  • If You Prefer Shorter Terms: While the 15-year fixed rate increased slightly, it's still a very competitive rate. If you have the financial ability, it remains an excellent way to cut down the total interest you pay.
  • If You're Considering an ARM: The rise in 5-year ARM rates really highlights the risks involved. You need to be very comfortable with your budget and have a solid plan for how you'll handle potentially higher payments down the road.

My Take: Today's Refinance Rates Are a Good Opportunity

To wrap it up, the mortgage refinance rates we're seeing today, February 19, 2026, show a pretty borrower-friendly market. The 30-year fixed refinance rate hitting 6.33% is the headline grabber, and for good reason. Even though some shorter-term loans are seeing minor increases, the clear drop in those long-term rates makes refinancing a really smart move for many homeowners. Remember that even a small change like 15 basis points can save you a significant amount of money over the years. If you're looking for more financial stability and affordability in your homeownership journey, now looks like a solid time to explore your refinancing options.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 18, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, February 18: 30-Year Fixed Rate Drops Below 5.8%

February 18, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

It's a really fantastic day for anyone thinking about buying a home or looking to lower their monthly payments – today, February 18, 2026, we're seeing some of the most attractive mortgage rates in quite some time, with the average 30-year fixed rate dipping to a very appealing 5.79%. This is welcome news for both new buyers and existing homeowners.

The big driver behind this pleasant change is a significant drop in the 10-year Treasury yield, which has shed nearly 2% just in the past week. Think of it this way: when investors get a little nervous about the stock market, they often pour their money into safer government bonds. This increased demand drives bond prices up and, in turn, their yields – which are what mortgage rates tend to follow – down.

Today’s Mortgage Rates, February 18: 30-Year Fixed Rate Drops Below 5.8%

Zillow’s latest numbers really show this trend clearly, with averages hitting lows we haven't seen in years:

Loan Type Average Rate
30-year fixed 5.79%
20-year fixed 5.71%
15-year fixed 5.34%
5/1 ARM 5.90%
7/1 ARM 5.69%
30-year VA 5.44%
15-year VA 5.06%
5/1 VA ARM 5.14%

Digging Deeper: What’s Behind These Numbers?

That 5.79% for a 30-year fixed mortgage is a real standout. For anyone looking for that predictable, stable monthly payment over the long haul, this rate is a significant plus. It means more buying power or just a more comfortable payment each month for the same loan amount.

If you're someone who likes to pay off your home faster and save on total interest, the 15-year fixed rate at 5.34% is looking incredibly strong. It’s a great way to build equity quicker. Now, adjustable-rate mortgages (ARMs), like the 5/1 ARM at 5.90% and the 7/1 ARM at 5.69%, are still a bit higher. This often happens because lenders are a little more cautious with shorter-term products, and they price that uncertainty in.

And I have to give a special mention to our veterans and service members. The VA loan products are truly shining right now. With a 15-year VA fixed at 5.06% and a 5/1 VA ARM at 5.14%, these are some of the most competitive rates out there, plain and simple. It’s great to see such favorable terms available for those who have served.

Why Do Rates Change So Much?

It's always a bit of a head-scratcher for people: why do mortgage rates jump around, sometimes even multiple times a day? From my experience, the biggest reason is that mortgage rates are directly linked to what’s happening in real financial markets, specifically mortgage-backed securities (MBS). Just like company stocks, these are packages of mortgages that investors trade. When new economic news comes out, investors adjust their prices, and that change ripples out to what lenders offer you.

Here are the main things that cause these daily shifts:

  1. The 10-Year Treasury Yield: This is probably the biggest influencer. Think of it as a close cousin to mortgage rates. When the 10-year Treasury yield goes up, mortgage rates tend to follow suit, and vice versa. Investors want a similar return for the risk they’re taking between a government bond and a mortgage.
  2. Inflation Reports: When inflation is high, it eats away at the future value of the interest lenders earn. So, higher inflation often means higher mortgage rates as lenders try to protect their profits.
  3. Federal Reserve Actions (and Hints): While the Fed doesn't directly set mortgage rates, their actions with the federal funds rate influence how much it costs banks to borrow money. Even whispers and expectations about what the Fed might do can move rates before any official announcement.
  4. Economic Data (Jobs, GDP): Reports on how the economy is doing, like how many jobs were added or how much the country grew (GDP), can cause markets to react. A super-strong economy might signal future inflation, leading to higher rates. A weaker report might send investors looking for the safety of bonds, pushing rates down.
  5. Investor Mood and Global Events: When there’s trouble in the world – think geopolitical tensions or financial crises – investors often flock to the perceived safety of U.S. Treasury bonds. This demand pushes bond prices up and yields down, which usually means lower mortgage rates.

Because of all this movement, most lenders offer something called a “rate lock.” This is a crucial tool that protects you from any rate increases while your loan application is being processed. It’s something I always advise my clients to consider.

Market Insights and Trends: What I'm Seeing

After a few rate cuts late last year, the Federal Reserve has taken a bit of a “wait-and-see” approach. However, that surprisingly strong January jobs report – with over 130,000 new jobs – has some folks thinking the Fed might hold off on any more cuts at their mid-March meeting.

On the housing front, with rates now at these lower levels, we're starting to see more people applying to buy homes compared to last year. That’s a good sign for market activity.

However, there’s a bit of a quirk in the market known as the “lock-in effect.” Even though rates have come down, a huge number of homeowners – I’m talking around 82.8% – still have mortgages with rates below 6%. This makes them hesitant to sell and move because they’d likely have to take on a new, higher-rate mortgage. This is keeping the number of homes for sale limited.

Looking ahead, most of the big real estate economists, including those at Fannie Mae and the Mortgage Bankers Association, are predicting that the 30-year fixed rate will stay pretty steady for the rest of 2026, likely hovering between 6.0% and 6.3%. So, the current lower rates might be a window of opportunity.

What This Means for You

  • For Homebuyers: Lower rates mean you can either afford a bit more house or significantly reduce your monthly payments. It’s all about making that dream of homeownership more attainable.
  • For Refinancers: If you've had your mortgage for a while and have a higher rate, now is definitely the time to explore refinancing. Locking in these lower rates could save you a substantial amount of money over the life of your loan.
  • For Veterans and Service Members: As I mentioned, the VA loan programs are really offering some of the best deals out there right now. If you qualify, definitely take a close look.

The key takeaways for today

February 18, 2026, feels like a significant point in the mortgage market. Rates are holding steady, and importantly, they’re trending lower. That 30-year fixed rate at 5.79% and the 15-year fixed at 5.34% are creating a very favorable environment for borrowers – the kind we haven’t seen in a good long while. Whether you’re looking to buy your first home or refinance your current one, today’s rates offer a genuine opportunity to lock in long-term savings and build financial security.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 18: 30-Year Refinance Rate Drops by 12 Basis Points

February 18, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

It’s February 18, 2026, and if you’re a homeowner thinking about refinancing, I’ve got some potentially good news for you. The national average 30-year fixed refinance rate has dipped by a noticeable 12 basis points, bringing it down to 6.36%. This little swing might not sound like much on paper, but when you’re talking about home loans, it can add up to significant savings over the life of your mortgage.

As of today, February 18, 2026, the national average 30-year fixed refinance rate is sitting pretty at 6.36%. This is a welcome change from the 6.48% we saw just last week. This information comes straight from Zillow, a source I’ve come to trust for keeping a pulse on the housing market.

Mortgage Rates Today, February 18, 2026: 30-Year Refinance Rate Drops by 12 Basis Points

Let’s take a quick look at what the other refinance options are doing:

Mortgage Product Rate (February 18, 2026) Change from Last Week
30-Year Fixed Refi 6.36% -12 basis points
15-Year Fixed Refi 5.42% Stable
5-Year ARM Refi 6.84% Stable

Why This Rate Drop Matters to You

Seeing that 30-year fixed refinance rate move down isn't just a number; it’s a signal. In my experience, these kinds of shifts, even if they seem small, can be the catalyst for a lot of homeowners to finally pull the trigger on refinancing.

  • The 30-Year Stability: At 6.36%, this is still the bedrock for many homeowners looking for long-term predictability. Locking in a slightly lower rate here means a lower monthly payment for the next three decades, which is a big deal, especially if you plan to stay in your home for a while.
  • The 15-Year Advantage: The 15-year fixed refinance rate is holding steady at 5.42%. This is a fantastic option if you can swing the higher monthly payments. You build equity twice as fast and save a ton on interest over the loan’s life. It’s a commitment, for sure, but the financial rewards are substantial.
  • Adjustable Rates – A Word of Caution: The 5-year ARM refinance rate at 6.84% is still quite a bit higher than the fixed rates. This tells me that lenders are pricing in the risk associated with rates potentially going up in the future. While ARMs can be attractive if you plan to move or refinance again before the fixed period ends, right now, the stability of a fixed rate seems to be the more sensible choice for most.

Digging Deeper: What's Driving These Numbers?

You don’t just wake up and have mortgage rates change without a reason. A few key things are nudging these numbers around, and it’s worth understanding them to see where we might be headed.

One of the biggest pieces of news is that a significant number of homeowners are now in a prime position to refinance. Zillow’s data suggests that nearly 5 million homeowners are currently “in the money,” meaning they can likely get a better deal by refinancing than what they're paying now. This has been a jump of about 20% in eligible borrowers since the start of January, thanks to rates inching closer to that 6% mark. It's a great sign that the market is becoming more accessible to people.

What’s causing this shift? Well, a couple of major economic forces are at play. First, we’ve seen a recent dip in 10-year Treasury yields. When Treasury yields go down, it generally makes it cheaper for lenders to borrow money, and they pass those savings on in the form of lower mortgage rates. Think of it like wholesale prices for money dropping.

On top of that, there’s been a bit of wobble in the stock market. When stocks get a bit shaky, investors often move their money into safer assets, like government bonds, which can also push Treasury yields lower. It’s a classic “flight to safety” scenario.

Adding a bit more pressure downwards on mortgage rates is a federal directive. Fannie Mae and Freddie Mac, which are government-sponsored enterprises that play a big role in the mortgage market, have been directed to purchase $200 billion in mortgage-backed securities. This essentially injects more money into the mortgage market, making it easier for lenders to offer lower rates. It’s a deliberate move to keep borrowing costs down.

The Federal Reserve and Inflation: Keeping an Eye on Things

Now, let’s talk about the big boss: the Federal Reserve. They are super important because their decisions on interest rates ripple through the entire economy. The Fed held its interest rates steady at their meeting on January 28th. This was a pause after a series of rate cuts, and they're watching inflation closely. Right now, inflation is sitting at 2.7%. They need to make sure it's heading towards their target before they start cutting rates aggressively again.

The next big meeting for the Federal Open Market Committee (FOMC) is scheduled for March 17–18, 2026. This meeting is crucial because whatever they decide there will likely set the tone for major interest rate movements for the rest of the year. We’re all watching to see if they’ll continue pausing or start another round of cuts.

Looking Ahead: 2026 Forecasts

So, what does all this mean for the rest of 2026? The smart money, including folks at Fannie Mae, are predicting that mortgage rates will likely stay around the 6.0% mark for the remainder of the year. That’s pretty stable, and a good neighborhood to be in if you're looking to refinance.

And if you want to get even more specific, some big names like Morgan Stanley are forecasting that rates could even end the year at a low of 5.75%. This is optimistic, of course, and relies on the Fed continuing to manage inflation successfully.

The Economic Picture: A Balanced Act

The fact that we’re seeing mortgage rates ease back a bit, driven by lower Treasury yields and a more controlled inflation outlook, suggests a certain level of confidence in the broader economy. Lenders aren’t panicked; they’re adjusting cautiously. They’re offering these slightly better rates because the underlying conditions support it, but they’re also not doing anything that would inject unnecessary volatility into the market. It’s a delicate balance they’re trying to strike.

What This Means for You, the Homeowner

So, how do you, as a homeowner, use this information?

  • Considering a Refi? Now's the Time to Check: That 12 basis point drop in the 30-year fixed rate might seem like a small number, but when you do the math on your loan amount, it can translate into some serious monthly savings. If you’ve got a larger mortgage, these savings could be hundreds of dollars a month. Don’t just assume it’s not worth it; run the numbers!
  • Short-Term Savings vs. Long-Term Goals: The 15-year fixed rate holding steady means it’s still an excellent option for those who want to pay off their home sooner and save big on interest in the long run. If you can handle the higher monthly payments, this is often the smartest financial move you can make.
  • ARM Logic: The fact that ARM rates are still higher than fixed rates is a clear signal. It’s telling you that taking on the uncertain future of adjustable rates comes at a premium right now. Weigh the risks very carefully if you’re even thinking about an ARM. For most people, the peace of mind from a fixed rate is worth it.

The Bottom Line on Today’s Refinance Rates

To wrap it all up, mortgage refinance rates on this February 18, 2026, are giving homeowners a bit of a breather. The headline today is that the 30-year fixed refinance rate has dropped to 6.36%. While it’s not a dramatic plunge, it’s a definite movement in your favor. This stability in the fixed-rate options, contrasted with the higher rates on ARMs, really highlights the value of locking in a predictable payment. For anyone looking to lower their monthly costs or simply gain more financial certainty, now is a prime time to explore your refinancing options and potentially lock in some valuable savings for the future.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 17, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, February 17: Rates See Persistent Stability Near 3-Year Lows

February 17, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of today, February 17, 2026, mortgage rates are holding remarkably steady, sitting near their lowest points in three years, offering a welcome period of calm in what can often be a turbulent housing market. It feels like just yesterday we were watching mortgage rates swing up and down with every economic report. But right now, something really interesting is happening.

According to Zillow's latest data, the average 30-year fixed mortgage rate is sitting comfortably at 5.85%, and the 15-year fixed rate is a very attractive 5.36%. This stability is a direct result of the Federal Reserve's decisions to lower rates in late 2025. Even though they didn't change rates at their first meeting of 2026, the groundwork has been laid for this calm. It's a rare chance for us to get a good deal on a home loan.

Today’s Mortgage Rates, February 17: Rates See Persistent Stability Near 3-Year Lows

A Snapshot of Current Mortgage Rates

To give you a clear picture, here’s what the numbers look like today:

Loan Type Average Rate
30-year fixed 5.85%
20-year fixed 5.64%
15-year fixed 5.36%
5/1 ARM 5.81%
7/1 ARM 5.71%
30-year VA 5.36%
15-year VA 5.15%
5/1 VA 4.99%

What's Making These Rates So Stable?

What’s truly remarkable about February 17, 2026, isn't just that the rates are low, but that they've stayed put. We haven't seen the wild swings that usually happen when economic news comes out or when Treasury yields jump around. It's like the market has found its happy place, at least for now.

Let's break down some of the key options:

  • The 30-year fixed at 5.85%: This is still the go-to for many people who want predictable monthly payments and the security of knowing their rate won't change over the lifespan of the loan. It's a solid choice, especially with this rate.
  • The 15-year fixed at 5.36%: If you want to build equity faster and pay less interest overall, this is a fantastic option. You'll have higher monthly payments than a 30-year loan, but you'll be mortgage-free sooner.
  • VA Loans: I have to give a special shout-out to VA loans. With the 5/1 VA ARM coming in at a stunning 4.99%, these are incredibly competitive. If you're a veteran or active-duty service member, this is a golden opportunity to refinance or buy your dream home.

The Bigger Economic Picture

So, why are rates behaving so nicely? A few things are at play. Inflation has been cooling down – the Consumer Price Index (CPI) in January dropped to 2.4%, which is great news. Plus, the Federal Reserve wrapped up its plan to shrink its balance sheet (quantitative tightening) back in December 2025. These two factors have put downward pressure on mortgage rates. However, the job market is still pretty strong, which might be preventing rates from dropping even further.

Because of these lower rates, we're seeing a big jump in people wanting to refinance. Zillow reports that refinance applications are up by over 100% compared to last year! Many homeowners who took out loans at rates above 7% in early 2025 are now jumping at the chance to lower their monthly bills.

Looking ahead, most of the smart people at places like Fannie Mae and the Mortgage Bankers Association believe that 30-year mortgage rates will likely stay pretty consistent through the rest of 2026, probably hovering somewhere between 5.9% and 6.3%. This prediction is based on the current economic conditions and the Fed's likely path.

Why This Environment is a Win for Borrowers

This steady, lower-rate environment is a real game-changer for anyone looking to get into a home or improve their current mortgage situation.

  • For Homebuyers: When rates are lower, it means you can afford more house for your money, or you can keep your monthly payments more manageable. This improves affordability significantly.
  • For Refinancers: If you have a mortgage from a year or two ago with a higher interest rate, now is the time to seriously consider refinancing. You could be saving a good chunk of money every month.
  • For Our Veterans and Service Members: As I mentioned, VA loans are offering some of the absolute best rates out there. It’s definitely worth exploring if you qualify.

It's Not Just About the National Average: What Affects YOUR Rate

While these national averages are fantastic, it’s important to remember that the rate you actually get will depend on several personal factors. Think of the national average as the starting point for the conversation.

Here’s what lenders will look at:

  • Your Credit Score: Generally, if you have a credit score of 740 or higher, you’ll be in the best position to grab the lowest advertised rates. A good credit score shows lenders you're a reliable borrower.
  • Loan-to-Value (LTV) Ratio: This is the ratio of how much you owe on the loan compared to the value of the home. If you can put down a larger down payment – say, 20% or more, which means a lower LTV – lenders often see that as less risk and can offer you a better interest rate.
  • Shopping Around is Key: This is a tip I can't emphasize enough! Freddie Mac research has shown that by getting quotes from multiple lenders, you could potentially save between $600 and $1,200 per year on your mortgage payments. Don't just go with the first lender you talk to. Compare offers from banks, credit unions, and online lenders.

Key Takeaways on Today's Market and Rates

As someone who follows the housing market closely, I find this period on February 17, 2026, quite refreshing. We've moved past the steep rate hikes, and rather than seeing rates bounce wildly, they've settled into a much more predictable and borrower-friendly range. The 30-year fixed at 5.85% and the 15-year fixed at 5.36% are rates that many people only dreamed of a few years ago.

Whether you're aiming to buy your first home or looking to make your current mortgage work better for you, today's stable and relatively low rates present a wonderful opportunity. It’s a reminder that sometimes, patience in the market pays off, and when those good times arrive, it’s smart to act strategically to make the most of them.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 17: 30-Year Refinance Rate Drops by 1 Basis Point

February 17, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of February 17, 2026, the national average 30-year fixed refinance rate has nudged down to 6.47%, a modest but welcome decrease of just one basis point from last week's average, according to data from Zillow. This slight dip signifies a moment of stabilization in the refinancing market, offering a sliver of an opportunity for homeowners to potentially improve their mortgage terms. Today’s figures, while not a dramatic plunge, certainly give us something to talk about.

Mortgage Rates Today – February 17, 2026: 30-Year Refinance Rate Drops by 1 Basis Point

What the Numbers Mean for You Right Now

You might be wondering if a one-basis-point drop is even worth considering. For the average homeowner, that tiny shift might not immediately free up tons of cash each month. However, in the world of mortgages, even small decreases can add up, especially over the many years a mortgage loan lasts. My take on it is this: it’s a signal that the market isn't suddenly jumping ship on lower rates. Instead, it's suggesting a period of careful observation and perhaps a good time to see if you qualify for anything better.

Here’s a quick look at where things stand today, according to Zillow:

Mortgage Product Average Rate (February 17, 2026) Change from Last Week
30-Year Fixed Refinance 6.47% ↓ 1 Basis Point
15-Year Fixed Refinance 5.44% Stable
5-Year ARM Refinance 7.01% Stable

As you can see, the longer-term fixed mortgage is the one showing that slight movement. The 15-year fixed rate is holding firm, which is great for those looking to pay off their home faster. The 5-year Adjustable Rate Mortgage (ARM), however, continues to stay higher. This is pretty typical when we see any uncertainty or upward pressure on short-term borrowing costs. Lenders are generally more cautious with ARMs in these situations because the risk of rates jumping is higher.

Digging Deeper: Why the Stability, and What's Next?

It’s important to understand that mortgage rates don’t just move on their own. They’re influenced by a whole bunch of factors, kind of like a complex recipe. The Federal Reserve’s actions, inflation numbers, and how many people are looking to borrow all play a role.

Last month, on January 28th, the Federal Reserve met and decided to keep the federal funds rate steady. They're seeing inflation cool down, which is good news, but the job market is still surprisingly strong. In January alone, about 130,000 jobs were added. Because of this strong job growth, it’s pretty unlikely we’ll see a rate cut at their next meeting on March 17th. This steady hand from the Fed contributes to the stability we're seeing in mortgage rates right now.

And speaking of borrowing, guess what? Refinance applications actually shot up by 20% in late January when rates hit their lowest point since late 2024. That tells me a lot of homeowners like you are paying attention and are ready to pounce when they see an opportunity. Industry folks are calling this “refinance index” up by more than double what it was at this time last year! It just goes to show, when rates dip even a little, people take notice and act.

Looking ahead, analysts from big names like Fannie Mae and the Mortgage Bankers Association (MBA) are predicting that rates will likely stay in the 6.0% to 6.1% range for the rest of 2026. That's optimistic, and it suggests that while today’s rate of 6.47% isn't the absolute bottom, it’s definitely within a favorable zone for many.

When Your Existing Rate is Already Low: What Are Your Options?

Now, I know what some of you might be thinking: “My current mortgage rate is fantastic, something like sub-4%! Why would I even think about refinancing?” That’s a great position to be in! If you're one of the lucky ones with a super-low rate, refinancing your primary mortgage might not make sense.

But what if you need access to cash for home improvements, to pay for education, or for any other big expense? This is where alternatives to a cash-out refinance become really valuable. Today, the average rate for a Home Equity Line of Credit (HELOC) is 7.23%, and a home equity loan is 7.44%. While these are higher than today’s refinance rates, they come with their own set of advantages, like potentially keeping your excellent primary mortgage rate intact. It’s really about weighing the costs and benefits for your specific situation.

What This Means for Your Pocketbook and Your Future Plans

So, if you're thinking about refinancing, what's the takeaway from today's news?

  • For Homeowners Considering Refinancing: That 30-year fixed rate nudging down to 6.47% is a gentle reminder that while we aren’t seeing dramatic drops, the chance to lock in a stable, potentially lower rate is still present. It might be the perfect time to compare offers and see if you can snag a better deal on your home loan.
  • For Those on ARMs: The fact that ARMs remain higher at 7.01% is a good reason to be extra cautious. If you're on an ARM now, or considering one, it’s crucial to understand the risks involved. That rate can go up, and those monthly payments can become a lot larger than you initially planned.
  • For Savvy Savers: Even these small basis point changes matter. If you’re a borrower who’s always looking at the long game, keeping an eye on these trends and understanding when to act can save you a significant amount of money over the life of your loan.

My Two Cents: Is Today a Good Day to Refinance?

From my perspective, today’s slight dip isn't a screaming buy signal, but it's a definite “look and see” opportunity. Many homeowners took out loans when rates were above 7% in late 2024 and early 2025. For those individuals, reaching a rate below 6.5% truly opens up a path to savings.

When you’re thinking about refinancing, it’s not just about the rate. You need to look at the whole picture. What are the closing costs? How long will it take for your monthly savings to pay back those costs (this is called the “break-even point”)? It’s always wise to shop around and get quotes from several lenders. What one lender offers might be very different from another, and you want the best deal for your needs.

Key takeaways for today's rates

On February 17, 2026, the mortgage market is showing a welcome sign of stability, with the 30-year fixed refinance rate settling at 6.47%. This minimal yet positive movement creates a consistent environment for homeowners. While the rate hasn't plummeted, it’s in a zone that rewards careful consideration and comparison shopping. For those prioritizing predictability and steady payments, fixed-rate mortgages continue to be the go-to option, offering a reliable balance between saving money and enjoying peace of mind.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 16, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

How to Get the Lowest 30-Year Fixed Mortgage Rate in 2026?

February 16, 2026 by Marco Santarelli

How to Get the Lowest 30-Year Fixed Mortgage Rate in 2026?

Securing the lowest 30-year fixed mortgage rate in 2026 isn’t about luck — it’s about preparation. While most borrowers will see rates hover near 6%, highly qualified buyers may be able to lock in something closer to the mid-5% range. The ultra-low rates of past years aren’t coming back anytime soon. But that doesn’t mean meaningful savings are out of reach. Even a small difference in your rate can translate into tens of thousands of dollars over the life of a loan.

The key is understanding what lenders are really looking for. Getting the lowest available rate goes beyond having a strong credit score — it requires presenting a complete financial profile that signals stability, low risk, and long-term reliability. Here’s what you need to know to position yourself for the most competitive 30-year fixed mortgage rates in 2026.

How to Get the Lowest 30-Year Fixed Mortgage Rate in 2026?

Factors That Will Help You Nail the Lowest Rate

Getting a mortgage rate below 6% in 2026 is definitely achievable if you tick all the right boxes. It goes beyond just having a decent credit score, although that's a huge part of it. Lenders assess several things to figure out how much of a risk you are, and the lower that risk, the better the rate they'll offer.

  • Your Credit Score is King: If you're aiming for the absolute lowest advertised rates, you'll likely need a credit score of 780 or higher. Think of it like climbing a ladder; each rung you move up can make a difference. Moving up just one credit band, say from a 620 to a 640, could potentially drop your rate by roughly 0.18% to 0.25%. That might not sound like much, but over 30 years, it adds up significantly.
  • The Power of Your Down Payment: Putting down a larger amount than the standard 20% (which helps you avoid private mortgage insurance, or PMI) can also signal to your lender that you're less of a risk. A down payment substantially larger than 20% can sometimes lead to additional rate discounts. It shows you're financially invested and have skin in the game.
  • Loan Term: Shorter Can Mean Cheaper: This is a big one, and it often surprises people. If you can swing it, switching from a 30-year fixed mortgage to a 15-year fixed mortgage can typically lower your interest rate by a good chunk, usually around 0.50% to 0.75%. Yes, your monthly payments will be higher because you're paying it off faster, but you'll save a ton on interest over the life of the loan.
  • “Buying Down” Your Rate with Discount Points: This is a strategy where you pay an upfront fee to lower your interest rate for the life of the loan. Typically, paying one discount point, which is 1% of the loan amount, can reduce your interest rate by about 0.25%. You'll need to do the math to see if the upfront cost is worth the long-term savings for your specific situation.
  • Your Debt-to-Income (DTI) Ratio Matters: Lenders like to see that you're not carrying too much debt relative to your income. While a DTI of 35% or less is generally preferred, the most competitive rates often go to borrowers with a DTI below 25%. This shows you have plenty of room in your budget for a mortgage payment.

The “Baseline Floor”: Why Rates Won't Plummet to 2.5%

Now, let's talk about the reality check. It's going to be incredibly difficult to see new 30-year fixed mortgage rates drop below 5.0% in 2026. There are fundamental economic reasons for this, often referred to as the “baseline floor.”

  • Economic “Stickiness”: Things like persistent inflation (even if it's around 2.7%), and the government needing to borrow money, tend to keep long-term bond yields higher than we've seen in the past. These yields are a major factor in mortgage rates.
  • The Fed's Cautious Stance: The Federal Reserve, which controls short-term interest rates, has been signaling a careful approach. They aren't planning on slashing rates drastically through 2026. This means we're not likely to return to the super-low, pandemic-era rates anytime soon.
  • Lender Risk and Profit: Lenders need to make a profit, and they do this by adding a “spread” to the yield on 10-year Treasury bonds. If those Treasury yields are expected to stay around 3.75%, lenders physically can't offer mortgages much lower than about 5.5% without actually losing money.

The “Holy Grail”: Assumable Mortgages in 2026

So, if getting below that 5.5% to 5.75% range for a new mortgage is tough, how can someone potentially get an even lower rate? This is where the “holy grail” of real estate comes in: an assumable mortgage.

An assumable mortgage is a special type of loan that allows a buyer to take over the seller's existing mortgage, including their original interest rate, the remaining balance, and all the loan's terms. This is huge because many sellers who bought homes in 2020 or 2021 have interest rates as low as 2.5% to 3.5%. Imagine taking over a loan with that kind of rate!

How it Works in Practice:

  1. The “Find”: You need to look for homes where the seller has a specific type of loan – typically an FHA, VA, or USDA loan. Standard “Conventional” loans are almost never assumable.
  2. The Qualification: Just because you found a house with an assumable mortgage doesn't mean you automatically get it. You still have to qualify with the original lender based on your credit, income, and DTI. You need to prove you can handle the payments.
  3. The “Gap” Challenge: This is the biggest practical hurdle. Let's say a house is worth $500,000, but the seller only owes $300,000 on their assumable mortgage. You have a $200,000 “gap.” You must be able to come up with that $200,000 difference, either with cash or by taking out a second mortgage (which will likely be at a higher, current market interest rate).

Monthly Payment Comparison: Seeing the Savings

To really drive home why even a small difference in interest rates matters, let's look at a hypothetical $400,000 mortgage (this is the amount after your down payment).

Feature 6.0% Interest Rate 5.5% Interest Rate Monthly Savings Total Interest (30 yrs)
Monthly (P&I) $2,398 $2,271 $127
Total Interest (30 yrs) $463,353 $417,605 $45,748

See that? An extra 0.5% might seem small, but it saves you $127 a month on your mortgage payment. Over 30 years, that's almost $46,000 in total interest savings! That's enough to buy a pretty nice car or cover a good chunk of college tuition.

Your Practical “Way Out” (Steps to Take)

If you're serious about trying to snag an assumable mortgage, here's how I'd recommend approaching it:

  1. Target Specific Listings: Your first move is to tell your real estate agent that you are specifically looking for homes with assumable mortgages. Ask them to search the Multiple Listing Service (MLS) for listings that mention “assumable,” “VA,” or “FHA” in the financing details.
  2. Negotiate the “Gap”: If you don't have all the cash needed for that equity gap (the difference between the sale price and the loan balance), you need to get creative. Sometimes, a seller might be open to “Seller Financing” for that portion. This means you'd pay the gap amount directly to the seller over a few years, often with an agreed-upon interest rate.
  3. Check for “Release of Liability”: If you're assuming a VA loan, it's crucial to make sure the seller gets a formal “release of liability” from the lender. This ensures they aren't on the hook if you happen to miss a payment down the line.
  4. Be Patient: I can't stress this enough: assuming a loan takes much longer than a standard home purchase. Expect an extra 30 to 60 days because the original lender has very little incentive to speed things up for a low-rate transfer.

The “Baseline” Reality Revisited

Just to reiterate, outside of finding an incredible assumable mortgage scenario, the absolute floor for a new 2026 mortgage is heavily influenced by the 10-Year Treasury Yield. Lenders will add their spread (typically around 1.7% to 2.0%) to cover their costs and make a profit. If those Treasury yields are hovering around 3.75%, it's just not physically possible for lenders to offer rates much lower than the 5.5% mark without losing money.

A Message for Your Real Estate Agent

If you're ready to go the assumable route, you need to be prepared. Sending your agent a well-crafted message can make all the difference. This shows you're serious and knowledgeable.

Hi [Agent's Name],

I’m very interested in finding homes with assumable mortgages, specifically FHA, VA, or USDA loans, as I’m aiming to secure a lower interest rate. Could you please search the MLS for listings in [Your Target Area] that mention “assumable” in the private remarks or financing fields?

Here’s the information I’d like to see:

  • 📉 Current interest rate and the remaining balance of the existing loan
  • 💡 An estimate of the equity gap (difference between the sale price and the loan balance)
  • 🤝 Whether the seller is open to seller financing for any part of that gap, or if you can identify recent listings with these loan types that may not have been explicitly advertised as assumable yet

Thank you for your help with this specialized search!

Practical Tools for Your Search

While your agent is your go-to on the MLS, you can also explore these resources to find potential assumable inventory:

  • Roam: This platform is built specifically to help you discover and buy homes with low-rate, assumable mortgages.
  • AssumeList: Similar to Roam, this site lets you search for homes with VA, FHA, and USDA assumable mortgages, including those not yet widely advertised.
  • Realtor.com Filter: You can use their search filters and try keywords like “assumable” or “assume” to narrow down standard listings, though results will vary.

Key “Watch-Outs” for 2026

Keep these things in mind as you navigate the mortgage market in 2026:

  • Processing Time: As mentioned, expect 60 to 120 days for an assumption, unlike the typical 30-day closing for a standard purchase. The original lenders are not in a hurry.
  • The Gap Solution: If the home has appreciated significantly, that gap needs to be covered. If cash is tight, a second mortgage is an option, but remember it will be at current, likely higher, rates.
  • Proof of Funds: Be ready to provide immediate proof of funds to sellers to show you can cover that often substantial equity gap.

While the era of sub-3% fixed rates for everyone seems to be behind us for now, a strategic approach and a keen eye for assumable mortgages can still lead to significant savings.

🏡 Two Turnkey Investment Opportunities With Strong Cash Flow

Bessemer, AL
🏠 Property: Blue Jay Cir
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1610 sqft
💰 Price: $282,000 | Rent: $1,885
📊 Cap Rate: 6.4% | NOI: $1,500
📅 Year Built: 2023
📐 Price/Sq Ft: $176
🏙️ Neighborhood: A-

And

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

Alabama’s newer A- rental vs Tennessee’s larger property with higher NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage, mortgage, mortgage rates

30-Year Fixed Mortgage Rate Falls Steeply by 78 Basis Points

February 16, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Falls Steeply by 78 Basis Points

If you've been dreaming of owning your own home, this is fantastic news you won't want to miss. The 30-year fixed mortgage rate has seen a dramatic drop of 78 basis points compared to this time last year, according to the latest figures released by Freddie Mac. This isn't just a small blip; it's a substantial decrease that translates into real savings for millions of potential homebuyers.

30-Year Fixed Mortgage Rate Falls Steeply by 78 Basis Points

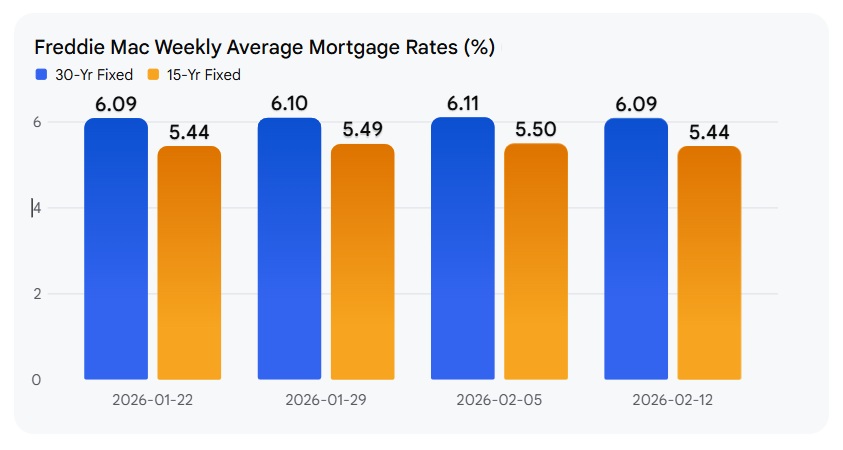
This latest report from Freddie Mac, released on February 12, 2026, shows the average 30-year fixed-rate mortgage (FRM) now sitting at 6.09%. While that's a tiny dip from last week's 6.11%, the real story is the significant drop from the 6.87% we saw a year ago. This substantial annual decline means a much more manageable monthly payment and a lower total cost of borrowing if you're looking to purchase a home this year.

What Does This Mean for You? Let's Break Down the Savings.

Freddie Mac Weekly Average Mortgage Rates (%)

It’s easy to get lost in the numbers, so let's put this into perspective. A basis point is simply one-hundredth of a percent. So, a drop of 78 basis points means your interest rate has gone down by 0.78%. When you're talking about mortgages, even small changes in interest rates can add up to thousands of dollars over the life of a loan.

Let's look at the numbers Freddie Mac provided in their Primary Mortgage Market Survey for the week ending February 12, 2026:

Mortgage Type Current Rate (02/12/2026) 1-Week Change 1-Year Change Monthly Average 52-Wk Average 52-Week Range
30-Year FRM 6.09% -0.02% -0.78% 6.1% 6.49% 6.06% – 6.89%
15-Year FRM 5.44% -0.06% -0.65% 5.47% 5.7% 5.38% – 6.04%

The Power of a Lower Rate: Real-World Impact

Imagine you're looking to buy a $300,000 home with a 30-year mortgage.

  • At last year's rate of 6.87%: Your estimated monthly principal and interest payment would be around $1,969.
  • At the current rate of 6.09%: Your estimated monthly principal and interest payment drops to about $1,822.

That's a difference of $147 per month! Over 30 years, that's a savings of over $52,900! That’s a significant amount of money that could go towards home improvements, savings, or simply enjoying life a little more.

Even the 15-year fixed-rate mortgage has seen a welcome decline, averaging 5.44%, down 0.65% from a year ago. This makes paying off your home faster even more appealing.

Why Are Rates Dropping So Significantly? It’s All About the Economy.

Freddie Mac's Chief Economist, Sam Khater, hit the nail on the head when he mentioned that housing affordability continues to measurably improve. This isn't a fluke; it’s a direct result of a strong economy and a robust labor market. When the economy is doing well, and people have jobs, lenders tend to feel more confident, which can lead to lower borrowing costs.

It's fascinating to see these rates holding near their lowest levels in three years. This is a sweet spot for anyone thinking about making a move. The market has been a bit unpredictable, and seeing this kind of sustained affordability improvement is a breath of fresh air.

What This Means for Buyers (and Sellers!)

For Prospective Homebuyers:

  • Increased Buying Power: With lower interest rates, your monthly payment goes further. This means you can potentially afford a slightly more expensive home than you could a year ago, or you can enjoy a lower monthly payment on the same priced home.
  • More Options: As affordability improves, more people can enter the market. This can lead to a healthier inventory of homes for sale, giving buyers more choices. Freddie Mac specifically noted that purchase application activity has driven higher than a year ago, which is a strong indicator of buyer interest.
  • Refinancing Opportunities: If you already own a home and have an existing mortgage with a higher interest rate, this could be a prime time to consider refinancing. Locking in a lower rate can significantly reduce your monthly expenses.
  • Reduced Stress: Let's be honest, buying a home is a big deal. Knowing you're securing a loan at a favorable rate can reduce some of that financial anxiety.

For Home Sellers:

  • More Motivated Buyers: With increased affordability and buyer interest, sellers can expect to see more qualified buyers actively looking.
  • Potentially Faster Sales: A strong buyer pool can lead to quicker sale times.
  • Competitive Market: While rates are low, they are still subject to market fluctuations. This current dip may not last forever, encouraging buyers to act sooner rather than later.

Beyond the Rate: Economic Factors at Play

It’s interesting to note how these rates are moving even with some market wobbles. Despite a strong jobs report that might typically cause some bond market volatility, mortgage rates have dipped. Freddie Mac pointed out that the 10-year Treasury yield, which mortgage rates typically follow, was down from the previous week. This shows that while the job market might be strong, other financial forces are also at play, pushing borrowing costs down.

My Takes from the Trenches

Having followed the housing market for years, I can tell you that these kinds of annual declines are significant. We haven't seen this sustained level of affordability improvement in quite some time. The three-year lows are a big deal, and it’s a testament to a period of economic stability that benefits consumers directly. It’s not just about the headline number; it's about the cumulative effect of these lower rates making the dream of homeownership more attainable for many families.

I believe this trend is encouraging for the broader housing market. When more people can afford to buy, it stimulates local economies, supports construction jobs, and builds wealth for individuals and families. It’s a win-win-win.

Looking Ahead

While this is fantastic news, it’s always wise to remember that mortgage rates are influenced by many factors and can change. My advice is always to talk to a trusted mortgage professional. They can help you understand your specific situation, explore your options, and guide you through the process of securing the best possible rate for your dream home. Don't let this opportunity pass you by! This is a significant moment for homebuyers, and capitalizing on these lower rates could make a world of difference to your financial future.

🏡 Two Turnkey Investment Opportunities With Strong Cash Flow

Bessemer, AL
🏠 Property: Blue Jay Cir
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1610 sqft
💰 Price: $282,000 | Rent: $1,885
📊 Cap Rate: 6.4% | NOI: $1,500
📅 Year Built: 2023
📐 Price/Sq Ft: $176
🏙️ Neighborhood: A-

And

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

Alabama’s newer A- rental vs Tennessee’s larger property with higher NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage, mortgage, mortgage rates

Today’s Mortgage Rates, Feb 16: Rates Drop to New Lows, Marking a Significant Shift

February 16, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or looking to lower your monthly payments on an existing mortgage, you're in luck. As of February 16, 2026, today’s mortgage rates are looking incredibly attractive, with the average 30-year fixed rate dipping to a compelling 5.85% and the 15-year fixed at 5.36%, according to data from Zillow. This marks a significant shift from the higher rates we experienced in previous years, offering a genuine opportunity to lock in some of the best borrowing costs we've seen in quite some time.

Today’s Mortgage Rates, Feb 16: Rates Drop to New Lows, Marking a Significant Shift

Understanding Today's Mortgage Rates: The Numbers

Let's break down exactly where things stand. Zillow Home Loans provides a clear snapshot of the current mortgage rate environment, and it’s quite encouraging for borrowers.

Here's a look at the average rates as of February 16, 2026:

Loan Type Average Rate
30-year fixed 5.85%
20-year fixed 5.64%
15-year fixed 5.36%
5/1 ARM 5.81%
7/1 ARM 5.71%
30-year VA 5.36%
15-year VA 5.15%
5/1 VA 4.99%

What’s really striking here is how these rates are hovering near multi-year lows. You can see that both conventional loans and VA loans are offering competitive options. The VA loan products, especially, are incredibly attractive with the 5/1 VA ARM dipping below 5% at 4.99%. This is fantastic news for our veterans and service members.

What's Driving These Lower Rates? A Look Under the Hood

It’s easy to focus on the numbers, but understanding why they're falling is just as important. Several factors are working together to create this borrower-friendly environment:

  • A Three-Year Trend Reversal: We’ve been seeing a steady decline in mortgage rates since the middle of 2025. This is a significant turnaround from the rising rates we experienced earlier this decade. It suggests a cooling of inflationary pressures and a shift in monetary policy.
  • Economic Winds are Shifting: Softer inflation data and easing Treasury yields have played a major role. When inflation is under control and the government's borrowing costs (Treasury yields) go down, lenders have more room to offer lower interest rates on mortgages. It's a domino effect.
  • The Federal Reserve's Influence: The Federal Reserve made three interest rate cuts in late 2025. While they held rates steady at their January 28, 2026 meeting, the market anticipates further cuts. The Fed’s decisions are heavily influenced by inflation and labor market data. Some experts are predicting they might hold off on additional cuts until at least March 2026, but the trend is leaning towards easing.
  • Falling Treasury Yields: Specifically, the 10-year Treasury yield, which mortgage rates are often closely tied to, is currently hovering around 4.065%. This is a key indicator that points to lower mortgage rates being sustainable.

Expert Predictions: What’s Next?

While today’s rates are a treat, it's natural to wonder about the future. Major industry organizations like the Mortgage Bankers Association (MBA) and Fannie Mae are forecasting that 30-year fixed rates will likely stay in a narrow range, around 6%, for the rest of 2026. This suggests that while we might not see rates plummet even further dramatically in the short term, they are expected to remain relatively stable and historically attractive. This forecast provides a degree of certainty for those planning their homeownership journey.

How These Rates Impact You: Homebuyers and Refinancers

The implications of these lower mortgage rates are significant and far-reaching for anyone involved in the housing market. From my perspective, this is a moment to really consider your options.

For Homebuyers:

  • Improved Affordability: This is the biggest win. Lower rates mean either your monthly mortgage payment is less for the same loan amount, or you can afford to borrow more for the same monthly payment. This is especially critical in markets where home prices have been high, making affordability a major hurdle. You might find yourself qualifying for a bigger home than you initially thought possible, or simply enjoying a more comfortable monthly budget.
  • Increased Purchasing Power: With lower interest costs, your housing budget stretches further. This could enable you to get into a more desirable neighborhood, a larger home, or simply have more wiggle room in your finances after moving in.

For Refinancers:

  • Significant Savings: If you have a mortgage with an interest rate significantly higher than the current offerings, refinancing could save you thousands of dollars over the life of your loan. Even a half-percent or one-percent drop can add up substantially. I’ve seen clients save hundreds of dollars per month by refinancing when rates dropped, which is life-changing money.
  • Accessing Equity: Refinancing can also be a way to tap into your home equity for things like renovations, consolidating debt, or funding education, often at a better rate than other loan types.

For Veterans and Service Members:

  • Unbeatable Value: VA loans are already known for their fantastic benefits, like no down payment options and no private mortgage insurance. When coupled with the current low rates, such as the 5/1 VA ARM at 4.99% or the 15-year VA at 5.15%, they represent some of the most compelling and cost-effective financing options available today. It's a well-deserved perk for those who have served.

Key Takeaways: Seize the Opportunity

To sum it up, February 16, 2026, truly feels like a special day in the mortgage market. The 30-year fixed rate at 5.85% and the 15-year fixed at 5.36% aren't just numbers on a screen; they represent a tangible opportunity to improve your financial situation.

If you’ve been on the fence about buying or refinancing, now is the time to seriously explore your options. The market conditions are exceptionally favorable, but these low rates might not stick around forever. Acting strategically and understanding your personal financial goals will be key to making the most of this borrower-friendly environment. It’s a chance to secure a lower cost of borrowing that can benefit you for years to come.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, February 16: 30-Year Refinance Rate Rises by 2 Basis Points

February 16, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

If you're thinking about refinancing your home on this February 16th, 2026, you'll notice that the popular 30-year fixed refinance rate has seen a slight uptick, moving up by just 2 basis points from last week. While it's not a dramatic change, it's a good reminder that mortgage rates can shift, and staying informed is key for making the best financial decisions for your home. We're seeing a bit of a mixed bag out there today, with some rates ticking up and others showing more significant changes, especially when we look at adjustable-rate mortgages.

Mortgage Rates Today – February 16, 2026: 30-Year Refinance Rate Rises by 2 Basis Points

Today's Refinance Rates at a Glance

Let's break down what the numbers are telling us today, according to Zillow's latest data.

Loan Type Today's Rate (Feb 16, 2026) Change from Previous Day Change from Last Week
30-Year Fixed Refinance 6.50% +4 basis points +2 basis points
15-Year Fixed Refinance 5.50% +5 basis points +2 basis points
5-Year ARM Refinance 7.12% +30 basis points Not Provided

Digging Deeper: What These Numbers Mean for You

You might be wondering, “What does a 4 basis point increase really mean?” Well, in the world of mortgages, even seemingly small changes can add up.

  • The 30-Year Fixed: This is the workhorse for many homeowners, and today it's sitting at an average of 6.50%. This is a 4 basis point jump from yesterday. While that might sound tiny, if you're thinking about refinancing a significant amount, it can impact your monthly payment. Compared to last week's average of 6.48%, we're seeing a 2 basis point climb. This indicates a gentle upward trend, which suggests lenders are watching the economic signals carefully. It’s not a huge surge, but it’s enough to encourage those who have been on the fence to maybe consider acting sooner rather than later, especially if their current rate is much higher.
  • The 15-Year Fixed: For those looking to pay off their mortgage faster, the 15-year fixed refinance rate has also moved up, now averaging 5.50%. This is a 5 basis point increase from yesterday. The appeal of a 15-year loan is its shorter term and typically lower interest rate, helping you save a lot of money on interest over time. However, with rates trending upwards, homeowners will need to weigh that benefit against the higher monthly payment they'll likely see compared to a 30-year loan.
  • The 5-Year ARM: This is where we see the most noticeable shift today. The 5-year Adjustable-Rate Mortgage (ARM) refinance rate has jumped up by a significant 30 basis points, landing at 7.12%. This is a pretty big move for an ARM in a single day. ARMs are attractive because they often start with a lower introductory rate than fixed-rate mortgages. However, as this sharp increase shows, they can become more expensive quickly if interest rates rise. This jump is a strong signal to be very cautious if you're considering an ARM right now, or if you already have one, to be prepared for potential payment increases down the line.

Market Insights: Why the Movement?

Understanding why rates change is just as important as knowing the rates themselves. Several factors are influencing these shifts.

  • The Federal Reserve's Footing: The Federal Reserve's actions (or inactions) have a huge impact on borrowing costs. We saw them make a few rate cuts in late 2025, which was great for lowering mortgage costs. However, they held the federal funds rate steady at their January 28, 2026, meeting. Now, with some recent reports showing inflation cooling down a bit in January, the market is buzzing with the possibility of another rate cut by June 2026. This kind of news can create uncertainty and lead to minor rate adjustments as lenders try to price in future expectations. My take is that the Fed is playing a careful game, trying to balance economic growth with keeping inflation in check.
  • Treasury Yields and Economic Signals: Mortgage rates often move in tandem with the yields on Treasury bonds, especially the 10-year Treasury note. When Treasury yields go up, mortgage rates tend to follow suit, and vice versa. The slight increase in fixed rates today likely reflects some upward movement in Treasury yields, possibly due to strong economic data or market anticipation of future Fed actions. The significant jump in ARM rates is particularly sensitive to these short-term yield fluctuations.
  • A Resilient Economy: It’s good news that the labor market is strong and the economy is showing resilience. This is generally a positive sign for overall financial health, but it can also keep interest rates from falling too rapidly. Lenders might be anticipating continued economic strength, which could lead them to keep rates from dropping too much.

Refinance Opportunities: Is Now the Time?

This is the big question on everyone's mind. With rates nudging up, it makes you wonder if you should jump on refinancing or wait.

According to insights from the Mortgage Bankers Association (MBA), refinance activity has actually seen a massive surge – up 101% compared to a year ago! A lot of this is driven by borrowers who took out loans in 2024 and 2025 when rates were higher, likely above 7%. These folks are now seeing opportunities to lower their monthly payments significantly by refinancing.

However, it's important to note that many Americans are currently “locked in” with mortgage rates below 5%. For these homeowners, refinancing right now might not make financial sense unless rates drop considerably lower than today's averages. My personal opinion is that if your current rate is 7% or higher, it’s definitely worth exploring a refinance. Even a small reduction can save you thousands over the life of your loan. But if you're already in that sub-5% range, you're in a great spot and might want to hold off unless there's a substantial drop in rates.

Impact on Borrowers: What Should You Do?

So, what does all this mean for you as a homeowner or potential borrower?

  • Homeowners Considering Refinancing: The slight rise in fixed rates today might serve as a nudge for those who have been procrastinating. If you've been looking at refinancing your 30-year fixed or 15-year fixed loan and your current rate is significantly higher than today's 6.50% or 5.50%, it could be a good time to at least get some quotes and see if you can lock in a lower rate before they potentially move higher.
  • Those With ARMs: The sharp increase in the 5-year ARM rate to 7.12% is a serious warning sign. If you have an ARM, or are considering one, understand that your payments can change quickly. This is especially true in a market where rates are showing upward momentum. You need to be very comfortable with the possibility of your payments increasing.
  • Planning for the Future: It's always wise to remember that even minor changes in basis points can have a big impact on your total interest paid over the 15 or 30 years of your mortgage. Understanding these costs is crucial for your long-term financial planning.

A Quick Summary for Today's Rates

To wrap up, on February 16, 2026, mortgage refinance rates are showing a mixed bag. We're seeing small increases in fixed-rate options, like the 30-year fixed at 6.50%, and a more substantial jump in adjustable-rate mortgages, with the 5-year ARM reaching 7.12%. The market is influenced by Federal Reserve signals, economic performance, and Treasury yields. For many homeowners who took out loans at higher rates in previous years, refinancing remains a smart move to save money. However, those with already low rates should proceed with caution. Staying informed and acting strategically are your best bets for navigating these ever-changing financial waters and securing your homeownership goals.

🏡 2 Renovated Properties Available for Investors

Port Charlotte, FL
🏠 Property: Dorion St
🛏️ Beds/Baths: 4 Bed • 4 Bath • 2086 sqft
💰 Price: $412,400 | Rent: $3,190
📊 Cap Rate: 6.2% | NOI: $2,124
📅 Year Built: 2023
📐 Price/Sq Ft: $198
🏙️ Neighborhood: A+

and

Kansas City, MO
🏠 Property: E 110th Terrace
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1002 sqft
💰 Price: $220,000 | Rent: $1,700
📊 Cap Rate: 6.9% | NOI: $1,273
📅 Year Built: 1957
📐 Price/Sq Ft: $220
🏙️ Neighborhood: A-

Florida’s modern build with strong cash flow vs Missouri’s affordable rental with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – February 15, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, Feb 15: 30-Year Fixed At Multi-Year Lows Offers Huge Savings

February 15, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you've been watching the housing market with a keen eye, you know how crucial mortgage rates are. Well, get ready for some good news! Today, February 15, 2026, mortgage rates are currently sitting at some of the most attractive levels we've seen in years, making it a fantastic time whether you're looking to buy your dream home or refinance your current mortgage. According to Zillow's lender marketplace, the average 30-year fixed mortgage rate is a sweet 5.85%. This is a significant dip compared to this time last year, when the same loan averaged a higher 6.87%.

Today’s Mortgage Rates, Feb 15: 30-Year Fixed At Multi-Year Lows Offers Huge Savings

This current environment is a breath of fresh air, and Zillow’s data highlights just how good things are. Here’s a breakdown based on their lender marketplace:

  • 30-year fixed: A fantastic 5.85%
  • 20-year fixed: Currently at 5.64%
  • 15-year fixed: Just 5.36%
  • 5/1 ARM (Adjustable-Rate Mortgage): Offering a competitive 5.81%
  • 7/1 ARM: Slightly lower at 5.71%
  • 30-year VA Loan: Extremely attractive at 5.36%
  • 15-year VA Loan: Even lower at 5.15%
  • 5/1 VA Loan: The absolute lowest for refinancers we're seeing, coming in at 4.99%

See? These rates are practically hovering around their three-year lows. This is the kind of environment that can make a big difference in your monthly payments and how much house you can afford. It’s not just about locking in a lower rate today; it’s about the long-term savings.

What's Driving These Favorable Rates? Unpacking the Trends

It’s always helpful to understand why things are happening, right? The steady decline in mortgage rates since around May of 2025 hasn't been random. Several factors have played a role.

One of the biggest influences is the broader economic picture. We recently saw the January jobs report, which was stronger than many expected. Unemployment dropped to 4.3%, which is great news for the economy. However, this positive economic signal has actually made experts rethink when the Federal Reserve might decide to lower interest rates further. Some analysts now believe the Fed might hold off on additional rate cuts at their upcoming March 2026 meeting. This doesn't necessarily mean rates will jump, but it suggests a period of stability.

Looking ahead, major housing authorities like Fannie Mae and the Mortgage Bankers Association (MBA) are forecasting that mortgage rates will stay relatively steady throughout 2026. Their projections put the average rate somewhere between 6.0% and 6.1%. This forecast supports the idea that today’s rates are a real opportunity, not just a fleeting dip.

And let’s not forget the powerful connection between mortgage rates and the bond market, specifically the 10-year Treasury yield. When the 10-year Treasury yield falls, mortgage rates tend to follow suit. We've seen this yield recently dip to 4.065%, which is a key reason why we're seeing these borrower-friendly conditions today. It’s like a domino effect, and right now, the dominos are falling in our favor.

Your Action Plan: How to Benefit from Today's Rates

So, what does this all mean for you as a potential homeowner or someone looking to save on your current mortgage? It’s simple, really: it’s time to pay attention and act strategically.

For Homebuyers:

Lower interest rates mean your money goes further.

  • Increased Affordability: With lower rates, you can either afford a bigger loan amount for the same monthly payment, or you can keep your monthly payment lower for the same loan amount. This can open up more housing options in your desired neighborhoods.
  • More Buying Power: That extra breathing room in your budget can translate to affording that extra bedroom, a larger backyard, or a better school district.

For Refinancers:

If you have an existing mortgage with a rate significantly higher than today’s, refinancing could save you a substantial amount of money over the life of your loan.

  • Significant Savings: Even a half-percent or one-percent difference can add up to tens of thousands of dollars over 15, 20, or 30 years.
  • Reduce Your Term: You might even consider refinancing into a shorter loan term to pay off your home faster and save even more on interest.

A Special Shout-out to Our Veterans:

VA loans continue to be a standout product, especially for those who have served our country.

  • Unbeatable Rates: The 5/1 VA ARM at 4.99% is incredibly low, offering exceptional value for refinancers.
  • No Down Payment: Remember, VA loans often come with the advantage of no down payment, making homeownership even more accessible.

My Take: Seizing the Moment

Looking at these numbers, I’m really impressed. We’re not talking about tiny shifts; these are meaningful drops that can impact household budgets for years to come. As someone who’s seen market cycles come and go, I can say that a period like this is a clear invitation to get serious about your housing goals.

It’s easy to get caught up in the day-to-day news cycle, but the underlying data for February 15, 2026, paints a picture of opportunity. The combination of relatively stable economic indicators, forecasts for continued favorable rates, and the specific attraction of mortgage products means that if you’ve been on the fence, now is the time to explore your options.

Don’t let this moment pass you by. Whether you're a first-time buyer dreaming of that “For Sale” sign or someone looking to trim your monthly expenses by refinancing, understanding these rates and acting decisively can make a huge difference.

Final Takeaways for Today's Mortgage Rates

February 15, 2026, is shaping up to be a really important date for anyone involved in the housing market. With mortgage rates at levels not seen in years, this is a prime opportunity to lock in lower borrowing costs. Whether you’re buying a new home or refinancing your current one, taking advantage of these favorable conditions could lead to significant long-term financial benefits. While economic shifts and Federal Reserve decisions will always play a role, today's market clearly highlights the value of being prepared and acting strategically.

🏡 Two Profitable Rental Properties With Strong Investor Appeal

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

Akron, OH
🏠 Property: Whitney Ave
🛏️ Beds/Baths: 3 Bed • 1.5 Bath • 1056 sqft
💰 Price: $135,000 | Rent: $1,225
📊 Cap Rate: 9.4% | NOI: $1,063
📅 Year Built: 1923
📐 Price/Sq Ft: $128
🏙️ Neighborhood: C+

Texas’s A‑rated rental with stability vs Ohio’s affordable property with higher cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to Our Investment Counselor (No Obligation):

(800) 611-3060

View All Properties 

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Current Mortgage Rates, mortgage, mortgage rates, Today’s Mortgage Rates

  • « Previous Page
  • 1
  • …
  • 49
  • 50
  • 51
  • 52
  • 53
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...