Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Today’s Mortgage Rates, March 5: Rates Hold Firm at 6%, Near Lowest Point Since 2022

March 5, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Mortgage rates have recently hovered near their lowest levels since late 2022, though they experienced a slight uptick this week due to geopolitical tensions in the Middle East. As of March 5, 2026, the average 30-year fixed mortgage rate is approximately 6.00%, according to Freddie Mac.

Today's Mortgage Rates, March 5: Rates Hold Firm at 6%, Near Lowest Point Since 2022

Freddie Mac Weekly Averages (March 5, 2026)

  • 30-Year Fixed-Rate Mortgage: Averaged 6.00%, up from 5.98% the previous week.
  • 15-Year Fixed-Rate Mortgage: Averaged 5.43%, a slight decrease from 5.44% the prior week.

As of March 5, 2026, Zillow's mortgage rates are trending slightly lower than the weekly averages reported by Freddie Mac. Zillow reported today, the 30-Year Fixed-Rate has dipped to 5.85%, down a solid seven basis points. This is a sign that lenders are adjusting their offerings, likely in response to market sentiment and the cost of borrowing for them.

For those looking at shorter-term loans, the news is even better. The 15-year fixed mortgage rate has seen a sharper drop, falling by ten basis points to 5.40%. This makes paying off your home faster an even more attractive option for some.

Zillow rates often appear lower than Freddie Mac's because Zillow aggregates rates from its online lender marketplace, whereas Freddie Mac reports based on loan applications submitted to its underwriting system.

Here’s a quick look at the rates as of March 5, 2026, based on Zillow's data:

Loan Type Current Interest Rate
30-Year Fixed 5.85%
20-Year Fixed 5.81%
15-Year Fixed 5.40%
5/1 ARM 5.72%
7/1 ARM 5.53%
30-Year VA 5.46%
15-Year VA 5.24%
5/1 VA 5.28%

You'll notice a few things here. The rates for a 20-year fixed mortgage are very close to the 30-year fixed, which is interesting. Also, the rates for Adjustable-Rate Mortgages (ARMs) like the 5/1 and 7/1 are competitive, especially given their initial lower periods. And for our veterans, the VA loan rates continue to be very appealing.

What's Driving These Numbers: My Take

For me, seeing these rates is a positive step, but it's important to remember that this is just one snapshot in time. The mortgage market is like a sensitive barometer for the economy.

  • Inflation Worries and Easing: We've seen some jitters this week regarding inflation, which can sometimes push mortgage rates up. However, these dips suggest that the overall impact might be leveling out, or perhaps other factors are calming lenders. It's a constant dance between fear and confidence in the market.
  • Treasury Yields are Key: Mortgage rates are closely tied to the yields on U.S. Treasury bonds, especially the 10-year Treasury note. When those yields go up, mortgage rates often follow suit, and vice versa. Today's movement suggests that Treasury yields have likely stabilized or even eased a bit, giving mortgage rates room to breathe.
  • The Federal Reserve's Shadow: The Federal Reserve's actions – or inactions – are always a major story in the mortgage world. The Federal Open Market Committee (FOMC) is set to meet from March 17-18, 2026. The current betting is that they'll keep their benchmark interest rate steady within the 3.50%–3.75% range. This steady hand from the Fed can provide a degree of stability, which is generally good for mortgage rates. However, any hint of future moves can cause ripples.

Looking at the Bigger Picture: What the Data Reveals

It’s not just about today’s number; it's about the trend and what influences it.

  • Year-over-Year Improvement: The most encouraging takeaway for many is that today's rates are still about 40 basis points (or 0.40%) lower than they were a year ago. This means that if you were looking to buy or refinance in March 2025, you're likely facing more favorable borrowing costs now. That difference can translate into significant savings over the life of a loan.
  • The Importance of Shopping Around: Bankrate's Mortgage Rate Variability Index is currently at a 7 out of 10. This is a really important signal. It means there's a wide range of offers out there from different lenders. It’s not enough to just look at one bank or one online lender. I strongly advise borrowers to get quotes from at least three to five different sources. The savings can be substantial. Think about it: a small difference in interest rate can add up to thousands of dollars over 15 or 30 years.

What This Means for You, Today

So, what does all this mean if you're in the market for a mortgage?

  • Refinancing Opportunities: If you pulled out a loan at a rate significantly higher than 7% back in 2025, today's rates around 5.85% for a 30-year fixed could make refinancing a very smart move. It's worth running the numbers to see if you can lower your monthly payment and save money in the long run.
  • New Buyers: For first-time homebuyers or those looking to upgrade, these rates offer a more approachable entry point into the housing market. The slightly lower costs can make that dream home feel a little more attainable.
  • Stay Informed: The mortgage market is dynamic. Upcoming economic reports, like the February jobs report (due March 6) and the CPI inflation reading (March 11), will be closely watched. Positive economic news might keep rates stable, while weaker data could potentially push them down further. My advice is to stay tuned.

My Final Thoughts

Navigating mortgage rates can feel like trying to catch a moving target, but understanding the factors at play gives you a real advantage. Today's rates offer a glimmer of opportunity, with the 30-year fixed dipping below 6% and the 15-year fixed looking even more attractive. Remember to always compare offers diligently, as lender variability is a significant factor right now. The market is still sensitive, but the current trend suggests a more favorable borrowing environment compared to last year.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 5, 2026: 30-Year Refinance Rate Rises by 1 Basis Point

March 5, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Are you watching mortgage rates like a hawk, hoping for the perfect moment to refinance? Well, let's dive into what's happening today, Thursday, March 5, 2026. The 30-year fixed refinance rate has edged up slightly, sitting at 6.49%, according to Zillow's latest data. This is a minor increase of 1 basis point compared to last week. While not a dramatic jump, it's a change worth noting if you're considering refinancing.

Mortgage Rates Today, March 5: 30-Year Refinance Rate Rises by 1 Basis Point

Current Refinance Rate Snapshot

Here's a quick look at how the different refinance rates are shaping up today:

Loan Type Rate Change
30-Year Fixed Refinance 6.49% +1 bps (week)
15-Year Fixed Refinance 5.53% Stable
5-Year ARM Refinance 6.60% Stable

As you can see, the 15-year fixed refinance rate remains at 5.53%, and the 5-year ARM refinance rate is steady at 6.60%. But what's driving these numbers, and what does it mean for you?

Decoding the Market: What's Influencing Mortgage Rates?

Mortgage rates aren't determined by a magic crystal ball. They're influenced by a complex recipe of economic factors. Right now, we're seeing a few key ingredients at play:

  • Inflationary Pressures: Persistent inflation continues to cast a shadow, keeping rates elevated. The fear of rising prices erodes the value of long-term investments like mortgage-backed securities, pushing yields and rates higher.
  • Geopolitical Uncertainty: The world stage always has some drama, and recently, U.S. actions against Iran stirred up inflation worries among investors. This type of disruption can negatively affect Treasury yields and, consequently, mortgage rates.
  • The Federal Reserve's Stance: All eyes are on the Federal Reserve (The Fed). Everyone is very curious about it's plans. They are like the conductor of this big economic orchestra. The Fed's expected to hold steady at its upcoming meeting on March 17–18, maintaining a cautious approach. If the Fed signals a commitment to keeping interest rates elevated for longer, that will likely translate into higher mortgage rates as well.
  • Economic News: And we are closely watching the jobs report. The February jobs report (due Friday, March 6) is a big one. A weaker-than-expected labor market could potentially ease rates, while strong employment numbers might hold them steady or even push them a bit higher.

Refinance Boom: Why Are People Jumping In?

Despite rates not being at historical lows, the Mortgage Bankers Association reports a whopping 150% surge in refinance applications year-over-year. What's driving this? My take is that many homeowners locked in rates above 7% in 2025, and they're now seeing opportunities to lower their monthly payments, even with rates higher than those rock bottom deals. People are saying, “I don't think anything will be better than this, I want to refinance.”

Refinancing: Is It the Right Move for You?

Refinancing can be a fantastic way to save money, but it's not a one-size-fits-all solution. Before you take the plunge, consider these factors:

  • Refinance vs. Purchase Rates: Keep in mind that refinance rates can be 0.01% to 0.15% higher than rates for new home purchases for the same loan term.
  • Crunch the Numbers: Calculate that break-even point! It's how long it will take for your interest savings to outweigh the closing costs, which typically run between 2% and 6% of the loan amount. If you plan to stay in your home long enough to recoup these costs and start seeing the savings, it's worth considering. This is basic mathematics. However most people ignore it
  • Don't Settle: Shop around! Rates can vary significantly among lenders. For example, I've found that Navy Federal Credit Union and Bank of America often offer very competitive 15-year rates, sometimes as low as 5.5%, for qualified borrowers.

Looking Ahead: What's the Mortgage Rate Forecast for 2026?

Trying to predict the future is always tricky, but major institutions project rates to remain relatively stable in the near term, probably averaging around 6.1% through the end of 2026. While there's a potential downside to 5.7% in an optimistic scenario, experts don't expect a return to the super-low 3% range we saw earlier in the decade. So, if you're holding out for those ultra-low rates, it might be time to adjust your expectations.

Key Takeaways

  • The 30-year fixed refinance rate is at 6.49%, a slight increase of 1 basis point from last week.
  • The 15-year fixed and 5-year ARM rates remain stable at 5.53% and 6.60%, respectively.
  • Inflation, geopolitical events, and Treasury yield fluctuations continue to drive these rate trends.
  • Refinance activity is surging as borrowers seek relief from higher-rate loans from 2025.
  • Rates are expected to stay near 6% through 2026, offering limited opportunities for significant drops.

Is now the right time to refinance? It really depends on your individual circumstances, financial goals, and risk tolerance. Do you want to just be stuck hoping for something better? However, you can make the right choice by carefully assessing your finances, shopping around for the best rate, and understanding the market trends.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 3, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 4: Rates Climb Amid Bond Market Volatility and Global Events

March 4, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of Wednesday, March 4, 2026, we're seeing mortgage rates edge up, with the popular 30-year fixed mortgage rate now sitting at 5.92%. While this is a bit higher than it was just a couple of days ago, it's still a good spot to be in if you're comparing it to rates from not too long ago.

It feels like just yesterday we were talking about rates hovering around the high 6s and even touching 7%, so this 5.92% is still a much more approachable number for many. But why the small bump? My gut tells me it's a mix of global events and how the market is reacting. Think of it like a ripple effect; something happening on the other side of the world can genuinely impact your ability to get a home loan right here.

Today's Mortgage Rates, March 4: Rates Climb Amid Bond Market Volatility and Global Events

Let's get down to the nitty-gritty. According to Zillow's lender marketplace, that 30-year fixed mortgage rate has ticked up 12 basis points since Monday. For those new to this, a basis point is just one-hundredth of a percent. So, a 12 basis point increase means a 0.12% jump. It doesn't sound like a lot, but in the world of mortgages, every little bit can add up over the life of a loan.

Similarly, the 15-year fixed mortgage rate has seen a slight increase, moving 11 basis points higher to 5.50% during the same timeframe. This tells me that it's not just one type of loan that's reacting; the whole market is trending a bit upward for now.

To make things super clear, here’s a quick look at what the rates are showing right now, based on Zillow's data:

Loan Type Current Interest Rate
30-Year Fixed 5.92%
20-Year Fixed 6.05%
15-Year Fixed 5.50%
5/1 ARM 5.91%
7/1 ARM 5.58%
30-Year VA 5.53%
15-Year VA 5.24%
5/1 VA 5.33%

Why the Push Upward? Let's Connect the Dots.

Now, if you're like me, you want to know why these rates are moving. It's rarely just one thing! Today, the talk among market watchers is that a lot of this upward pressure is coming from what's happening in the bond market. Specifically, there's been some selling pressure on bonds, which tends to push interest rates higher.

What's driving that selling pressure? Unfortunately, it seems to be renewed geopolitical conflict in the Middle East. Strikes involving Iran have caused oil prices to spike, and when oil prices go up, it often fuels inflation concerns. This makes investors a little nervous and prompts them to shift their money around, which, in turn, affects benchmarks like the 10-year Treasury yield. This yield is a really important indicator for mortgage rates, and it's now sitting above 4%. Think of it as a mood ring for the economy; when the 10-year Treasury yield is up, it often means mortgage rates will follow suit.

Looking Ahead: What's Next for Mortgage Rates?

So, what does this mean for the coming days and weeks? I always tell people to keep an eye on a few key things.

  • The Bond Market's Mood: As I mentioned, the bond market is a big player. If we see continued selling pressure due to those geopolitical worries or rising oil prices, rates could stay elevated or even nudge a bit higher. On the flip side, if things calm down and investors feel more secure, we might see bond yields come back down, which could mean lower mortgage rates.
  • Economic Signals from the Jobs Report: Big economic news is always a driver. This Friday, we're all waiting for the February jobs report. This is huge! If the report shows a weakening labor market, it could signal to the Federal Reserve that the economy is cooling down, potentially leading to lower interest rates. But if the jobs report is strong, showing lots of hiring and wage growth, it might suggest the economy is still robust, and rates could stay where they are or even climb a bit more.
  • The Federal Reserve's Next Move: The Federal Reserve has been holding the federal funds rate steady, currently between 3.50%–3.75%, since their January meeting. Everyone's looking ahead to their next meeting on March 17–18. The general consensus is that they'll probably hold rates steady again. However, any hints or signals they give about future rate cuts later in 2026 could be a game-changer. If they start to suggest they might lower rates down the line, that could help keep mortgage rates below that 6% mark we're currently dancing around.
  • More Homes on the Market? This is exciting news for potential buyers. Despite the slight uptick in rates, projections suggest that housing inventory – meaning the number of homes for sale – is going to rise. We're expecting an increase of nearly 9% year-over-year in 2026. A big reason for this is that the “lock-in effect” (where homeowners with super low rates are hesitant to sell and buy again at a higher rate) is starting to ease. As more homeowners feel comfortable listing their properties, it means more choices for buyers, which can help balance things out even with slightly higher borrowing costs.

What This Means for You: Borrowers and Buyers

So, what's the takeaway here?

  • For Refinancers: If you managed to lock in a mortgage rate significantly higher than 7% back in 2024 or 2025, you're still in a good position. Even with the slight increase today, rates below 6% offer a real opportunity to lower your monthly payments. It’s definitely worth looking into if you can save money.
  • For New Homebuyers: While rising rates can make affordability a little tougher, the good news is that expected increase in housing inventory means you might have more options. This could help offset some of the impact of higher interest rates. It’s a balancing act, for sure.
  • Timing is Everything (But Predictable?): My best advice is to stay informed. Keep an eye on those economic reports, especially the jobs numbers and inflation data. These are the big influencers that will help predict where rates are headed in the immediate future. Don't rush into a decision, but don't wait so long that you miss a good opportunity either.

The Big Picture: Key Takeaways

To wrap it up, here's what I'm seeing today:

  • The 30-year fixed rate is at 5.92%, and the 15-year fixed is at 5.50%, both showing a slight upward trend.
  • Global events and concerns about inflation are playing a role, pushing up yields in the bond market.
  • The Federal Reserve is expected to keep interest rates steady for now, but their future plans are a key point to watch.
  • The promise of increased housing inventory in 2026 is a bright spot for the housing market.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, March 4, 2026: 30-Year Refinance Rate Drops by 8 Basis Points

March 4, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

For homeowners looking to trim their monthly mortgage payments, March 4, 2026, brings some welcome news: the 30-year fixed refinance rate has fallen to 6.40%, marking an encouraging decrease that offers a chance to lock in lower borrowing costs. Today, March 4, 2026, brings a bit of relief.

According to Zillow's data, the 30-year fixed refinance rate is now sitting at 6.40%. This is a nice drop, down by 12 basis points from yesterday and a solid 8 basis points lower than what we saw just last week. That might not sound like a huge amount, but over the life of a loan, those basis points can add up to significant savings.

Mortgage Rates Today, March 4: 30-Year Refinance Rate Drops by 8 Basis Points

What the Numbers Tell Us Today

Let's break down what's happening with the main types of refinance rates, again, based on Zillow's tracking today:

Loan Type Rate Change
30-Year Fixed Refinance 6.40% -12 bps (daily) / -8 bps (weekly)
15-Year Fixed Refinance 5.58% -1 bps (daily)
5-Year ARM Refinance 6.75% +4 bps (daily)

As you can see, while the longer-term fixed rates are dipping, the 5-year adjustable-rate mortgage (ARM) is ticking up. This is a good reminder that nothing stays exactly the same in the world of finance, and different loan types react to market shifts in their own ways.

Why Are Rates Moving Today?

It's easy to just look at the numbers and see an uptick or a downtick, but understanding the “why” can be more helpful. Several factors are at play, influencing these mortgage rate movements.

  • Global Ripples: Honestly, I've been keeping an eye on international events, and today was no different. Tensions in the Middle East are creating some nervousness in the financial markets. This can sometimes push investors towards safer options, and that often impacts Treasury yields, which, in turn, affect mortgage rates. So, even though our refinance rates are dropping, there's this underlying global pressure trying to push them up.
  • Treasury Yields are Key: My general rule of thumb is to watch the 10-year Treasury yield. It’s a really good indicator of where mortgage rates are headed. Today, it's hovering near 4.02%. When Treasury yields go up, mortgage rates usually follow, and when they go down, mortgage rates tend to follow suit. It’s a pretty direct correlation.
  • That “In the Money” Feeling: If you took out a mortgage in early 2025, or even before, when rates were higher than they are now (think above 7%), today's rates might feel like a breath of fresh air. This is what we call being “in the money” for a refinance. You’re in a position where refinancing to a lower rate can genuinely lower your monthly payment. It’s exciting when that opportunity presents itself.
  • The Fed's Steady Hand: The Federal Reserve is expected to hold steady on its key interest rate at its upcoming meeting in mid-March. This is something the markets have largely anticipated, meaning it's already “priced in.” So, while the Fed's decisions are crucial, for now, their upcoming pause isn't causing major rate swings.

My Thoughts: Is Refinancing Right for You?

As someone who's navigated the mortgage process more than once, I can tell you that refinancing isn't always a no-brainer, even when rates drop.

  • Know Your Break-Even Point: This is a big one. When you refinance, there are closing costs involved. These can be anywhere from 2% to 6% of your loan amount. You need to do the math to figure out how long it will take for your monthly savings to cover these upfront costs. If you plan to move or sell the house well before you hit that break-even point, refinancing might not save you money in the long run.
  • Your Credit Score Matters (A Lot): I always tell people to check their credit scores well in advance of thinking about refinancing. The best rates, the ones you see advertised, are usually reserved for borrowers with excellent credit. We're talking mid-700s or higher. If your score is lower, the rate you're offered might not be as attractive.
  • Consider Your Equity: Many homeowners today have a good chunk of equity in their homes. If you need to access some of that cash, you might want to think about a Home Equity Line of Credit (HELOC) instead of a full refinance. This lets you tap into your equity while keeping your original, potentially lower, primary mortgage rate intact. It’s a smart way to get cash without changing your main housing payment.

Looking Ahead: What's the Forecast for 2026?

Predicting the future of interest rates is always tricky, but the experts at institutions like Fannie Mae and the Mortgage Bankers Association (MBA) are generally expecting rates to stay relatively stable throughout the rest of 2026. They're forecasting an average somewhere around 6.1%.

While a dip to, say, 5.7% isn't entirely out of the question in the best-case scenario, it's highly unlikely we'll see a return to the incredibly low rates of the early 2020s. So, while today’s drop is great news, it's important to have realistic expectations for the rest of the year.

Quick Recap of Today's Mortgage News

To sum it all up:

  • The 30-year fixed refinance rate is currently at 6.40%, down from yesterday and last week.
  • The 15-year fixed refinance dipped slightly to 5.58%, while the 5-year ARM nudged up to 6.75%.
  • Global events and Treasury yields are key drivers of these rate movements.
  • Always calculate your break-even point and consider your credit score before refinancing.
  • The 2026 rate forecast points towards stability, with averages expected near 6%.

It's a dynamic market, but today’s numbers offer a positive sign for those looking to refinance. Keep an eye on these trends and do your homework to make the best decision for your financial situation.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 3, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 3: Rates Remain Below 6% Amid Heightened Global Volatility

March 3, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of today, March 3, 2026, the average 30-year fixed mortgage rate stands at 5.80%, showing a slight dip of one basis point from yesterday. However, this number, while seemingly stable, is happening within a surprisingly turbulent market, and it's crucial to understand why to make sense of owning a home right now.

Today's Mortgage Rates, March 3: Rates Remain Below 6% Amid Heightened Global Volatility

Key Takeaways for You

  • The 30-year fixed mortgage rate is currently at 5.80%, a minor decrease, while the 15-year fixed has nudged up to 5.39%.
  • Geopolitical tensions have caused Treasury yields to spike, usually a sign that mortgage rates will climb, even though the 30-year fixed saw a small dip today.
  • Rising oil prices and worries about inflation are currently having a bigger impact on the market than the typical “flight to safety” reaction to global events.
  • Despite today's jitters, the housing market fundamentals are still looking pretty good, with more homes potentially coming onto the market and buyers generally having more financial room to maneuver than last year.

For a moment, it looked like 2026 was shaping up to be a fantastic year for homebuyers. We were seeing rates dip below that often-talked-about 6% mark for the first time in ages. But as any seasoned observer of the financial world knows, things can change on a dime, and today is a prime example of that. The news from the Middle East has really shaken things up, causing a bit of a head-scratching reaction in the bond market that directly impacts what you'll pay for your mortgage.

How Today's Rates Stack Up (March 3, 2026)

Let's break down the numbers directly from Zillow, the source that tracks a lot of this crucial information:

Loan Type Current Interest Rate
30-Year Fixed 5.80%
20-Year Fixed 5.69%
15-Year Fixed 5.39%
5/1 ARM 5.86%
7/1 ARM 5.62%
30-Year VA 5.47%
15-Year VA 5.12%
5/1 VA 5.07%

Understanding the Key Rate Types

For anyone looking to buy or refinance, understanding these numbers is the first step.

  • 30-Year Fixed Mortgage: This is the old reliable, the most popular choice for a reason. It gives you a predictable payment for three decades. At 5.80%, it's still a decent rate, and it's holding steady for now. But keep an eye on it; the current global situation could push it higher if things don’t calm down soon.
  • 15-Year Fixed Mortgage: If you’re looking to build equity faster and want to be mortgage-free sooner, this is the way to go. The 5.39% rate is a bit higher than yesterday, but honestly, it's still really good when you look back at the highs we saw just a year or two ago. This loan type is perfect for those who can handle a higher monthly payment for a shorter period.
  • Adjustable-Rate Mortgages (ARMs): These can be tempting with their lower initial rates. The 5/1 ARM at 5.86% and the 7/1 ARM at 5.62% offer a good starting point, but it's about knowing the risk. If interest rates continue to bounce around, your payment could go up after the initial fixed period. It’s a gamble that might pay off, but you need to be prepared for the potential downsides.

The Geopolitical Ripple: Operation Epic Fury and the Bond Market

So, what’s making these rates do this interesting dance? The big news is the joint U.S.–Israeli military operation, Operation Epic Fury, against Iran, which kicked off on February 28, 2026. This has sent shockwaves through the financial world.

Normally, when something like this happens, you’d expect investors to get nervous and move their money into safer assets, like U.S. Treasury bonds. This usually drives bond prices up and their yields down, which in turn tends to lower mortgage rates. But this time, it’s different.

  • Treasury Yields Jump: Instead of going down, the 10-year Treasury yield actually jumped by more than 2% on Monday, reaching around 4.05%. This is a significant move and a strong indicator that mortgage rates are likely to follow suit, even if the 30-year fixed is only slightly down today.
  • Inflation Worries: Added to the geopolitical tension is the surge in oil prices, pushing towards $100 a barrel. This immediately brings back fears of inflation. When there's more worry about prices going up, central banks like the Federal Reserve tend to keep interest rates higher for longer to try and control it.
  • Escalation on the Ground: Reports are coming in about retaliatory strikes from Iran and expanded operations by Israel. This isn't just a little spat; it's an escalating conflict, and that kind of uncertainty makes the markets very jumpy.

A Look Back: The 2026 Housing Market Before Today

It’s easy to get caught up in today’s news, but it’s important to remember where we were just a few weeks ago. The start of 2026 was looking much brighter for the housing market.

  • More Homes Listing: For the first time in about five years, we've seen more homeowners with mortgage rates above 6% (about 21.2%) than those with super-low rates below 3% (around 20%). This is important because it means more people are feeling less “locked in” by their current mortgage and are more willing to sell their homes. This has been slowly helping to increase the number of available homes, which is great news for buyers.
  • Buying Power Boost: Zillow data earlier this year showed that as rates dipped, the average household's ability to buy a home increased by roughly $30,000 compared to last year. This made a lot of people feel optimistic about finding their dream home.

My Take on It All

From my perspective, watching these markets, it's a constant balancing act. We had such promising signs of recovery and affordability earlier in the year. The fact that geopolitical events and inflation fears are the dominant forces right now is a stark reminder that real estate doesn't exist in a vacuum.

The slight dip in the 30-year fixed is a bit of a curveball. Usually, you'd expect Treasury yields to pull mortgage rates up. This divergence suggests that maybe lenders are playing it conservative, or perhaps anticipating some future market easing. However, I wouldn’t get too comfortable. The underlying pressures of inflation and global instability are real, and they have a way of making their presence known in the long run.

For borrowers, this means being extra vigilant. If you were thinking of locking in a rate, now might be the time to talk to your lender seriously about what yesterday’s events could mean for your specific situation. Don't just look at the headline number; understand the factors influencing it.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

30-Year Fixed Mortgage Rate Drops Steeply by 78 Basis Points

March 3, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Drops Steeply by 78 Basis Points

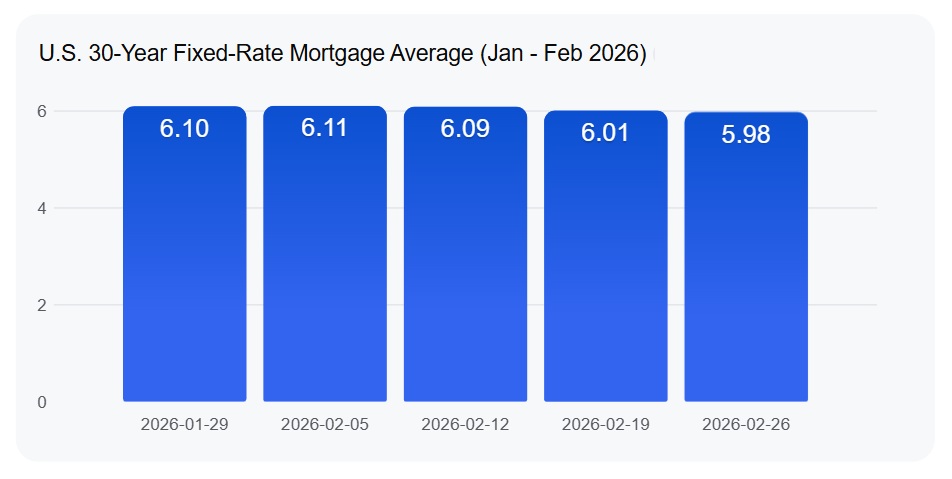
This is huge news for anyone dreaming of homeownership or looking to refinance their mortgage. The 30-year fixed mortgage rate has officially dipped below 6%, settling at a fantastic 5.98%, according to the latest, highly anticipated report from Freddie Mac. This milestone, the first time we’ve seen rates in the 5% range in about three and a half years, is more than just a number; it's a significant shift that could dramatically improve affordability and breathe new life into the housing market.

30-Year Fixed Mortgage Rate Drops Steeply by 78 Basis Points

While this week's change might seem modest, the year-over-year drop of a stunning 78 basis points represents a truly substantial improvement for borrowers. A drop like this isn't just a blip.

It feels like a turning point. After the rollercoaster of rising rates we’ve experienced, seeing the primary 30-year fixed mortgage rate fall this much represents a substantial win for potential and current homeowners. It’s like finally getting a bit of breathing room after holding your breath for too long. This decrease opens up doors that might have felt slammed shut just a few months ago.

A Significant Swing in Borrowing Costs

Let's break down what these numbers from Freddie Mac's Primary Mortgage Market Survey® actually mean for you.

The headline number, 5.98% for the 30-year fixed-rate mortgage, is significant. It's not just a little bit lower than last week; it's the lowest it’s been in a long time. While the weekly change from last week was a tiny decrease of just 3 basis points, the real story is in the big picture. Compared to this time last year, when rates were hovering much higher, we’ve seen a dramatic decrease of 78 basis points. To put that into perspective, that's nearly a full percentage point drop in your borrowing cost.

U.S. 30-Year Fixed-Rate Mortgage Average (Jan - Feb 2026)

Think about it: last year, the average rate was closer to 6.76%. That means the cost of borrowing the same amount of money has gone down considerably. This doesn't just make buying a new home more accessible; it also makes refinancing your existing mortgage to a lower rate incredibly attractive.

The 15-year fixed mortgage rate also offers good news, although with a slightly different weekly trend. It's currently at 5.44%. While it ticked up a bit this week by 9 basis points, it's still a full 50 basis points lower than it was a year ago. This reinforces the overall trend: despite minor weekly ups and downs, the general direction for mortgage rates has been downward over the past year.

Decoding the Impact: What the Rate Drop Means for Your Wallet

This isn't just about numbers on a screen; it's about tangible savings and increased possibilities. Let's look at a quick comparison:

Loan Type Current Rate (Feb 26, 2026) Rate Last Year (Approx.) Yearly Change Potential Monthly Savings (on $400k Loan)
30-Year Fixed 5.98% 6.76% -78 bps (-0.78%) Approximately $135 per month
15-Year Fixed 5.44% 5.94% -50 bps (-0.50%) Approximately $70 per month

Note: Monthly savings are estimates based on a $400,000 loan amount and may vary based on loan terms and specific lender rates.

When you're talking about a 78 basis point drop on a 30-year mortgage, the savings add up incredibly quickly over the life of the loan. For a $400,000 mortgage, a difference of 0.78% can mean saving thousands, if not tens of thousands, of dollars. The thought of saving $135 more each month at 5.98% compared to, say, 6.5% is enough to make a big difference for families budgeting for a new home. It’s this kind of substantial shift that can make or break a home purchase for many people.

Why This “5-Handle” Matters So Much

Here's why this rate falling below 6% is so important. It's not just a little bit lower; it's a psychological benchmark that many buyers and sellers have been waiting for.

  • The “5-Handle” Effect: For years, we've seen rates climb into the 6% and even 7% range. Seeing a rate with a “5” in front of it, like 5.98%, has a powerful psychological impact. It makes the idea of buying or refinancing feel much more achievable for people who might have been priced out or hesitant. I've seen firsthand how a round number like this can encourage people to finally make a move.
  • Unlocking the Market: Many homeowners who got mortgages during the super-low rate environment of the pandemic have been hesitant to sell. They might have a 3% rate and are understandably reluctant to trade it for a 7% rate. However, as rates drop closer to the 6% mark, that difference becomes smaller, potentially freeing up more homes for sale. This could lead to a much-needed increase in housing inventory.
  • Perfect Timing for Spring: This rate drop comes at an ideal time, just as we head into the traditionally busy spring homebuying season. More buyers looking and potentially more homes coming onto the market? That’s a recipe for a more active and vibrant real estate market. I'm expecting this to be a really strong spring for home sales.
  • Boosting Purchasing Power: Experts estimate that a drop of this magnitude can significantly increase a household's purchasing power. For the average U.S. household, this could mean they can afford a significantly more expensive home than they could a year ago. The National Association of REALTORS® suggests that over a million more households could qualify for a mortgage nationally. This is incredibly empowering for first-time buyers.
  • Refinancing Frenzy: For those who already own homes and perhaps bought or refinanced at higher rates in the past year or two, now is the time to seriously look at refinancing. Those who bought at rates of 7% or higher could see substantial savings by refinancing to this new 5.98% rate. We've already seen an uptick in refinance activity, and this news will likely push that even higher.

My Take: A Welcome Shift for Buyers and the Economy

As someone who works with people navigating the mortgage process, I find this news incredibly encouraging. The Federal Reserve's recent rate cuts and government initiatives to support the housing market are clearly having a positive effect. Seeing the 30-year fixed mortgage rate fall below 6% is a clear sign that the market is responding, and more importantly, that borrowers are getting a break.

This isn't just about getting a slightly better deal; it's about restoring balance and accessibility to the housing market. It’s about giving families the chance to achieve their homeownership dreams and helping existing homeowners improve their financial situations. If you've been on the fence about buying or refinancing, I strongly suggest you talk to your lender about what these new rates could mean for you. The savings are real, and the opportunity is here.

🏡 Two Investment Opportunities With Cash Flow

Bessemer, AL
🏠 Property: Blue Jay Cir
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1610 sqft
💰 Price: $282,000 | Rent: $1,885
📊 Cap Rate: 6.4% | NOI: $1,500
📅 Year Built: 2023
📐 Price/Sq Ft: $176
🏙️ Neighborhood: A-

And

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

Alabama’s newer A- rental vs Tennessee’s larger property with higher NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

5 Steps to Secure the Lowest Mortgage Rates in 2026

March 3, 2026 by Marco Santarelli

5 Steps to Secure the Lowest Mortgage Rates in 2026

Are you dreaming of owning a home or refinancing in 2026? The thought of navigating mortgage rates can feel a bit daunting, can't it? But let me assure you, securing the lowest mortgage rates in 2026 is absolutely within your reach if you start preparing now, armed with a clear strategy, a strong credit profile, and a willingness to explore all your options.

Despite projections that 30-year fixed rates might average anywhere from 5.5% to 6.4%, being proactive and informed will give you a significant advantage in locking in a rate that works best for you.

For many, a mortgage is the biggest financial commitment of their lives. It's not just about finding a house; it's about making smart decisions that can save you tens, even hundreds, of thousands of dollars over the lifetime of your loan. As someone who's observed countless home-buying journeys, I can tell you that the difference between an average rate and a truly competitive one often comes down to these five crucial steps.

Don't just dream of lower rates; plan for them. Here’s how you can position yourself to get the best deal on your mortgage in 2026.

5 Steps to Secure the Lowest Mortgage Rates in 2026

1. Optimize Your Credit Profile

When a lender looks at your mortgage application, your credit score is one of the very first things they check. It’s like their crystal ball, telling them how reliable you are at paying back debts. My experience tells me that a strong credit score isn't just a number; it's a golden ticket to the best interest rates. While you can certainly qualify for a mortgage with a lower score, the absolute most competitive rates in 2026 are likely to be reserved for those who boast a score of 780 or higher.

Here’s what you need to do:

  • Review Your Credit Reports: This is non-negotiable. I always advise my friends and family to pull their reports from AnnualCreditReport.com at least once a year. Look for any errors or inaccuracies. Mistakes happen, and disputing them can sometimes boost your score by a significant 30-40 points. Imagine that – a simple check could save you a fortune!
  • Manage Credit Utilization: This is a big one. Your credit utilization is how much credit you're using compared to your total available credit. Lenders prefer to see this number kept below 30%. For example, if you have a credit card with a $10,000 limit, try to keep your balance under $3,000. High utilization signals that you might be over-reliant on credit, which lenders see as a risk.
  • Avoid New Accounts: In the 6-12 months leading up to your mortgage application, try to avoid opening any new credit accounts, whether it's a new credit card or an auto loan. Each new application can cause a small, temporary dip in your score, and a new account means a shorter average age of accounts, which can also negatively impact your credit history. Stay disciplined and let your existing good habits shine through.

2. Maximize Your Down Payment

A larger down payment is a powerful tool in your quest for the lowest mortgage rates. Think of it this way: the more money you put down upfront, the less money you need to borrow, and the less risk the lender takes on. This reduced risk often translates directly into a lower interest rate for you.

The “20% Rule” and Beyond:

  • Avoid PMI: The gold standard has long been to aim for at least 20% down. Why? Because hitting this mark usually helps you avoid Private Mortgage Insurance (PMI). PMI is an extra monthly fee, typically costing 0.5% to 1.5% of your loan amount annually, that protects the lender, not you. Skipping PMI can save you hundreds of dollars each month, which ultimately means you can afford more house without stretching your budget. It’s a definite win.
  • Every Bit Helps: I often meet people who feel discouraged if they can’t hit that 20% mark. But here's what I’ve learned: even if 20% isn't feasible, don’t give up. Any increase in your down payment – for example, moving from 3% to 10% – can significantly improve your position and qualify you for better rate tiers. Each additional percentage point you put down shows the lender your commitment and financial strength, and they often reward that with a more attractive rate. Start saving aggressively, and every dollar will count.

3. Shop at Least Three Different Lenders

This step is, in my opinion, one of the most overlooked and yet most impactful actions you can take. It’s a common mistake to simply go with your existing bank’s first offer, but please don't fall into that trap! Just like you wouldn't buy the first car you see, you shouldn't settle for the first mortgage offer you receive. Mortgage rates can vary significantly from one lender to another.

Don't Leave Money on the Table:

  • Explore Your Options: Big banks, local credit unions, and online lenders all have different underwriting standards, fee structures, and, crucially, different rates. What one lender offers, another might beat. I’ve seen borrowers save thousands of dollars simply by taking the time to compare. Research shows that borrowers who compare multiple lenders can save up to $44,000 over the life of a 30-year loan. That's a staggering amount of money just for making a few phone calls or filling out a few online forms.
  • Focus on APR: When comparing offers, don't just look at the interest rate. My advice is to focus on the Annual Percentage Rate (APR). The APR gives you a more complete picture of the loan’s true cost because it includes not only the interest rate but also most associated fees and closing costs. This lets you make a true apples-to-apples comparison and ensures you’re not surprised by hidden fees down the road. Demand a Loan Estimate from each lender you consider; it makes comparison straightforward.

4. Utilize Strategic “Buydowns” and Points

When you have some extra cash upfront, you can actually “buy” a lower interest rate through something called discount points or buydowns. This might sound a bit like paying for an admission ticket, but it's a very real and effective strategy to reduce your long-term costs.

Here’s how it works:

  • Discount Points: A discount point is typically equal to 1% of your total loan amount. For example, on a $300,000 mortgage, one point would cost you $3,000. In exchange for this upfront payment, lenders will usually reduce your interest rate by roughly 0.25% for the life of the loan. This strategy makes the most sense if you plan to stay in your home for many years, as you'll have ample time to “break even” on the upfront cost through lower monthly payments.
  • Seller Concessions for Buydowns: In what I anticipate will be a more balanced market in 2026, you might find sellers more willing to negotiate. This opens the door for negotiating seller concessions to pay for a temporary rate buydown. A common example is a 2-1 buydown. This means your interest rate is 2% lower than the permanent rate for the first year, 1% lower for the second year, and then settles at the permanent rate from the third year onward. This can provide significant relief in those crucial initial years of homeownership, allowing you to settle in without the full brunt of the mortgage payment right away. It's a clever negotiation tactic that savvy buyers should definitely explore.

5. Consider Alternative Loan Structures

While the 30-year fixed-rate mortgage is the most popular choice for a reason – its predictability and stable payments – it's not the only game in town. Depending on your financial goals and how long you plan to stay in the home, other loan structures might offer you significantly lower initial rates in 2026.

Explore these options:

  • 15-Year Fixed-Rate Mortgage: If you're comfortable with a higher monthly payment, a 15-year fixed mortgage typically offers rates 0.5% to 0.75% lower than a 30-year term. You'll pay off your home faster, save a massive amount on interest over the life of the loan, and build equity at a much quicker pace. It’s a fantastic option for those with stable income and a desire to be debt-free sooner.
  • Adjustable-Rate Mortgages (ARMs): An ARM might sound scary to some, but they can be a smart choice under the right circumstances. ARMs typically offer a significantly lower introductory rate for a set period (e.g., 5, 7, or 10 years) before the rate adjusts periodically. If you know you plan to sell your home or refinance within that initial fixed-rate period (say, within 5 to 10 years), an ARM could save you a good deal of money in interest during those first few years. Just be sure to understand the terms and potential adjustments.
  • Assumable Mortgages: This is a lesser-known gem! Some existing mortgages, specifically FHA, VA, or USDA loans, are assumable. This means that if a seller has one of these loans, you might be able to “assume” their existing mortgage and its original interest rate. Given the lower rates from previous years, this could mean securing a rate potentially below 5% – a significant advantage in a higher-rate environment. This option requires finding sellers with these specific loan types and working through the unique assumption process, but the savings can be truly substantial.

Your Journey to the Lowest Mortgage Rates in 2026

Securing the lowest mortgage rates in 2026 isn't about luck; it's about preparation, diligence, and informed decision-making. By taking these five steps – optimizing your credit, maximizing your down payment, shopping multiple lenders, understanding buydowns, and exploring alternative loan options – you're not just hoping for a good rate; you're actively creating the conditions for one. Start today, put in the work, and position yourself to achieve your homeownership dreams on the best financial terms possible.

🏡 Two Turnkey Investment Opportunities With Strong Cash Flow

Bessemer, AL
🏠 Property: Blue Jay Cir
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1610 sqft
💰 Price: $282,000 | Rent: $1,885
📊 Cap Rate: 6.4% | NOI: $1,500
📅 Year Built: 2023
📐 Price/Sq Ft: $176
🏙️ Neighborhood: A-

And

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

Alabama’s newer A- rental vs Tennessee’s larger property with higher NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Assumable Mortgage, mortgage, mortgage rates

How to Get a 3% Mortgage Rate in 2026?

March 3, 2026 by Marco Santarelli

How to Get a 3% Mortgage Rate in 2026?

Securing a 3% mortgage rate in 2026 might sound impossible in today’s market, but it’s entirely achievable through assumable mortgages. These loans allow buyers to take over the seller’s existing mortgage terms—often locked in years ago when rates were much lower. Instead of waiting for lenders to cut rates, savvy buyers can step into favorable financing from the past, making assumable mortgages one of the most practical strategies for reducing borrowing costs today. So let’s dive in and see exactly how you can secure a 3% interest rate in 2026.

How to Get a 3% Mortgage Rate in 2026 — The Assumable Mortgage Hack

Why a 3% Interest Rate Feels Like a Miracle (And How to Get It)

Let's be real. Right now, a 30-year fixed mortgage is hovering somewhere around 6%. That's a big number, and it makes homeownership feel like an uphill battle. For every 1% you can shave off that interest rate, your buying power jumps by about 10%. So, grabbing a 3% rate instead of a 6% one is like getting a huge discount on your monthly payments – a solid 30% cheaper! It sounds almost too good to be true, but it's not. It's about understanding a specific type of mortgage that most people overlook.

The “DNA” of a 3% Mortgage: What to Look For

Not all mortgages are created equal when it comes to this cool trick. You can't just assume any loan you find. To get that sweet 3% interest rate, you need to target homes with specific types of government-backed loans. Those super common conventional loans from Fannie Mae and Freddie Mac? They're almost never assumable. Instead, keep your eyes peeled for these:

  • FHA Loans: These are everywhere and are usually assumable. You'll still need to meet standard credit requirements, but it's a straightforward process once you find a home with one.
  • VA Loans: If you want the lowest rates, this is often it. I've seen these dip below 3%! Here's a crucial tip: You don't have to be a veteran to assume a VA loan. However, it's worth noting that the seller might temporarily lose their “entitlement” until the loan is paid off.
  • USDA Loans: These are typically found in more rural or suburban-fringe areas. They're also assumable, but you might need to check if your household income fits within their limits.

Beyond Zillow: Finding “Assumable” Listings

You know how sometimes the most important details are hidden in the tiny print? That's often the case with assumable mortgages on big real estate sites. Sites like Zillow or Redfin might mention it, but it can be buried deep. My advice for 2026? Use tools specifically designed for this niche:

  • Roam: This platform is built to filter listings specifically for assumable mortgages. Even better, they help with the tricky paperwork involved in transferring the loan from the seller to you.
  • AssumeList: This is a fantastic database that tracks properties with FHA and VA loans. You can often see the seller's exact interest rate before you even connect with a real estate agent. Talk about being prepared!
  • Keyword Power: On the traditional sites, don't underestimate the power of a good keyword search. Try terms like: “assumable,” “3% rate,” “VA assumption,” or “FHA assumption.” This can help surface those hidden gems.

The Equity Gap: The Biggest Hurdle (and How to Leap It)

Okay, so you've found the perfect house with a 3% mortgage. Awesome! But here's where most people get stuck: the equity gap. Let's say the house is worth $550,000, but the seller's outstanding mortgage balance at 3% is only $350,000. That leaves a $200,000 gap you need to cover. How do you do it?

  1. Cash is King: If you've sold another home and have some serious cash reserves, this is the most straightforward way to bridge the gap.
  2. A Second Mortgage: This is where the math really starts to shine. You can get a second mortgage or a home equity loan for that $200,000 difference. Even if this second loan has a higher rate, say 8%, your blended rate (the average of your 3% first loan and your 8% second loan) will still be way lower than taking out a brand-new 6% mortgage.
  3. Seller Financing: Some sellers are really motivated to sell, especially if their house has been sitting on the market. They might be willing to “carry” a portion of the equity as a private loan. This means you pay them back directly over time. It’s a win-win if you can negotiate it.

The “Hidden” Closing Process: It's Different!

Found your 3% dream home? Great! Now, here's a key difference: you won't be going to your bank for the loan. You'll be working with the seller's bank. Here’s what to expect:

  • Timeline: Be patient. A standard new mortgage process takes about 30 days. An assumption can take 60 to 90 days. Why? Because the seller's bank doesn't have the same financial incentive to rush a low-interest loan for someone new.
  • Your Credit Still Matters: Don't get too relaxed! The bank will absolutely vet you. They need to make sure you're financially stable, so expect them to check your income and credit score just like any other lender.
  • Seller's Peace of Mind: This is important for everyone. Make sure your purchase contract clearly states that you require a formal “Release of Liability” for the seller. This ensures their credit won't be on the line for your future payments.

Why This is the “Gold Mine” of 2026

Honestly, I see this as one of the smartest ways to navigate the housing market in the coming years. The savings are significant. Taking that assumed 3% loan instead of a new 6% one on a typical mortgage can save you thousands annually.

Here’s a quick look at the math:

Let's say you're eyeing a $500,000 home. The seller has an assumable loan of $300,000 at 3%, leaving a $200,000 equity gap.

  • Option A: New 2026 Mortgage
    • Loan Amount: $500,000
    • Interest Rate: 6%
    • Estimated Monthly Payment (Principal & Interest): $2,998
  • Option B: Assumed “Blended” Mortgage
    • Assumed Loan: $300,000 @ 3% = $1,265/mo
    • Second Loan (for equity gap) @ 7% = $1,331/mo
    • Total Estimated Monthly Payment: $2,596

See that? That's a monthly savings of $402, which adds up to $4,824 a year! Your effective blended rate here is around 4.6% – still significantly lower than a new loan.

Pro Tip: Don't shy away from listings that have been on the market for more than 60 days. These sellers are often eager to make a deal and might not even realize their assumable mortgage is their most valuable asset. It’s definitely worth exploring!

🏡 Two Turnkey Investment Opportunities With Strong Cash Flow

Bessemer, AL
🏠 Property: Blue Jay Cir
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1610 sqft
💰 Price: $282,000 | Rent: $1,885
📊 Cap Rate: 6.4% | NOI: $1,500
📅 Year Built: 2023
📐 Price/Sq Ft: $176
🏙️ Neighborhood: A-

And

Lebanon, TN
🏠 Property: Baltusrol Lane #852
🛏️ Beds/Baths: 4 Bed • 2.5 Bath • 2011 sqft
💰 Price: $369,990 | Rent: $2,400
📊 Cap Rate: 5.8% | NOI: $1,789
📅 Year Built: 2024
📐 Price/Sq Ft: $184
🏙️ Neighborhood: B

Alabama’s newer A- rental vs Tennessee’s larger property with higher NOI. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: Assumable Mortgage, mortgage, mortgage rates

Mortgage Rates Today, March 3, 2026: 30-Year Refinance Rate Drops by 4 Basis Points

March 3, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Tuesday, March 3, 2026, the 30-year fixed refinance rate has dipped to 6.44%, marking a welcome, albeit modest, decrease of 4 basis points from the previous week's average. This slight easing offers a hopeful sign for homeowners looking to potentially lower their monthly mortgage payments after a period of considerable market fluctuation.

Mortgage Rates Today, March 3, 2026: 30-Year Refinance Rate Drops by 4 Basis Points

A Closer Look at Today's Mortgage Rates

It's always a bit of a rollercoaster keeping up with mortgage rates, isn't it? One day they nudge up, the next they ease back down. Today, we're seeing a bit of good news for those eyeing a refinance on their 30-year fixed mortgage. According to Zillow's latest report, that popular loan option has settled at 6.44%. This is a slight improvement from last week's average of 6.48%, and a 3 basis point drop just within the last day. While it might not sound like a huge shift, for many families, shaving off even a quarter of a percent can translate into significant savings over the life of their loan.

However, not all news is uniformly positive across the board. The 15-year fixed refinance rate, another popular choice for its quicker payoff and slightly lower interest, has seen a minor increase, moving from 5.47% to 5.50%. This is a small bump of 3 basis points, but it’s worth noting for anyone comparing these two loan types.

The real story for today, though, is the significant jump in the 5-year adjustable-rate mortgage (ARM) refinance rate. This rate has climbed a substantial 38 basis points, going from 6.74% to a rather steep 7.12%. This highlights a common trend: while fixed rates offer more predictability, ARMs can be much more sensitive to market shifts, and today we're seeing that volatility play out.

Here’s a quick snapshot of what mortgage rates are looking like today:

Loan Type Rate Change (Day / Week)
30-Year Fixed Refinance 6.44% –3 bps / –4 bps
15-Year Fixed Refinance 5.50% +3 bps
5-Year ARM Refinance 7.12% +38 bps

Source: Zillow

What's Driving These Numbers?

It’s never just one thing, is it? The mortgage market is complex, influenced by a mix of economic indicators, global events, and even political shifts. This morning, a few key factors seem to be at play:

  • The Federal Reserve and Future Policy: There's a lot of quiet speculation about what comes next with the Federal Reserve. Jerome Powell's term is ending in May 2026, and President Trump has put forward Kevin Warsh as his nominee for the top spot. Warsh is generally seen as someone who might favor quicker interest rate cuts down the line. This expectation of future easing, even if not immediate, can sometimes provide a floor beneath mortgage rates, preventing them from climbing too high.
  • Geopolitical Tensions and Treasury Yields: We can't ignore the impact of global events. Recent military actions in Iran have definitely caused some ripples. On March 2nd, the 10-year Treasury yield—which is a huge factor in mortgage rate movements—jumped by more than 2%. While today's mortgage rates managed to dip, this underlying pressure from the Treasury market is a reminder that international events can, and do, affect our daily borrowing costs.
  • A Surge in Refinance Activity: It's encouraging to see that homeowners are actively looking to refinance. The Mortgage Bankers Association is reporting a massive 150% increase in refinance applications year-over-year. This tells me that many people are still remembering the much higher rates from 2024 and 2025 and are eager to take advantage of any opportunity to secure a better deal. This demand can also influence rate movements, but right now, it seems the slight downward trend in the 30-year fixed is a primary driver.

What Do the Experts See Ahead?

Forecasting mortgage rates is notoriously tricky, but various organizations offer their best guesses. Here’s a peek at what some are expecting for 2026:

Organization Q1 2026 Forecast (30-Year) Full Year 2026 Outlook
Fannie Mae 6.10% 6.0% – 6.1%
MBA 6.20% 6.10%
Morgan Stanley 5.75% 5.50% – 5.75% (mid-year low)
Bankrate 6.10% 5.7% – 6.5% range

As you can see, there's a range of predictions, with some anticipating rates to hover around 6%, while others, like Morgan Stanley, see potential for a mid-year dip closer to the mid-5% range. This diversity in forecasts underscores the inherent unpredictability of the market.

For Homeowners: Should You Refinance Now?

My personal take is that if your current mortgage rate is at least 1% higher than what's available today for a similar loan type, it’s definitely worth exploring a refinance. The savings can be quite substantial, even with the closing costs involved.

The “lock-in effect” that we've discussed so much in recent years, where homeowners were hesitant to move or refinance because their existing rate was so low, seems to be easing. More and more people are finding themselves with rates above 6%, meaning refinancing into today's market, even if it’s not a record low, can still make financial sense.

However, always remember that rates can change quickly. We’re heading into March 11th, which brings the next crucial CPI inflation data. This report is a big one and can significantly influence the Federal Reserve’s upcoming decisions. Keep an eye on this, as well as any further international developments, because they have the power to shift mortgage rates quite rapidly.

Key Takeaways for Today:

  • The 30-year fixed refinance rate has moved favorably, settling at 6.44%, down 4 basis points over the past week.
  • While fixed rates saw a slight mixed performance, the 5-year ARM refinance rate surged significantly to 7.12%.
  • Geopolitical events and shifts in Federal Reserve leadership are key influences on market sentiment.
  • Demand for refinancing is incredibly strong, with applications showing a 150% year-over-year surge.
  • It’s a good time to review your mortgage if your current rate is considerably higher, but stay informed about upcoming economic data, especially inflation reports.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Invest Smart — Build Long-Term Wealth Through Turnkey Real Estate in 2026

Market forecasts suggest steady demand, making turnkey real estate one of the most reliable paths to passive income and wealth creation.

Norada Real Estate helps investors capitalize on these trends with turnkey rental properties designed for appreciation and consistent cash flow—so you can grow wealth securely while others wait for clarity in the market.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Send Us An Email or Request a Call Back

Contact Us

Recommended Read:

  • 30-Year Fixed Refinance Rate Trends – March 1, 2026
  • Best Time to Refinance Your Mortgage: Expert Insights
  • Should You Refinance Your Mortgage Now or Wait Until 2026?
  • When You Refinance a Mortgage Do the 30 Years Start Over?
  • Should You Refinance as Mortgage Rates Reach Lowest Level in Over a Year?
  • Half of Recent Home Buyers Got Mortgage Rates Below 5%
  • Mortgage Rates Need to Drop by 2% Before Buying Spree Begins
  • Will Mortgage Rates Ever Be 3% Again: Future Outlook
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, March 2: Rates at Lowest Levels Spark Buyer Optimism

March 2, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

The mortgage market on March 2, 2026, is offering some of the most attractive borrowing costs we've seen in years. If you're thinking about buying a home or refinancing, the numbers are definitely worth paying attention to. To put it simply, today's 30-year fixed mortgage rate is averaging 5.81%, and the 15-year fixed mortgage rate has dipped to a remarkable 5.32%. This is significant news, especially as we head into the busy spring homebuying season.

Today's Mortgage Rates, March 2: Rates at Multi‑Year Lows Spark Buyer Optimism

Let's break down what these numbers look like across different loan types. Zillow's data for March 2, 2026, paints a clear picture:

Loan Type Current Interest Rate
30-Year Fixed 5.81%
20-Year Fixed 5.76%
15-Year Fixed 5.32%
5/1 ARM 5.82%
7/1 ARM 5.88%
30-Year VA 5.41%
15-Year VA 5.04%
5/1 VA 5.01%

As you can see, the 30-year fixed, the most popular choice for many Americans, is comfortably below 6%. The 15-year fixed is even lower, offering a fantastic opportunity to pay off your home faster. Even the VA loans, which are designed to help our nation's veterans, are showing incredibly competitive rates.

What's Driving This Drop in Mortgage Rates?

It's not just a random fluke that rates have fallen so dramatically. Several key factors are working together to push borrowing costs down:

  • Strategic Moves in the Bond Market: In early 2026, the Trump administration made a significant move by directing Fannie Mae and Freddie Mac to actively purchase mortgage-backed securities (MBS). We're talking about a $200 billion injection into this market. Think of it this way: when more people (or in this case, government-backed entities) are buying up mortgages, the demand for them goes up. This demand narrows the gap between what mortgage lenders can get for your loan and what they have to pay to borrow money themselves (often tied to Treasury yields). This allowed lenders to lower their rates even without a direct boost from the Federal Reserve in February.
  • Inflation is Cooling Off: The good news on the inflation front continues. Recent data suggests that inflation is steadily moving closer to the Federal Reserve's target of 2%. At the same time, the labor market, while still strong, is showing signs of moderating. When inflation is under control and the job market isn't overheating, it signals to the economy that borrowing money might be a bit less risky. This, in turn, pushes down the yields on longer-term investments like bonds, which directly impacts mortgage rates.
  • Looking Ahead to Future Fed Actions: The Federal Reserve is playing a strategic role. After making three interest rate cuts in 2025, they held steady at their first meeting of 2026. However, the financial markets are already anticipating that more cuts are on the horizon later this year. This expectation of future lower interest rates has a ripple effect, putting downward pressure on long-term rates, including the 10-year Treasury yield, which is a key benchmark for mortgage rates.
  • A Global Search for Safety: In times of global uncertainty, investors often flock to what they consider safe havens. U.S. Treasury bonds are widely viewed this way. Increased demand for these safe assets drives their prices up and, consequently, their yields down. This global trend of seeking stability in U.S. debt contributes to those lower mortgage rates we're seeing.

A Look at the Weekly Trends

The downward movement isn't just a one-off event; it's been a consistent trend.

  • The 30-Year Fixed Mortgage: At 5.81%, this rate is down over 11 basis points from the previous week. This is the lowest we've seen in more than three years, making it a very attractive option for many.
  • The 15-Year Fixed Mortgage: Hitting 5.32% is a big deal. This is the lowest point for this loan type since 2022. It means borrowers can build equity much faster while paying less in interest over the life of the loan.
  • Adjustable-Rate Mortgages (ARMs): While ARMs like the 5/1 ARM at 5.82% and the 7/1 ARM at 5.88% are still competitive, the current stability and attractiveness of fixed-rate options are making them the go-to for many buyers. When fixed rates are this low, the predictability of them is a huge advantage.

What This Means for You: Borrowers and Homeowners

These lower mortgage rates have significant implications depending on your current situation:

  • For Homeowners Looking to Refinance: If you took out a mortgage in 2024 or 2025 when rates were higher (think 7% or more), now is an absolutely prime time to consider refinancing. Even a drop of 1% on a $340,000 loan can save you well over $2,000 annually in interest payments. That's money that can go back into your pocket or be used for other financial goals. I've seen many homeowners put off refinancing, thinking it's too much hassle, but the savings now are substantial enough to make it very much worth exploring.
  • For Prospective Homebuyers: The improved affordability is a game-changer. Not only are the monthly payments lower, but this could also mean more competition in the housing market. Builders are still actively offering incentives like rate buydowns, which can further sweeten the deal and make homeownership even more accessible. If you've been waiting on the sidelines, now might be the time to jump in.
  • Thinking About the Market's Future: The general consensus from major forecasters, including Fannie Mae and the National Association of Realtors (NAR), is that we'll likely see rates hovering around or even below 6% for the rest of 2026. This “sub-6%” environment is expected to act like a gentle nudge, encouraging those “locked-in” homeowners who might be hesitant to sell because of their current low rates to finally list their homes. It also provides a much-needed boost for first-time buyers who are looking for that entry point into the market. My sense is that this could lead to a more balanced and active spring season than we've seen in a few years.

Key Takeaways from Today's Mortgage Rates

  • We are currently experiencing multi-year lows in mortgage rates, with the benchmark 30-year fixed rate at 5.81% and the 15-year fixed at 5.32%.
  • Several factors are contributing to this positive trend, including Federal intervention in the bond market, cooling inflation, and global geopolitical stability driving safe-haven demand for U.S. bonds.
  • Homeowners with existing higher-rate mortgages have a strong refinancing opportunity.
  • Buyers should be prepared for potentially increased activity and competition as affordability improves, especially with the spring homebuying season approaching.

🏡 Two Texas Rental Properties With Strong Cash Flow

Cibolo, TX
🏠 Property: Columbia Dr
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1758 sqft
💰 Price: $245,000 | Rent: $1,795
📊 Cap Rate: 5.2% | NOI: $1,052
📅 Year Built: 2007
📐 Price/Sq Ft: $140
🏙️ Neighborhood: A

VS

San Antonio, TX
🏠 Property: Burning Lamp
🛏️ Beds/Baths: 3 Bed • 2 Bath • 1415 sqft
💰 Price: $237,500 | Rent: $1,750
📊 Cap Rate: 5.4% | NOI: $1,069
📅 Year Built: 2012
📐 Price/Sq Ft: $168
🏙️ Neighborhood: A

Two Texas rentals in A‑rated neighborhoods—Cibolo’s larger home vs San Antonio’s newer build with stronger cap rate. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

  • « Previous Page
  • 1
  • …
  • 45
  • 46
  • 47
  • 48
  • 49
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Interest Rate Predictions for the Next 2 Years: 2026-2028
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 15, 2026Marco Santarelli
  • 10-Year Treasury Yield Hits 5% — Highest Since 2007
    September 15, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...