Bond traders did not need Wednesday’s Federal Reserve decision to invent a Fed path — they needed it to confirm one. After a unanimous +25 bp hike that lifted the federal funds target to 3.75%–4.00%, the updated Summary of Economic Projections pointed toward roughly one more hike in 2026 (a year-end range near 4.00%–4.25%), and Chair Kevin Warsh’s press conference kept the emphasis on sticky inflation and firmer policy. The front end of the Treasury curve — especially the 2-year note — is where that story gets priced first.
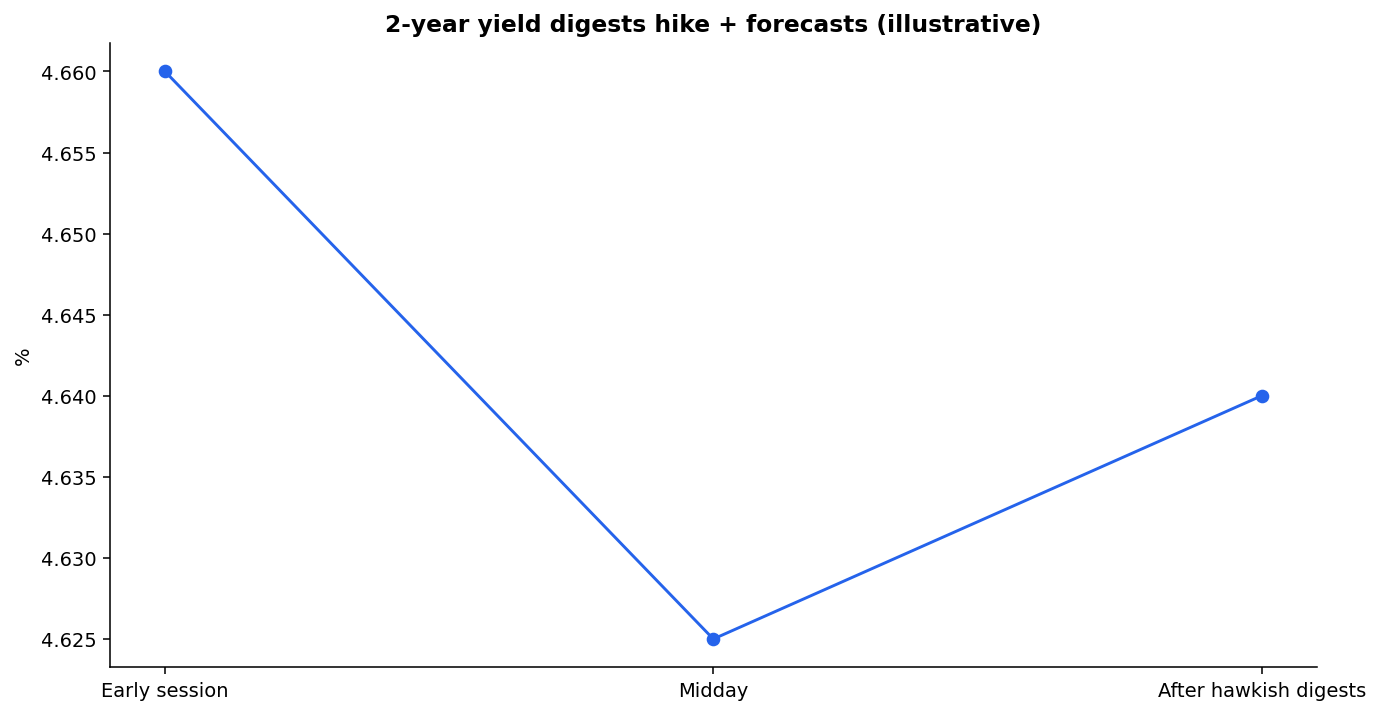
The headline framing for this piece keeps the published H1 about the 2-year reversing early gains. The accurate tape from available session reports is more nuanced: early Wednesday trade saw the 2-year yield ease a few basis points (one widely cited morning snapshot had it down about 3.6 bp near 4.625%) after a multi-day run toward the mid-4.60s and recent highs, then traders spent the afternoon adjusting to hawkish forecasts rather than celebrating a one-and-done cut cycle. We will not invent tick-by-tick closes we cannot verify; we will explain what the 2-year is telling you about the Fed path — and why that matters for mortgages even though the 10-year does more of the payment heavy lifting.
Two Year Treasury Yield Reverses Early Gains as Bond Traders Adjust to Hawkish Fed Forecasts
What the 2-year actually prices
If the federal funds rate is the overnight policy lever, the 2-year Treasury yield is the market’s rolling forecast of where that lever sits over the next several meetings. It embeds:
- The current funds range (now 3.75%–4.00%)
- Odds of additional hikes or cuts at upcoming FOMC dates
- A term premium and risk buffer for surprises in inflation and growth data
That is why hawkish dots move the 2-year even when the day’s 25 bp hike was fully telegraphed. The hike was the base case. The path was the trade.
What we can say about Wednesday’s tape (without fake ticks)
Public session commentary through the Fed day supports this sequence:
| Window | Reported 2-year context | Market read |
|---|---|---|
| Days into the meeting | 2-year near recent highs in the mid-4.60% area (examples around 4.65%–4.69% on the approach) | Hike odds already high; path being priced tighter |
| Wednesday morning | Yield eased in early trade (about −3.6 bp near 4.625% in one live snapshot) | “Early gains” in bond prices / softer yields ahead of the 2 p.m. package |
| Statement + SEP | Unanimous +25 bp; median path toward ~4.00%–4.25% by end-2026; 16 of 18 officials seeing at least one more hike this year | Confirms restrictive follow-through risk |
| Warsh press conference | Inflation still elevated; financial conditions not clearly restrictive going in; no soft “one and done” gift | Front-end stays sensitive to more firming |
Reuters noted that Treasury yields held largely steady into the announcement after already moving in anticipation — with the 10-year near ~4.95%–4.96% around the release after an earlier week spike above 5%. CME FedWatch-style odds for the next meeting also ticked slightly higher after the package. Together, that is a hawkish-adjustment story, not a dovish melt in front-end yields.
If your feed showed an early yield dip that later gave back as guidance landed, that pattern fits the H1’s “reverses early gains” language in bond-price terms. If your screen showed a choppy mid-4.60s hold, that still matches the economic point: traders did not take the hike as permission to price easy money.
Why hawkish forecasts hit the 2-year harder than the funds print
A 25 bp move that everyone expects is mostly in the price. What was not fully settled was whether September would look like:
- A single credibility hike, then a long pause
- The first step in a short re-tightening sequence into late 2026
The SEP leaned toward option two for the median participant. Warsh declined to prejudge meeting-by-meeting steps — consistent with his preference against heavy forward guidance — but he also framed the hike as removing accommodation while inflation remains too high. Bond desks translate that combination into higher odds that the funds rate stays elevated or edges higher, which is textbook 2-year material.
For the broader policy package, see our companions on the first hike in over three years and the dot plot’s signal of one additional 2026 hike.
2-year vs. 10-year: different jobs on your mortgage quote
| Yield | Primary job | Housing relevance |
|---|---|---|
| 2-year | Near-term Fed path / policy expectations | Signals whether “higher for longer” is being priced; influences short floating products and sentiment |
| 10-year | Growth, inflation, term premium, duration supply | Closer benchmark for 30-year mortgage and MBS pricing |
| 30-year mortgage | MBS + lender margin + points | What buyers pay — recently still ~7.00%–7.08% survey range |
That is why mortgages can hold steady above seven after a priced-in hike even when the 2-year chops around a few basis points. The front end can reprice Fed odds while the long end — and therefore mortgages — stays anchored near the high yields already baked in this week.
How to read the next few sessions in the 2-year
- If the 2-year grinds higher: Markets are adding weight to October/December firming or a higher terminal rate.
- If the 2-year falls hard on soft data: Path odds are being dialed back — mortgage relief still needs the 10-year and MBS to follow.
- If the 2s/10s curve flattens: Classic “Fed tighter for longer” shape; often accompanies hawkish SEP digestion.
Homebuyers should treat the 2-year as a warning light, not a payment calculator. Payment math still runs through long rates. Investors comparing floating HELOC or bridge debt to fixed acquisition loans should watch both ends of the curve.
What this means for real estate decisions this week
A hawkish front-end adjustment after an expected hike usually means:
- Do not underwrite a rapid 2026 easing cycle into your purchase or refi plan.
- Keep stress-testing mortgage payments at mid-7% levels while surveys sit just above 7%.
- Expect the affordability squeeze and low-turnover “frozen” housing metaphor to remain relevant while path pricing stays restrictive.
Data caveats (read this before screenshotting a tick)
Intraday Treasury quotes differ across terminals, composite prints, and timestamps. Morning soft patches can reverse by the cash close; afternoon press-conference moves can dominate the narrative even when the daily change looks small. For this article we rely on:
- Pre-meeting context that the 2-year had already climbed into the mid-4.60% area on high hike odds
- A documented Wednesday morning ease of a few basis points (about −3.6 bp near 4.625% in one live market wrap)
- Post-decision reporting that yields were largely steady into the announcement after anticipatory moves, with hawkish SEP details (another 2026 hike in the median path) and Warsh’s inflation focus as the adjustment catalysts
That is enough to explain why traders “adjusted to hawkish Fed forecasts” without fabricating an unverifiable last-print. If your brokerage chart shows a sharper V-shape around 2:00–3:00 p.m. ET, it can still fit the same story: early calm or softness giving way to path repricing once the dots and presser removed doubt that September was merely cosmetic.
Bottom line
The 2-year Treasury remains the market’s Fed-path instrument. Wednesday’s package — hike to 3.75%–4.00%, dots still open to another 2026 move, Warsh focused on inflation — gave traders a hawkish forecast to digest. Early-session softness in the 2-year yield fit a pre-announcement fade; the lasting message is not a dovish all-clear. Until inflation cools enough to rewrite the dots, treat front-end yields as a higher-for-longer gauge and remember that mortgage quotes still live or die with the long end.
The Fed’s rate decisions can create market volatility, but turnkey rentals continue to deliver reliable cash flow and appreciation. Investors in 2026 are focusing on real estate as a hedge against uncertainty.
Norada Real Estate helps you secure turnkey properties designed for immediate income and long‑term growth—so your portfolio stays strong regardless of Fed policy shifts.
Want to Know More?
Explore these related articles for even more insights:
- How Fed Rate Hikes Affect Your Wallet, Credit Cards, and Loans
- Goldman Sachs and J.P. Morgan Warn of an Imminent Fed Rate Hike This Week
- Fed Interest Rate Decision July 29, 2026: Rates Steady at 3.50-3.75%
- Interest Rate Predictions for the Next 5 Years: 2026-2030
- J.P. Morgan Predicts No Fed Rate Cuts Before 2027 as Inflation Persists
- Fed Interest Rate Predictions for the Next 3 Years: 2026-2028
- The Fed After Jerome Powell: Who Could Drive Rate Cuts in 2026?
- Why Your Loan Payment Isn’t Budging Despite Recent Fed Rate Cut
- How Does the Recent Fed Rate Cut Impact Your Personal Finances
- Fed Interest Rate Forecast for the Next 12 Months

