Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Today’s Mortgage Rates, June 19: Rates Tick Higher Amid Inflation Concerns

June 19, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

Today, June 19, 2026, average mortgage rates are ticking up a bit, with the popular 30-year fixed-rate purchase mortgage now sitting at 6.36% according to Zillow. It’s like a gentle nudge upwards, not a giant leap. If you're thinking about buying a home or refinancing, knowing these numbers is super important. It's my job to help you understand what all these numbers mean for your wallet.

Today's Mortgage Rates, June 19: Rates Tick Higher Amid Inflation Concerns

Let's break down the numbers you'll see today, June 19, 2026, straight from Zillow. These are for buying a home, so they're what most people think about when they hear “mortgage rates.”

Here's a simple table to see it all clearly:

Loan Type Interest Rate
30-year fixed 6.36%
20-year fixed 6.28%
15-year fixed 5.87%
5/1 ARM 6.46%
7/1 ARM 6.38%
30-year VA 5.85%
15-year VA 5.49%
5/1 VA 5.70%

You'll notice a few things. The 30-year fixed and 15-year fixed rates are a bit higher than they were recently. Also, the 5/1 ARM has nudged up. It’s a bit of a mixed bag, but the general trend is a slight increase today.

What's Making These Rates Move?

It's not just random numbers floating around. Lots of things influence mortgage rates, and they can change pretty quickly. Think of it like the weather – sometimes it's sunny, sometimes it rains, and sometimes it’s a bit breezy.

1. What's Happening in the World:
Remember that big conflict involving Iran that started back in February? That really shook things up. When there’s talk of war and oil prices jump way up (like over $115 a barrel!), it makes everyone a little worried about inflation. When inflation fears rise, borrowing money, including for mortgages, tends to get more expensive.

But here's some good news: there's been talk of a peace deal, and the Strait of Hormuz, a super important route for oil ships, is looking like it might reopen. This has helped calm things down a bit. When the world feels a little more stable, oil prices can cool off, and that makes people less anxious about money. That's why we've seen rates ease up a little from their high points in May.

2. Those Government Bonds:
You might not think about it, but mortgage rates aren't directly controlled by the Federal Reserve's short-term rates. Instead, they tend to follow something called the 10-year U.S. Treasury note yield. When people feel safer about the world, they often put their money into bonds. This demand pushes bond prices up and their yields down. As those Treasury yields have come down from over 4.53% to 4.44%, it’s helped pull mortgage rates down a bit too.

3. Prices Going Up (Inflation):
Even though world events have been calming down, our own country's inflation numbers are still a bit stubborn. The Consumer Price Index (CPI), which is a big way we measure how much prices are changing, jumped to 4.2% in May. That's the fastest it's gone up in three years! When prices are going up quickly, the people in charge of our money, like the Federal Reserve, get nervous.

The Federal Reserve's Move:
The Federal Reserve recently met and decided to keep their main interest rate steady between 3.5% and 3.75%. That sounds like good news, right? But there's a twist. The new boss at the Fed, Kevin Warsh, and his team are now saying that to fight this stubborn inflation, they might actually need to raise interest rates later this year. This is a big deal because it signals they're more serious about stopping prices from rising so fast, even if it means borrowing gets a little more expensive. This “hawkish” stance, as they call it, can put upward pressure on mortgage rates.

What This Means for You

So, what's the big picture for folks looking to buy a house?

On the bright side, the world isn't as scary as it was a few months ago. The worst-case scenarios that could have pushed mortgage rates past 7% haven't happened. That’s a relief!

However, the fact that prices at home are still going up and the Federal Reserve is talking about raising rates means that mortgage rates probably aren't going to drop super low anytime soon. Experts from places like Fannie Mae and the Mortgage Bankers Association think that for now, rates are likely to stay above 6%. It’s like they’re stuck in that zone for a while.

My Two Cents

From my experience, it’s always a bit of a balancing act. You’ve got global events creating waves, and then you’ve got our own economic situation. Right now, the world events have given us a bit of a breather, but domestic inflation and the Fed’s response are the real story.

If you're in the market to buy or thinking about refinancing, my best advice is to stay informed. These rates can shift, and understanding why they’re moving helps you make the best decisions. Don't just look at the number; think about what's behind it.

Are you trying to figure out if now is the right time to buy your dream home, or perhaps thinking about changing your current mortgage? Let me know your situation, and I can try to give you some more specific thoughts based on what I've seen over the years.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 19, 2026: 30‑Year Refinance Rate Drops by 3 Basis Points

June 19, 2026 by Marco Santarelli

Mortgage Rates Today, September 16, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Good news for homeowners looking to refinance! Today, June 19, 2026, marks a small but welcome dip in refinance rates. The national average for a 30-year fixed refinance rate has fallen by 3 basis points, moving from 6.73% down to 6.70%. This is a positive sign for those hoping to trim their monthly payments or tap into their home's equity. This little drop, while not a massive earthquake, is definitely something to pay attention to, especially if you’ve been on the fence about refinancing.

Mortgage Rates Today, June 19, 2026: 30-Year Refinance Rate Drops by 3 Basis Points

What Does This Little Drop Mean for You?

A 3 basis point drop might sound tiny, but let's break it down. A basis point is just 1/100th of a percent. So, 3 basis points means a 0.03% decrease. While this won't suddenly make your mortgage payment drastically different, it's a step in the right direction.

For someone with a $300,000 mortgage, a 0.03% drop translates to saving about $7.50 per month. Over a year, that's $90, and over the life of a 30-year loan, it adds up to a few thousand dollars saved. It’s not life-changing cash, but every bit helps, right?

This current rate of 6.70% for a 30-year fixed refinance is also a 2 basis point drop from the average rate we saw last week, which was 6.72%. So, the trend is definitely heading downwards, albeit slowly.

Other Refinance Rates to Watch

It's not just the 30-year fixed rate that's making news. Here's what else is happening with refinance rates, according to Zillow:

  • 15-year fixed refinance rate: This one has actually nudged up a bit, increasing by 5 basis points from 5.87% to 5.92%.
  • 5-year Adjustable-Rate Mortgage (ARM) refinance rate: This rate is holding steady at 6.12%.

Here’s a quick look at where things stand today:

Loan Type Today's Rate (June 19, 2026) Previous Rate (Approx.) Change
30-Year Fixed Refinance 6.70% 6.73% Down 3 bps
15-Year Fixed Refinance 5.92% 5.87% Up 5 bps
5-Year ARM Refinance 6.12% 6.12% Steady

(Rates are national averages reported by Zillow.)

What’s Making Rates Move?

It’s always a bit of a puzzle trying to figure out exactly why mortgage rates do what they do. A lot of things play a role, from what the big banks are thinking to global events. Here’s what I’m seeing as the main drivers behind these current rates:

  • The Federal Reserve's Stance: The Fed recently decided to keep their main interest rate the same. But, they also put out some signals that suggest they might not be cutting rates as much as people hoped this year. Some folks on the Fed are even talking about potentially raising rates if prices keep going up too much. This uncertainty keeps lenders a bit cautious, which can influence mortgage rates.
  • Global News: Remember when there was a lot of worry about conflicts happening around the world? That made gas prices jump and caused some panic. Now, there are some signs that things might be calming down, which is helping bond markets feel a bit more stable. When bonds are more stable, it can help keep mortgage rates from going way up.
  • Treasury Yields: Mortgage rates don't follow the Fed's rate directly. Instead, they tend to track the 10-year Treasury yield. Right now, that yield is hanging around 4.44%. This is like a steady platform for loan prices, meaning rates aren’t likely to drop dramatically unless this yield really moves.
  • A Strong Economy: The good news is, our economy seems to be doing pretty well. People are buying more things, and not as many people are out of jobs. This is great for the country, but it also means the economy isn't slowing down enough for lenders to feel like they need to slash mortgage rates to get people to borrow money.

My Thoughts on Refinancing Right Now

From my experience, I always tell people to think carefully before jumping into a refinance. It’s not always the magic bullet everyone hopes for.

The 0.50% Rule: A good rule of thumb I often share is the “0.50% rule.” If your current mortgage rate is below 7.25% and you can't shave off at least half a percentage point (0.50%) by refinancing, it's probably not worth the hassle and cost right now. For example, if you have a mortgage at 7.00%, refinancing to 6.70% is a great idea. But if you have a rate at 6.90% and can only get 6.70%, you might want to wait.

Don't Forget Closing Costs: Refinancing isn't free! You'll have to pay fees, which can be anywhere from 2% to 6% of your loan amount. That's a chunk of money. You need to make sure you plan to stay in your home long enough to make those costs back through your lower monthly payments. If you refinance a $200,000 loan and the closing costs are $10,000, you need to save at least that $10,000 in monthly payments to break even.

Consider Other Options for Cash: If you need to get some cash out of your home but your current mortgage rate is really low, a refinance might not be the best option. Sometimes, a Home Equity Line of Credit (HELOC) or a home equity loan can be a better choice. These let you borrow against your home's value without changing your primary mortgage rate.

Your Credit Score Matters Big Time: I've seen it time and time again – a good credit score opens doors to better rates. Lenders are being a bit pickier these days. If you have a FICO score of 760 or higher, you're likely to get rates that are up to 0.75% lower than someone with a score below 680. So, if you're thinking about refinancing, take a look at your credit report and see if there's anything you can do to boost your score.

What Does This Mean for the Housing Market?

A slight drop in refinance rates is usually a good sign for the housing market. It can encourage more people to buy homes because they can secure slightly better loan terms. It also helps existing homeowners who might want to refinance to get a lower payment or tap into their equity.

However, with the economy still strong and the Federal Reserve signaling that rate cuts might not be coming as quickly as hoped, I don’t expect a huge rush of people refinancing. It’s more of a steady, gradual improvement.

For those of you who have been waiting for the perfect moment to refinance, today’s small dip is definitely a reason to look closer. Make sure you do your homework, compare offers from different lenders, and see if it makes sense for your financial situation.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 18: Fixed Loans Drop, Adjustable Rates Stay Mixed

June 18, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or refinancing, you're probably wondering about today's mortgage rates for June 18. The good news is that for fixed-rate loans, rates are nudging a little lower this week! Specifically, the average rate for a 30-year fixed loan dropped to 6.24%, the 20-year fixed is now at 6.01%, and the 15-year fixed is sitting at 5.72%. This is a welcome little dip, though it's important to remember these are averages, and your personal rate might be a bit different.

Today's Mortgage Rates, June 18: Fixed Loans Drop, Adjustable Rates Stay Mixed

It feels like just yesterday we were talking about super low mortgage rates, right? I've been following the housing market for years, and I remember when getting a rate under 3% felt like finding a unicorn. Now, things are a bit different, and understanding where rates are today and what might happen next is key to making smart decisions about your home.

What Are Today's Mortgage Rates Like?

Let's break down what the numbers look like right now, according to Zillow data for June 18, 2026:

Loan Type Average Rate
30-year fixed 6.24%
20-year fixed 6.01%
15-year fixed 5.72%
5/1 ARM 6.31%
7/1 ARM 6.03%
30-year VA 5.74%
15-year VA 5.28%
5/1 VA 5.50%

(Note: These rates are for purchase loans and are averages. Your actual rate can depend on your credit score, down payment, and other factors.)

Fixed vs. Adjustable-Rate Mortgages: A Quick Look

You'll see different types of loans listed. Fixed-rate mortgages mean your interest rate stays the same for the whole life of the loan. Adjustable-rate mortgages (ARMs) have a rate that can change over time.

Right now, I'd be a little cautious about the 5/1 ARMs. They're actually costing a bit more than the 30-year fixed loans, which feels a bit backward! However, the 7/1 ARM is something to look at closely. It's currently lower than the 30-year fixed. The big idea with an ARM is that you get a lower rate for the first few years (that's the ‘5' or ‘7' in 5/1 or 7/1). If you plan to move or refinance before that initial period ends, it could save you money. But if you plan to stay put for a long time, locking in a fixed rate is usually the safer bet to avoid surprises when the rate adjusts.

How Do These Rates Affect Your Wallet?

Let's imagine you're looking at a $400,000 loan. Here's how the monthly payments (principal and interest only) stack up:

  • 30-Year Fixed (6.24%): You'd be looking at about $2,460 per month.
  • 15-Year Fixed (5.72%): This would be around $3,314 per month.

That's a difference of $854 per month if you choose the 30-year loan. However, over the life of the loan, the 15-year fixed saves you a whopping $388,719 in interest! It's a trade-off between a lower monthly payment now and significant savings in the long run.

What's Driving Today's Mortgage Rates?

Mortgage rates aren't just pulled out of thin air. They're influenced by a lot of things happening in the economy. Think of it like a big puzzle with many pieces.

The Big Picture for the Coming Year:

Experts who study the housing market, like those at Fannie Mae and the Mortgage Bankers Association, think rates will likely stay in the 6.1% to 6.5% range for the rest of the year. And looking further out, it seems like rates will probably stick between 6.0% and 6.5% for a few years. This tells me that the days of super-duper low rates are probably behind us for a while.

What Makes Rates Go Up (or Down):

The most important thing to remember is that mortgage rates don't just follow what the Federal Reserve does with their short-term rates. Instead, they're more closely tied to something called the 10-year Treasury yield. This yield is like a thermometer for how investors are feeling about the economy.

Stuff Pushing Rates Higher (These are the bigger forces right now):

  • Inflation Won't Quit: Prices are going up faster than the Federal Reserve wants. When money loses its buying power, lenders try to charge more interest to make up for it over the long loan term.
  • World Events: Sometimes, problems in other parts of the world, like conflicts that affect oil prices, can make everything more expensive and push inflation higher, which then pushes mortgage rates up too.
  • The Fed's Tightrope Walk: Even though the Federal Reserve didn't raise its main interest rate recently, some people in the market think they might have to raise it later in the year because of inflation. This expectation can push mortgage rates up.
  • Government Borrowing: The government borrows a lot of money, and when they issue a lot of bonds to do that, it can push up the yields on those bonds, which in turn pulls up mortgage rates.

What's Keeping Rates From Going Completely Crazy High?

  • People Buying Less: With higher home prices and higher borrowing costs, fewer people are buying houses. This naturally puts a bit of a brake on how high lenders can push rates before the market just stops altogether.

What Should You Do With This Information?

Based on what experts are saying, like the National Association of Realtors, it's a good idea to stop waiting for rates to magically drop and start making plans based on what's happening now.

For People Wanting to Buy a Home:

  • “Marry the House, Date the Rate”: This is a popular saying, and it's wise. If you find a house you love and can afford, it might be better to buy it now. Waiting for a lower rate is a gamble.
  • Expect More Buyers Later: If rates do dip a bit in the future, a lot of people who have been waiting will rush back into the market. This could mean more competition and higher home prices, possibly canceling out any savings from a slightly lower rate.
  • Think About Hybrid ARMs: Like the 7/1 ARM, these can offer a lower starting rate. If you think you might sell or refinance in a few years, it could be a smart way to get into a home now and potentially save money initially.
  • Ask About “Buying Down” the Rate: You can sometimes negotiate with the seller to help you pay for a lower interest rate at closing. It's like an upfront payment to save on interest later.

For People Who Already Own a Home:

  • Protect Your Low Rate: If you got lucky and have a super low rate from a few years ago, hold onto it! If you need cash for renovations, consider a home equity line of credit (HELOC) or a second mortgage instead of refinancing your main mortgage, which would mean giving up that great low rate.
  • Get Ready to Refinance Later: Keep your credit score in great shape (aim for 740 or higher) and pay down other debts as much as you can. This will put you in the best position to refinance if rates take a dip below 6% in the future.

The housing market is always changing, and today's mortgage rates for June 18 are just one piece of the puzzle. But by understanding what's going on, you can make the best choices for your own homeownership journey.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 18, 2026: 30‑Year Refinance Rate Rises by 7 Basis Points

June 18, 2026 by Marco Santarelli

Mortgage Rates Today, September 16, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Looks like the numbers are nudging up a bit for those thinking about refinancing. Today, June 18, 2026, the average 30-year fixed refinance rate has climbed to 6.74%, a slight increase of 7 basis points. This means the dream of a super-low rate might be a little further out of reach for some homeowners right now.

Mortgage Rates Today, June 18, 2026: 30-Year Refinance Rate Rises by 7 Basis Points

It's easy to get caught up in the daily ups and downs of mortgage rates, but I've been watching this market for a long time, and I know it's crucial to understand what's really going on. After a period where rates dipped closer to 6.0% back in April, they've been steadily climbing again, settling in the mid-to-high 6% range. This isn't the best news for everyone, especially those who locked in rates below 5% during the pandemic. For them, refinancing right now likely doesn't make financial sense unless they have a very specific reason.

What's Causing These Rate Jumps?

You might be wondering why these rates are moving around so much. It's like a seesaw, influenced by a few big players.

  • Inflation is Sticky: We're seeing inflation hit its highest point since 2023, climbing 4.2% over the last year. A big part of this is due to rising energy costs, which are being pushed higher by what's happening in Iran. When prices for everyday things go up, it makes it harder for the economy to stay stable.
  • The Fed is Getting Serious: The Federal Reserve, now led by Chair Kevin Warsh, recently decided to keep their main interest rate the same. But, with the job market still strong – adding 172,000 jobs last month – and inflation being so high, they're starting to talk a bit tougher. The idea of lowering interest rates anytime soon has been put on hold, and people are even starting to think the Fed might raise rates later this year. This “hawkish” talk makes borrowing money more expensive.
  • Treasury Yields are High: Mortgage rates often follow the lead of the 10-year Treasury yield. Right now, this yield is a bit jumpy because of government spending and general worries about the economy. When the bond market is uncertain, it adds a little extra cost, which we see reflected in mortgage rates.

What Should You Watch For If You're Thinking About Refinancing?

If you're considering refinancing, especially in this environment, you need to be smart about it. Here are a few things I always tell people to think about:

1. Your Break-Even Point: Refinancing isn't free. You'll have closing costs, which can be anywhere from 2% to 6% of the loan amount. You need to figure out how long it will take for your monthly savings to cover those costs. If you think you'll sell your home before you reach that “break-even” month, then refinancing might actually cost you money in the long run.

2. The 1% Rule: While historically a 2% drop in your rate was the magic number, things have changed. Now, especially if you bought your home when rates were higher (like in late 2023 or 2024), getting a rate that's 1% lower than what you have now can often justify the closing costs. It's worth doing the math!

3. Smart Cash-Out Refinancing: If you've built up a lot of home equity and also have high-interest debt like credit cards, a cash-out refinance might still be a good idea. Even if your current mortgage rate is lower, consolidating that expensive debt into a mid-6% mortgage could save you a lot of money on interest over time. It's a strategic move.

4. Locking Your Rate: With rates moving so much day-to-day, trying to catch the absolute lowest point is really risky. If a lender offers you a rate that fits your budget and your financial goals, it's often best to lock that rate in right away. Waiting for a slightly better deal could mean ending up with a higher rate than you expected.

Today's Refinance Rates at a Glance

Here's a quick look at the average rates for different types of refinances today, June 18, 2026, according to Zillow:

Loan Type Current Average Rate Change from Previous Day Change from Previous Week
30-Year Fixed 6.74% +7 basis points +2 basis points
15-Year Fixed 5.89% +18 basis points (Data not provided)
5-Year ARM 6.12% (Data not provided) (Data not provided)

Note: Rates are by Zillow. Basis points are a way to measure small changes in interest rates, where 1 basis point equals 0.01%. So, 7 basis points means a 0.07% increase.

What About the Future?

Forecasters like the Mortgage Bankers Association are predicting that rates will likely stay in the 6.3% to 6.5% range for the rest of 2026. This suggests that while we might see some fluctuations, a big drop back down to pandemic-era lows is probably not on the horizon anytime soon.

For homeowners, this means it's more important than ever to stay informed and to carefully consider your individual situation before making any decisions about refinancing.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 17: Rates Edge Down But Market Still Tight

June 17, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

If you're thinking about buying a home or refinancing your mortgage, you've probably been watching mortgage rates closely. As of June 17, the rates have seen a small dip, with the popular 30-year fixed mortgage rate now at 6.26%. While this is a tiny bit lower than yesterday, it's still a bit higher than what we saw earlier this year.

Today's Mortgage Rates, June 17: Rates Edge Down But Market Still Tight

It feels like just yesterday we were seeing rates closer to 6.0%, and now we're hovering a bit above that. Why is this happening? Well, a few big things are going on in the world that are making these rates stick around. Think of it like a big puzzle where different pieces affect how much you pay for your home loan.

What's Happening with Today's Mortgage Rates?

Let's break down what the numbers are telling us today. According to Zillow, here's a snapshot of what mortgage rates look like on June 17:

Loan Type Interest Rate
30-year fixed 6.26%
20-year fixed 6.06%
15-year fixed 5.73%
5/1 ARM 6.30%
7/1 ARM 6.03%
30-year VA 5.80%
15-year VA 5.38%
5/1 VA 5.58%

As you can see, most of the rates have nudged down just a tiny bit. The 30-year fixed rate, which is what most people choose for their homes, dropped by 5 “basis points” (that's just a fancy word for a small change in percentage) to land at 6.26%. The 15-year fixed and the 5/1 ARM also saw a small dip of 1 basis point.

Why Aren't Rates Much Lower? The Big Picture

Even though we saw a small drop, rates are still higher than they were at the start of the year. This is mainly because of a few big factors that are like strong winds pushing against lower rates. I’ve been watching this market for a while, and it's clear that these issues aren't going away overnight.

Here are the main things making rates stick around the current levels:

  • Trouble Far Away, Trouble Here: There's a military conflict happening in Iran. This is really important because Iran is a big supplier of oil. When there's worry about oil, prices go up. Since oil is used for almost everything – like shipping goods and making things – higher oil prices make everything else cost more. This is called inflation. Even though there have been some small agreements to help ships get through safely, the worries about prices going up for a long time are still there.
  • Prices Keep Going Up: You know how sometimes the price of your favorite snack goes up? Well, that's happening with lots of things for everyone. The government wants prices to only go up about 2% each year. But right now, prices are going up much faster, around 4.2%! When prices go up quickly, the money people have saved doesn't buy as much. To make sure they don't lose money because of this, banks and lenders have to charge more for loans, which means higher mortgage rates.
  • Government Borrowing and Bonds: You might have heard about the government borrowing money. When the government needs a lot of money, it sells something called “bonds.” Think of bonds like an IOU from the government. When lots of bonds are being sold, the government has to offer a higher “interest rate” on these bonds to get people to buy them. Mortgage rates tend to follow what happens with these long-term government bonds, specifically the 10-year Treasury yield, which has been around 4.5%. So, the more the government borrows, the higher interest rates tend to go.
  • The Federal Reserve's Tough Choices: The Federal Reserve (often called the “Fed”) is like the main banker for the country. They can help control how much money is out there and how much it costs to borrow. They actually lowered interest rates a lot late last year to help people. But now, with prices going up so much and people still having jobs, the Fed is rethinking things. They're not planning to lower rates anytime soon. In fact, some people are even starting to think they might have to raise interest rates to fight inflation, which would push mortgage rates even higher.

What Does This Mean for You?

When mortgage rates are a bit higher, it means buying a home can be more expensive each month. For example, if you borrow $300,000, even a small increase in the interest rate can add up to hundreds of dollars more on your monthly payment over the years.

  • For Buyers: If you're looking to buy, it’s a good time to shop around for the best rate from different lenders. Also, try to save up a larger down payment if you can. A bigger down payment means you borrow less money, which can lower your monthly payments.
  • For Refinancers: If you already have a mortgage, it might not be the best time to refinance if your current rate is lower than today's rates. However, if you need to lower your monthly payments for other reasons, it's still worth looking into options.

My Thoughts on Today's Rates

From where I stand, these rates are a bit of a balancing act. The world is dealing with some big challenges, from faraway conflicts affecting oil prices to how we manage our own country's money. The Federal Reserve is in a tough spot, trying to keep prices from going up too fast without hurting the economy too much.

For the average person, it means we need to be smart about our homebuying decisions. It's not just about the sticker price of a house; it's about the total cost over time, and that's heavily influenced by the mortgage rate you get.

I’ve seen rates go up and down over the years, and what’s happening now is a reminder that things don't always move in a straight line. The good news is that even with these rates, owning a home is still possible for many. It just requires a bit more careful planning and understanding of what's driving the numbers.

So, while today's mortgage rates might not be the lowest we've seen, they are what they are for now. Keep an eye on the news, talk to lenders, and make the best decision for your situation!

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

30-Year Fixed Mortgage Rate Drops by 32 Basis Points From Last Year’s Highs

June 17, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Drops by 32 Basis Points Year-Over-Year

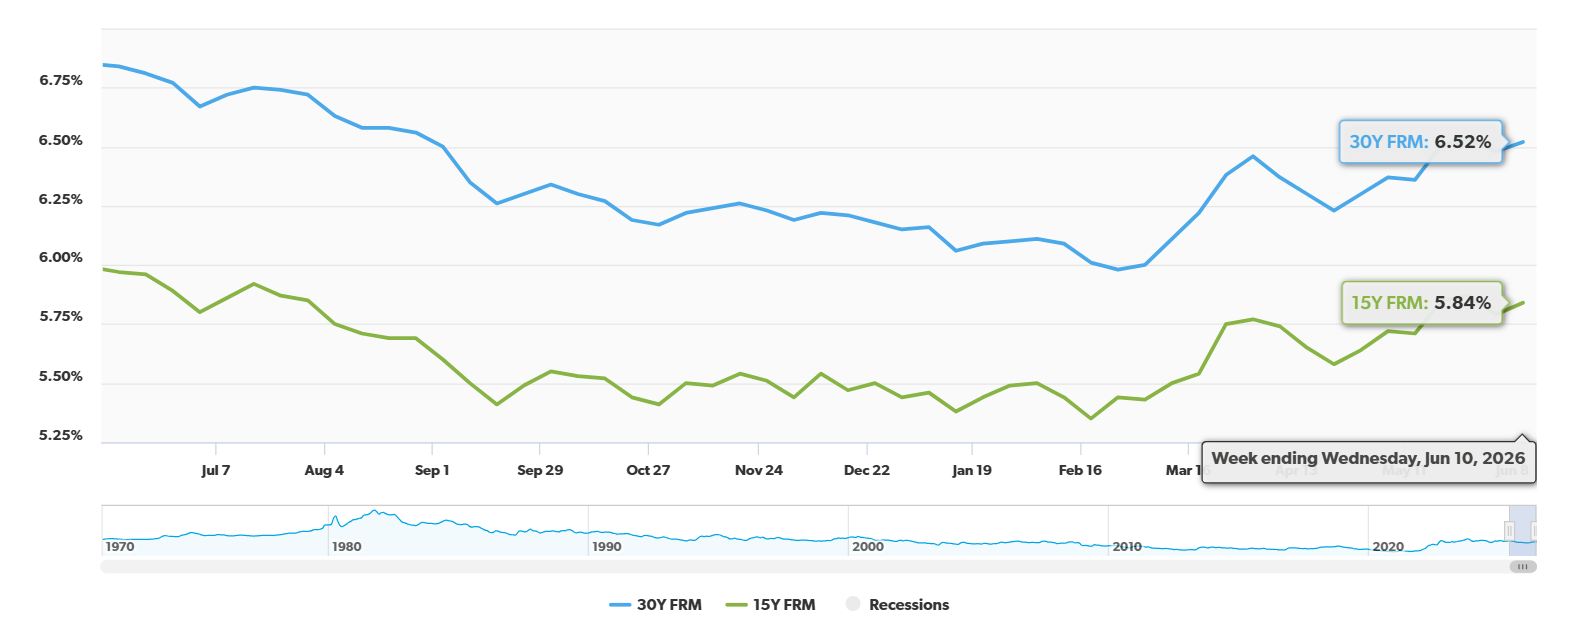
According to the Freddie Mac Primary Mortgage Market Survey for the week ending June 11, 2026, the 30-year fixed-rate mortgage averaged 6.52%, marking a 32-basis-point drop year-over-year from the 6.84% average recorded during the same week in 2025. While borrowing costs have trended lower over the past 12 months, rates ticked up slightly from last week’s average of 6.48% due to resilient labor data and sticky consumer inflation. This annual decrease translates into tangible savings for borrowers, making homeownership more attainable despite current economic pressures.

30-Year Fixed Mortgage Rate Drops by 32 Basis Points From Last Year’s Highs

Understanding the Numbers: A Closer Look at the Decline

Let's break down what this means. Freddie Mac, a key player in the housing finance industry, releases weekly surveys that are a benchmark for mortgage rates across the country. Their data for the week ending June 11, 2026, shows the average 30-year fixed-rate mortgage at 6.52%.

Here's a quick look at how this compares:

Loan Type Weekly Average (06/11/2026) 1-Week Change 1-Year Change
30-Yr Fixed FRM 6.52% +0.04% -0.32%
15-Yr Fixed FRM 5.84% +0.05% -0.13%

FRM stands for Fixed-Rate Mortgage.

You can see the 30-year fixed rate is a full 0.32% lower than it was a year ago. This is a substantial move. While the weekly jump of 0.04% might seem small, it's the year-over-year trend that truly signals a more affordable borrowing environment for many. The 15-year fixed-rate mortgage also saw a year-over-year decrease, though it wasn't as pronounced.

30-Year Fixed Mortgage Rate Drops by 32 Basis Points Year-Over-Year
Freddie Mac

Why the Slight Weekly Jump? Factors at Play

It's important to understand that mortgage rates don't move in a straight line. Even with the positive year-over-year trend, rates can fluctuate weekly. The data from Freddie Mac points to a couple of key reasons for the slight increase from last week:

  • Resilient Labor Data: The latest jobs report showed more new jobs were created than economists predicted. This is generally a good sign for the economy, but it can also signal that the Federal Reserve might be less inclined to lower its benchmark interest rates quickly. Lower benchmark rates often lead to lower mortgage rates.
  • Sticky Consumer Inflation: While inflation has cooled from its peak, it's still proving to be a bit stubborn. When inflation is higher, it can put upward pressure on interest rates as lenders try to keep pace with rising costs.

These are the forces that are essentially creating a floor under mortgage rates, preventing them from plummeting back into the 5% range we saw in some more favorable periods.

The Real Impact: What a 32-Basis-Point Drop Means for Your Wallet

This is where it gets exciting for potential homeowners. A 32-basis-point reduction in your interest rate can make a significant difference in your monthly mortgage payment and the total interest you pay over the life of your loan.

Let's imagine you're looking at a standard $400,000, 30-year fixed loan.

  • At 6.52%, your estimated monthly principal and interest payment would be around $2,533.54.
  • If the rate were 6.20% (representing a 32-basis-point drop from the current 6.52%), that same loan's monthly payment would be approximately $2,449.88.

That's a monthly savings of $83.66!

Over the 30-year life of the loan, this translates to a total interest saving of $30,117.60. That's money you can use for home improvements, savings, or simply enjoy.

Here's a table showing how this drop impacts various loan amounts:

Loan Amount Monthly Payment at 6.52% Monthly Payment at 6.20% Monthly Savings 30-Year Lifetime Savings
$300,000 $1,900.16 $1,837.41 $62.75 $22,590.00
$400,000 $2,533.54 $2,449.88 $83.66 $30,117.60
$500,000 $3,166.93 $3,062.35 $104.58 $37,648.80
$600,000 $3,800.31 $3,674.82 $125.49 $45,176.40

Note: These are estimates for principal and interest only and do not include taxes, insurance, or fees.

What This Means for the Housing Market and Buyers

This annual rate reduction, even with slight weekly ups and downs, is a positive signal for the housing market. It boosts buyer purchasing power. For instance, Redfin data suggests that new home listings have surged, creating a more favorable inventory situation for buyers. With nearly 47% more sellers than active buyers in some areas, homebuyers might find they have more room to negotiate on price, even with mortgage rates in the mid-6% range.

From my perspective, this environment presents a unique opportunity. Buyers who have been patiently waiting for rates to dip may find that now is a good time to re-enter the market. The combination of a more favorable interest rate year-over-year and potentially increased inventory can lead to a better overall home-buying experience. It's crucial, however, to stay informed about weekly rate changes and consult with a mortgage professional to understand how these fluctuations might affect your specific situation.

The average 30-year fixed mortgage rate falling by 32 basis points year-over-year to 6.52% is a clear indication of improving affordability for potential homebuyers, despite some ongoing economic factors keeping rates from falling further.

🏡 Out‑of‑State Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

Mortgage Rates Today, June 17, 2026: 30‑Year Refinance Rate Drops by 4 Basis Points

June 17, 2026 by Marco Santarelli

Mortgage Rates Today, September 16, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Well, it looks like a little bit of good news for homeowners thinking about refinancing their mortgages. On June 17, 2026, the average rate for a 30-year fixed refinance actually dipped by 4 basis points. This means that if you've been on the fence about whether to refinance, today might be a day to take a closer look.

Mortgage Rates Today, June 17, 2026: 30-Year Refinance Rate Drops by 4 Basis Points

What’s Happening with Refinance Rates Right Now?

So, what does this little drop really mean for you? According to Zillow, the national average for a 30-year fixed refinance rate is now sitting at 6.68%. This is a small step down from yesterday's rate of 6.64%. While it might seem like a tiny change, every little bit counts when you're talking about a big loan like a mortgage.

It's not just the 30-year loans seeing movement. The 15-year fixed refinance rate also got a nice little haircut, dropping a more significant 12 basis points to 5.62%. And if you're looking at an adjustable-rate mortgage (ARM), the 5-year ARM refinance rate has seen the biggest dip, down a whole 50 basis points to 5.75%.

Right now, the national average for a 30-year fixed refinance is hovering between 6.60% and 6.70%. This means that many homeowners are watching these rates very closely. Even though rates are higher than they were last year (about 17% higher than the really low historic rates), people are still applying to refinance. However, applications actually dropped by 5% this past week. This tells me that even with a small rate drop, things are still pretty sensitive to what's happening in the bigger economy.

Why Are Rates Doing This? It’s Not Just One Thing!

It can be confusing to figure out why mortgage rates change. It's not like the Federal Reserve just wakes up and decides to change them. A lot of different things are going on behind the scenes that make lenders adjust their prices.

One of the big things is something called inflation. Think of inflation like prices going up for everything. When inflation is high, like it has been recently (showing a 4.2% increase in the Consumer Price Index), it makes borrowing money more expensive for everyone, including mortgage lenders. This forces bond yields higher, and that directly impacts what they can offer you for a mortgage.

Then there's what the Federal Reserve is doing. Even though inflation is still a bit high, the job market is still pretty strong. There were a lot of jobs added recently (172,000 in May), which means the Fed might not be in a hurry to lower interest rates anytime soon. Wall Street is kind of expecting rates to stay “higher for longer.”

And we can't forget what's happening around the world. Things like conflicts in the Middle East can make energy prices go up. When energy prices go up, it can also affect something called the 10-Year U.S. Treasury yield. This yield is a really important number that lenders look at when they decide what to charge for a 30-year mortgage. So, global events can have a direct impact on your mortgage rate!

Who Is Actually Refinancing These Days?

I've noticed that the people who are refinancing right now are usually those who bought their homes when rates were much higher, maybe even above 7%. They're looking to grab a better deal if they can.

Also, a lot of people are looking to get cash out of their homes, either for renovations or to pay off other debts. But it’s interesting, many are choosing a Home Equity Line of Credit (HELOC) instead of a full refinance. This is smart because they can keep their existing, low primary mortgage rate and just borrow extra money at a potentially higher rate for their specific need. It saves them from giving up their great original loan.

What Should You Look For When Thinking About Refinancing?

If you're thinking about refinancing, here are some things I'd really pay attention to:

  • How Long Until You Save Money (Break-Even Point): Refinancing usually costs money upfront, often between 2% and 5% of your loan amount for closing costs. You need to figure out how many months it will take for the money you save each month to add up to more than those upfront costs. If you plan to move before you reach that “break-even” point, you might actually lose money by refinancing.
  • Extending Your Loan Term: It’s tempting to lower your monthly payment by switching to a brand-new 30-year loan. But remember, this means you’ll be paying for your house for a lot longer. Over the entire life of the loan, you’ll end up paying a lot more in interest.
  • Considering Other Ways to Get Cash: If you need money for a project or to pay off other debts, compare a cash-out refinance with a HELOC. Sometimes, it’s way cheaper to keep your low primary mortgage and get a separate HELOC for the extra cash you need. For example, mixing a 3% primary mortgage with a small 8% HELOC can be thousands of dollars cheaper than replacing your whole loan with a new 6.6% rate.
  • Your Credit Score Matters a Lot: In today’s market, lenders want to see that you’re a super safe bet. If you have a great credit score (usually 740 or higher), you'll likely get the best rates. Before you apply, check your credit report and make sure everything is in order. You don't want to have your application turned down because of something on your credit that you could have fixed.

Here's a Quick Look at Today's Refinance Rates:

Loan Type Current Average Rate (June 17, 2026) Change from Previous Week
30-Year Fixed Refinance 6.68% Down 4 basis points
15-Year Fixed Refinance 5.62% Down 12 basis points
5-Year ARM Refinance 5.75% Down 50 basis points

Rates are by Zillow.

It's a dynamic market out there, and these numbers can change. The best thing you can do is stay informed and talk to a mortgage professional to see what makes the most sense for your situation.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 16: Fixed Loan Rates Ease But ARMs Edge Higher

June 16, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of today, June 16, 2026, if you're looking to buy a home, the average 30-year fixed mortgage rate is sitting at 6.31%, which is a little bit lower than yesterday. It's a bit of a mixed bag out there with some rates inching up and others dipping down, but overall, things are staying pretty steady in the mid-6% range for the most common types of loans.

Today's Mortgage Rates, June 16: Fixed Loan Rates Ease But ARMs Edge Higher

So, today is one of those days where we see a little bit of movement in mortgage rates. It’s like the stock market, but for houses! While a small change might not seem like a big deal, it can actually make a difference in how much you pay over the years. Let's break down what's happening with today's mortgage rates and what it means for you and your dream of homeownership.

What Are Today's Mortgage Rates, June 16, 2026?

Based on the latest information from Zillow, here’s a snapshot of what you might see today:

  • 30-year fixed rate: 6.31% (down 4 basis points from yesterday)
  • 20-year fixed rate: 6.19% (up 9 basis points from yesterday)
  • 15-year fixed rate: 5.74% (down 4 basis points from yesterday)
  • 5/1 ARM: 6.31% (up 1 basis point from yesterday)

And just so you know, these numbers are just averages. Your actual rate could be higher or lower depending on your credit score, the size of your down payment, and other factors.

A Deeper Dive: What’s Causing These Swings?

It’s easy to just look at the numbers and say “higher” or “lower,” but understanding why they move is the real key. For me, as someone who's watched this market for a while, it's all about how different parts of the economy are doing. Think of it like a big puzzle with lots of pieces.

1. Inflation: The Big Spender

You’ve probably heard about inflation in the news. It’s basically when prices for everything go up. This May, the government said prices went up by 4.2% compared to last year. Even when you take out the prices of things like food and gas that can change a lot, prices are still stubbornly high, up 2.9%.

When inflation is high, money isn't worth as much. So, people who lend money (like banks) want to get paid more to make up for it. This makes mortgage rates go up. It's like if your favorite candy bar suddenly cost more – you’d want more allowance to buy it, right?

2. Jobs, Jobs, Jobs!

The good news is that people are finding jobs! In May, the U.S. added 172,000 jobs, which is more than people expected. And the number of people looking for jobs but not finding them stayed the same at 4.3%.

A strong job market is a sign that our economy is doing well. When people are working and earning money, they feel more confident about buying homes and making big purchases. This can sometimes push rates up a little because there’s more demand.

3. What the Fed is Thinking (and Doing)

The Federal Reserve, or the “Fed” as many call it, is like the conductor of our economy’s orchestra. They have the power to lower or raise interest rates. Right now, they’ve kept their main interest rate pretty high, between 3.5% and 3.75%.

Because inflation is still a worry and the job market is strong, many people don't think the Fed will lower interest rates anytime soon. In fact, they might keep them high for a while longer. This “higher-for-longer” idea makes the cost of borrowing money, including for mortgages, stay up. The 10-year U.S. Treasury yield, which is like a benchmark for mortgage rates, is also staying high because of this.

4. World Events and Oil Prices

Sometimes things happening far away can still affect our wallets. There's been some trouble in the Middle East, and that can make oil prices jump around. When oil prices go up, so do the costs of lots of things, including transportation and making products.

This global uncertainty can make investors a bit nervous. They might demand a higher return for lending their money, which again, pushes up mortgage rates. It’s a ripple effect!

Comparing Today to Last Week and Last Year

It’s always helpful to see how today’s rates stack up.

Loan Type Today's Average (June 16, 2026) Last Week's Average (Approx.) Change from Last Week Last Year's Average (Approx.) Change from Last Year
30-year fixed 6.31% 6.59% Down 6.84% Down
15-year fixed 5.74% 5.84% Down N/A N/A
5/1 ARM 6.31% N/A N/A N/A N/A

Note: Weekly data is based on general trends and surveys.

Looking at the table, you can see that while today's 30-year fixed rate is a bit lower than the average we saw at the start of the week (around 6.59%), it's still a good bit lower than this time last year, when it was around 6.84%. That's a saving of about 40 basis points, which is nice!

The 15-year fixed rate has also seen some ups and downs, but it's currently looking pretty good at 5.74%.

What Does This Mean for You?

If you’re thinking about buying a home, these rates mean you'll want to shop around for the best deal. Even a small difference in the interest rate can save you thousands of dollars over the life of your loan. It’s why I always tell people to get quotes from a few different lenders.

If you already own a home and have a higher interest rate, you might be wondering about refinancing. It’s a good idea to keep an eye on these numbers. If rates dip significantly, refinancing could lower your monthly payments. However, with rates staying in the mid-to-high 6% range, it's still a bit of a wait-and-see game for many homeowners looking for a big drop.

For those considering an Adjustable-Rate Mortgage (ARM), like the 5/1 ARM at 6.31%, remember that the rate is fixed for the first five years and then can change. It can be a good option if you plan to move or refinance before the fixed period is over, but it comes with the risk of higher payments later on.

My advice? Don't get too caught up in the day-to-day ups and downs. Focus on what your personal finances look like, what your long-term goals are, and then work with a trusted lender to find the mortgage that’s the best fit for you.

Future Outlook: What to Watch For

Predicting mortgage rates is like trying to predict the weather – you can make educated guesses, but there are always surprises. I'll be keeping an eye on inflation reports, job numbers, and anything the Fed says. If inflation starts to cool down and the Fed signals they might lower rates, we could see mortgage rates begin to trend downwards more consistently. Until then, expect things to stay a bit bumpy.

Remember, buying a home is a huge decision. Take your time, do your research, and don't be afraid to ask questions!

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 16, 2026: 30‑Year Refinance Rate Drops by 2 Basis Points

June 16, 2026 by Marco Santarelli

Mortgage Rates Today, September 16, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

If you're thinking about refinancing your home, you'll want to hear this. Today, June 16, 2026, brings a little bit of good news for those looking to refinance a 30-year mortgage. The average rate has dipped by 2 basis points, settling at 6.70%. While this might seem like a tiny change, it's a welcome sign in what has been a pretty stubborn market.

Mortgage Rates Today, June 16, 2026: 30‑Year Refinance Rate Drops by 2 Basis Points

What This Tiny Dip Means for You

Let's be real, a 0.02% drop might not sound like a lot at first glance. But remember, mortgage rates are a bit like the weather – they can change by small amounts quite often. What's more important is the trend and what it signals about the economy.

I've been watching mortgage rates for a long time, and even these small movements tell a story. It seems like rates have been hanging out above the 6.0% mark for a while now. This is mainly because the economy is still showing some strength, which makes lenders a little hesitant to lower rates too much.

It's a bit of a puzzle, isn't it? We're seeing more people wanting to refinance compared to last year, but a huge chunk of homeowners (over 80%!) are still sitting pretty with rates that are much lower than today's. This means most of the refinancing happening right now is for people who either bought homes when rates were super high, or they're using the refinance to pull out some cash from their homes, not just to get a better rate.

Why Are Rates Sticking Around?

It's not just one thing making mortgage rates do what they do. Here are the big players:

  • Inflation is Still a Bit Sticky: Remember hearing about inflation? Well, it's still hanging around. The latest numbers from May showed prices jumped by about 4.2%. When inflation is like this, it puts pressure on things like the 10-year Treasury yield, and guess what? Mortgage rates tend to follow that yield pretty closely.
  • Jobs, Jobs, Jobs! The job market is still looking pretty good. More jobs are being created than folks expected, and people are holding onto their jobs. This means the economy isn't slowing down as much as some hoped it would, which makes it less likely that interest rates will drop quickly.
  • World Events Matter: Sometimes, news from far away, like conflicts in the Middle East, can really shake things up. When things calm down in those areas, the stock market (and bonds) can get a bit shaky, which can push Treasury yields and mortgage rates up. It’s a crazy connection, but it's true!
  • The Federal Reserve's Big Meeting: Big news! The Federal Reserve has a meeting coming up on June 17th. Everyone is watching to see if they'll signal that interest rates might go up, stay the same for a long time, or eventually come down. What they say, especially in their “dot plot” forecasts, will have a big impact.

What Should You Watch Out For If You're Refinancing?

So, you're thinking about refinancing? That's great! But before you jump in, here are a few things I always tell people to think about:

  • The Break-Even Point: Refinancing usually costs money upfront. We're talking about closing fees that can add up to 2% to 6% of your loan amount. You need to do the math! Will the money you save each month be enough to cover these costs over time?
  • Your Credit Score is King: Lenders want to see good credit. If your credit score is in the high 700s, you'll likely get the best rates. If it's lower, your rate quote could easily go past 7%. It's worth checking your credit report and maybe doing some work to boost it before you apply.
  • How Much Home Equity Do You Have? Your home's value compared to what you owe on it is super important. This is called your Loan-to-Value (LTV) ratio. If you have at least 20% equity, you usually won't have to pay Private Mortgage Insurance (PMI) on your new loan, which saves you money.
  • Timing and Locking Your Rate: Rates change daily, sometimes even hourly! If you see a rate you like, be ready to lock it in. This means you agree to that rate for a certain period. You need to be prepared to act fast when you see a good dip, especially with all the news that can cause rates to jump around.

Today's Rates at a Glance

Here's a quick look at the average rates today, June 16, 2026, according to data from Zillow:

Loan Type Average Rate Change from Last Week
30-Year Fixed Refinance 6.70% Down 2 Basis Points
15-Year Fixed Refinance 5.79% Stable
5-Year ARM Refinance 6.25% Stable

My Two Cents on the Market

From my perspective, the slight dip today is a small positive sign, but it doesn't mean we're suddenly heading back to the super low rates of a few years ago. The economy is still holding strong, and that's the main reason rates are staying put. For most people, refinancing right now is only a good idea if you bought a home recently with a high rate, or if you absolutely need to pull out cash. If you're thinking about it, my best advice is to do your homework, get your finances in order, and be ready to act when the time is right. Don't chase rates too hard, but be aware of when a good opportunity presents itself.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 15: Rates Dip Easing Monthly Housing Costs for Buyers

June 15, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of Monday, June 15, 2026, the average rate for a 30-year fixed-rate mortgage has dipped slightly to 6.35%, offering a small but welcome breather for potential homebuyers. While this is a tiny step down, it's important to understand what this means for your wallet and how it fits into the bigger economic picture.

Today's Mortgage Rates, June 15: Rates Dip Easing Monthly Housing Costs for Buyers

A Closer Look at Today's Numbers

It's always a good idea to know the exact figures, and according to the latest data from Zillow, here's how things are shaping up today for purchase loans:

Loan Type Today's Rate Change from Yesterday Comparison to Refi Rate
30-year fixed 6.35% Down 1 basis point 1 basis point higher
15-year fixed 5.78% Down 7 basis points 5 basis points lower
5/1 ARM 6.30% Down 6 basis points 5 basis points higher

It's interesting to see the 15-year fixed rate making a more significant move downwards today, which might catch the eye of those looking for shorter-term commitment and lower overall interest paid. The 30-year fixed rate, while only nudging down a bit, remains the benchmark for many.

Why Are Rates Doing What They're Doing?

Understanding mortgage rates isn't just about the numbers; it's about grasping the forces that push them up and down. Right now, a few big things are keeping mortgage rates a bit higher than we might like.

First off, the job market is still surprisingly strong. When lots of people have jobs, the economy is humming along, and this makes the Federal Reserve less likely to lower its main interest rate. Think of it this way: if everyone's earning money, there's less pressure to make borrowing super cheap. The recent news of 172,000 jobs added in the U.S. economy is a clear sign of this resilience.

Then there's inflation, which has crept back up to around 4.2%. Inflation is like a hidden tax on your money. When prices go up, the money you have buys less. Lenders, who are essentially lending you money that will be paid back later, need to make sure the money they get back is worth as much as the money they lent out. So, when inflation is higher, they need to charge more interest to make it worth their while. This puts upward pressure on bond yields, which mortgage rates tend to follow.

Speaking of bond yields, the 10-year Treasury yield has been quite jumpy, even going above 4.5%. Why do we care about Treasury yields? Because mortgage rates often move hand-in-hand with them. Global events, like the ongoing tensions in the Middle East and their impact on oil prices, are making these yields very unpredictable. When there's uncertainty, investors often move their money around, and this can cause yields to spike.

Are We Saving Money Compared to Last Year?

This is a question I get asked a lot, and the answer is a bit nuanced: yes, but only a little.

Last year, around this time, the average 30-year fixed rate was hovering around 6.84% to 6.85%. Today's rate of 6.35% is about 0.50% lower. On a large loan, this can mean saving a noticeable amount of money over the life of the loan.

However, let's talk about the monthly payment reality. While today's rates are better than last year's peak, they're still higher than the 6.0% rates we saw earlier this spring. And here's the kicker: home prices haven't exactly come down. They've stayed pretty high. So, even with slightly lower rates, the combination of elevated home prices and rates above 6.5% means that monthly housing payments are stretching many buyers' budgets to their limits. It’s a tough balancing act for many trying to achieve homeownership right now.

A Quick Look at Other Loan Types

It's not just the 30-year fixed that matters. Here's a snapshot of other rates, also according to Zillow:

  • 20-year fixed: 6.10%
  • 7/1 ARM: 6.45%

For those with military service, VA loans often present a more attractive option:

  • 30-year VA: 5.82%
  • 15-year VA: 5.34%
  • 5/1 VA: 5.64%

You can see that the VA loan rates are consistently lower across the board, which is a significant benefit for eligible borrowers.

My Two Cents: What I'm Seeing on the Ground

From my perspective, the market is still a bit of a puzzle. We're seeing these small fluctuations in rates, but the underlying economic factors – like that persistent inflation and a strong job market – are acting like anchors, preventing rates from dropping significantly.

For buyers, this means patience and smart shopping are key. Don't just jump at the first rate you see. Shopping around is crucial. Comparing offers from different lenders can save you thousands. And if you're considering an ARM, like the 5/1, make sure you fully understand the risks and rewards. While the initial rate might be lower, it could jump up after the introductory period.

For those looking to refinance, today might be a good day to at least check your options, especially if you have a 15-year loan. Even a small drop can add up. However, if your current rate is significantly lower than today's offerings, it might not be the right time to refinance just yet.

It’s a dynamic market, and staying informed is your best strategy. Keep an eye on economic news, and remember that your personal financial situation is the most important factor in deciding when and how to lock in a mortgage.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

  • « Previous Page
  • 1
  • …
  • 20
  • 21
  • 22
  • 23
  • 24
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Today’s Mortgage Rates, September 16: Rates Hold Near 7% as Fed Meeting Concludes Today
    September 16, 2026Marco Santarelli
  • Mortgage Rates Today, September 16, 2026: 30-Year Refinance Rate Rises by 24 Basis Points
    September 16, 2026Marco Santarelli
  • Kevin Warsh Inflation Is a Choice Quote Signals a Certain Interest Rate Hike Today
    September 16, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...