Norada Real Estate Investments

  • Home
  • Markets
  • Properties
  • Membership
  • Podcast
  • Learn
  • About
  • Contact

Mortgage Rates Today, June 13, 2026: 30‑Year Refinance Rate Rises by 12 Basis Points

June 13, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of today, June 12, 2026, if you're looking to refinance your home, you'll find that the national average for a 30-year fixed refinance rate has nudged up to 6.80%, marking a 12-basis-point increase from yesterday. This means that securing a new mortgage to replace your current one just got a little more expensive, especially if you're aiming for that popular 30-year term.

It feels like just yesterday we were talking about rates hovering closer to the 6.00% mark, and now we're consistently seeing them higher. I know it can be a bit disheartening when you see rates ticking up, especially when you've been watching them closely, hoping for that perfect moment to save some money. But understanding why these rates are moving is half the battle, and I'm here to break it down for you in plain English.

Mortgage Rates Today, June 12, 2026: 30-Year Refinance Rate Rises by 12 Basis Points

What's Driving These Rate Hikes?

You might be wondering, “Why are mortgage rates going up now?” It's a complex puzzle, but a few big pieces are definitely playing a role.

One of the main culprits is inflation. Remember those recent reports from the U.S. Labor Department? The May Consumer Price Index (CPI) showed inflation soaring at a 4.2% year-over-year clip, the highest it's been in over three years. When inflation is high, it makes the money we earn today worth less tomorrow. For investors who buy bonds, this means they need to get paid more interest to make it worthwhile, and that, in turn, pushes up mortgage rates.

Then there's the jobs market. The economy is still adding jobs, with May seeing 172,000 new positions, which is more than many expected. A strong job market usually means people are spending money, and that tells the financial world the economy isn't slowing down as much as some might like. This can make the Federal Reserve hesitant to lower interest rates, which directly influences mortgage rates.

Speaking of the Federal Reserve, they've decided to keep their target federal funds rate steady. With inflation still a concern and the job market humming along, they're in no rush to make borrowing cheaper. This “higher-for-longer” stance from the Fed is a big reason why we're seeing mortgage rates stay put at these higher levels.

Finally, we can't ignore what's happening with government debt. As the U.S. Treasury issues more bonds to manage the national debt, this massive supply can drive up the yields on those bonds. And guess what? When Treasury yields go up, mortgage rates tend to follow right behind them.

Refinance Rates Today: A Closer Look

Let's get down to the numbers, straight from Zillow's latest data. It's important to remember that these are national averages, and your personal rate could be a bit different based on your credit score, loan amount, and the lender you choose.

Here's a snapshot of where things stand as of Saturday, June 13, 2026:

Loan Term Current Average Rate Change from Previous Day Change from Previous Week
30-Year Fixed 6.80% +12 basis points +8 basis points
15-Year Fixed 5.93% +12 basis points –
5-Year ARM 7.04% – –

(Source: Zillow Lender Marketplace via Yahoo Finance)

As you can see, both the 30-year and 15-year fixed refinance rates have moved up by 12 basis points in the last day. The 30-year fixed rate is now 8 basis points higher than it was at this time last week. It's a noticeable uptick, and it emphasizes the “sticky” nature of these rates, meaning they're not moving down quickly.

My Take: What Does This Mean for You?

From my perspective, watching these rates fluctuate has become a daily ritual for many homeowners. We're in a bit of a holding pattern, where rates are high, but they're not necessarily skyrocketing. The key takeaway is that rates have been relatively stable in a higher range since February 2026, when 30-year rates briefly dipped close to 6.00%.

If you're thinking about refinancing, it's crucial to understand that what constitutes a “good” rate is quite subjective these days. According to some financial analyses from June 2026, snagging a rate at or just above 6.00% is still considered a solid deal. So, while today's 6.80% might feel high, it's important to compare it to the broader trend and your own financial goals.

Should You Refinance Now?

This is the million-dollar question, isn't it? My advice is always to run the numbers and see if it makes sense for your specific situation.

  • Consider Shorter Terms: If your main goal is to save money on interest over the life of your loan, and not just lower your monthly payment, then looking at a 15-year fixed refinance might be a smart move. As you can see, those rates are generally lower than the 30-year options.
  • Break-Even Analysis is Key: Don't forget about the costs involved in refinancing. You'll typically have closing costs, which can range from 2% to 6% of your loan amount. You need to be sure you plan to stay in your home long enough for the savings from your lower monthly payment to cover these upfront fees. I always advise my clients to calculate their “break-even point” before they commit.
  • Locking vs. Floating: This is a strategic decision. With the Fed's stance and potential economic shifts, rates could go up or down. If you find a rate you're happy with, consider locking it in. This protects you from any potential increases before your loan closes. Some lenders offer a “float-down” option, which allows you to take advantage of lower rates if they happen to drop before you finalize your loan, but this isn't always available or might come with a fee.

The mortgage market is always moving, and while today's increase might feel significant, it's part of a larger trend. My expertise tells me that the best approach is always to stay informed, understand the forces at play, and make a decision that aligns with your personal financial roadmap.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 12: Rates Slip to Mid‑6% Range, Buyers Find Small Advantage

June 12, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of today, June 12, 2026, the average 30-year fixed-rate purchase mortgage is sitting at 6.36%, a slight dip from previous days, but the overall picture for mortgage rates remains complex and influenced by a mix of economic forces and global events.

It feels like just yesterday we were talking about mortgage rates in the 3% and 4% range, and now, seeing them inch back down to the mid-6% mark is a welcome, albeit cautious, development for many potential homebuyers. We’re seeing some encouraging signs, but the ground beneath us still feels a bit shaky.

Today's Mortgage Rates, June 12: Rates Slip to Mid‑6% Range, Buyers Find Small Advantage

The Latest Numbers: What the Data Tells Us

First off, let's get to the numbers you're likely looking for. According to the latest data from Zillow, here’s a snapshot of mortgage rates as of this morning:

Loan Type Today's Rate
30-year fixed 6.36%
20-year fixed 6.33%
15-year fixed 5.85%
5/1 ARM 6.36%
7/1 ARM 6.45%
30-year VA 5.87%
15-year VA 5.50%
5/1 VA 5.70%

As you can see, the 30-year fixed-rate, which is the most popular choice for homebuyers, saw a small drop of 4 basis points, bringing it down to 6.36%. The 15-year fixed also saw a slight decrease, while the 5/1 Adjustable-Rate Mortgage (ARM) moved lower by a more noticeable 15 basis points.

It’s also important to look at the broader picture, as different organizations track these rates. Freddie Mac’s data, which often represents weekly averages, shows similar trends. They report that 30-year fixed conforming rates are hovering between 6.52% and 6.55%. While this is a step up from where we were in early 2026, it's still a relief compared to the 7% and higher peaks we experienced in late 2023.

Why Are Rates Moving Like This? It's a Two-Pronged Attack.

The mortgage market isn't moving in a straight line, and frankly, it hasn't been for a while. There are two major forces at play right now that are creating this back-and-forth:

  1. Sticky Inflation: The latest Consumer Price Index (CPI) report showed inflation jumping to 4.2% in May. This is a significant increase, and a big reason for it is rising energy costs. The conflict in Iran has unfortunately put upward pressure on oil prices, which then ripples through the economy and affects the cost of almost everything else. This is a serious concern because the Federal Reserve’s target for inflation is a much lower 2%.
  2. Global Tensions: The geopolitical situation, particularly concerning the situation in Iran, is directly impacting energy markets. When there’s uncertainty and instability in major oil-producing regions, it almost always translates into higher energy prices. This, in turn, fuels inflation, which is a primary driver of mortgage rate movements.

What the Fed is Doing (and Not Doing)

Because inflation is proving to be stubborn and the job market remains strong (with about 172,000 jobs added in May), the Federal Reserve is taking a pause. They are holding their benchmark interest rate steady. What this means for us is that Wall Street traders are no longer expecting rate cuts anytime soon. In fact, some economists are even talking about the possibility of a rate hike by winter if inflation doesn't start to cool down.

Where Are Rates Headed Next? My Two Cents.

Looking ahead, I don't see mortgage rates plunging back into the 3s or 4s anytime soon. The general consensus among experts, including major players like Fannie Mae and the Mortgage Bankers Association, is that we’ll likely see 30-year fixed rates stay in the 6.3% to 6.5% range for the rest of the year. It’s a new normal, and trying to time the market for a massive drop is a risky game.

From my experience, trying to perfectly time the mortgage market is like trying to catch lightning in a bottle. If you find a home that truly fits your needs and your budget, my advice is to seriously consider making a move.

Strategic Advice for Borrowers Today

Given this dynamic environment, here's what I'm telling people:

  • Don't Hold Your Breath for Pandemic-Era Rates: Seriously, forget about the 3% and 4% rates for now. The 5% to 6% range is looking more like the standard. Waiting too long for a significant drop could mean missing out on a home or facing even higher rates if inflation keeps climbing.
  • Competition is Coming Back: If rates do eventually dip, you can bet there will be a flood of buyers re-entering the market. This is going to create intense competition, potentially driving home prices up even further. Buying now, when there might be a little less frenzy, could be a smart move.
  • “Marry the House, Date the Rate”: This is a mantra I’ve shared before, and it’s more relevant than ever. Focus on finding a home you love and can comfortably afford. If rates drop significantly down the line, you always have the option to refinance and lower your monthly payments and overall interest paid over the life of the loan. It’s much easier to change your interest rate than to change your house.
  • Shop Around, Seriously: The difference between lenders can be huge, especially with market volatility. Don't just go with the first lender you talk to. Compare quotes from different banks, credit unions, and mortgage brokers. You can save thousands in fees and get a better Annual Percentage Rate (APR) by doing your homework.

The mortgage market is a puzzle, and right now, there are a lot of pieces in motion. Staying informed and making strategic decisions based on your personal circumstances is key.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?
Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 12, 2026: 30‑Year Refinance Rate Drops by 10 Basis Points

June 12, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

Good news for homeowners looking to save some money: the 30-year fixed refinance rate has seen a welcome dip today, June 12, 2026, dropping by a significant 10 basis points from last week. This means that the average rate is now sitting at 6.62%, down from 6.72% the previous week, according to Zillow. While this might seem like a small change, for many, it’s enough to make refinancing a much more attractive option to lower those monthly payments.

Mortgage Rates Today, June 12, 2026: 30‑Year Refinance Rate Drops by 10 Basis Points

It’s been a bit of a rollercoaster ride for mortgage rates this year, and honestly, keeping up can feel like trying to predict the weather. After a nice little dip earlier in the year, rates have been creeping back up, making many of us wonder if those low-rate dreams were over. But this recent drop in the 30-year fixed refinance rate is a promising sign. It suggests that while the overall trend might still lean towards “higher for longer,” there are moments of opportunity for homeowners.

For anyone considering refinancing, this movement is definitely worth paying attention to. It’s not just about chasing the absolute lowest number, but about finding the right moment that makes the most financial sense for your specific situation.

What's Going On with These Rates?

So, why the small but significant drop today? It's a combination of factors, and understanding them can help you make smarter decisions.

Think of interest rates like a complex recipe. You need the right ingredients (economic signals) to get the desired outcome (mortgage rates).

  • Inflation’s Stubbornness: Even though the Federal Reserve has been working hard to tame inflation, it's proving to be a bit of a tough nut to crack. They've held steady on interest rates for a while now, and as long as inflation is still a concern, they’re unlikely to start cutting rates dramatically anytime soon. This “sticky inflation” is a big reason why rates have been higher than we saw in previous years.
  • A Strong Job Market: On the flip side, the job market is doing pretty well. We’ve seen some really positive reports, showing that the economy is still chugging along. When the economy is strong, it means there's more demand for things, which can sometimes push prices up (hello, inflation again!). This resilience in the job market also tells the Fed that they don’t need to rush into lowering rates.
  • Treasury Yields on the Move: Mortgage rates tend to follow the 10-year Treasury yield pretty closely. When economic news is good or there's some global uncertainty (like tensions in the Middle East), these yields can spike. And guess what? Higher Treasury yields usually mean higher mortgage rates.

The Current Rate Picture: A Snapshot

Here’s a look at the national average refinance rates as of today, June 12, 2026, according to Zillow:

Loan Type Current Average Rate Change from Previous Week
30-Year Fixed Refinance 6.62% Down 10 basis points
15-Year Fixed Refinance 5.83% Up 7 basis points
5-Year ARM Refinance 6.75% No change

As you can see, while the 30-year fixed rate is down, the 15-year fixed rate has nudged up a bit, and the 5-year ARM is holding steady. This highlights the importance of looking at the specific loan type that fits your needs.

Is Refinancing Right for You Now?

This is the million-dollar question, isn't it? With rates hovering in the mid-6% range for the 30-year fixed, it’s not as clear-cut as it was when rates were significantly lower. My own experience tells me that not everyone should jump on a refinance just because the headline number looks good.

Here's what I think you should be considering:

  1. Your Break-Even Point is Key: Forget those old rules of thumb. The most important thing is to figure out how long it will take for your savings to cover the costs of refinancing. This is your break-even point. You can calculate it by dividing your total closing costs by the amount you'll save each month.

    Formula:
    Break-Even Months = Total Closing Costs / Net Monthly Savings

    If your break-even point is, say, 18 months, and you plan to move or refinance again before then, it might not be worth it.

  2. What Rate Did You Lock In? Data suggests that a large majority of homeowners (around 82.8%) have mortgages with rates below 6%. If you're in this group, a simple rate-and-term refinance probably isn't going to save you enough money to justify the costs. Refinancing makes more sense if:
    • You originally got your mortgage when rates were very high (think above 7.5%), which was common in late 2023 and 2024.
    • You're looking to do a cash-out refinance. This can be a smart move to consolidate high-interest debt (like credit cards) or to fund important home improvements.
  3. Understand Your Loan Options: As the table showed, rates can vary quite a bit depending on the type of loan you choose.
    • Conventional 30-Year Fixed: Around 6.68%
    • Conventional 15-Year Fixed: Around 6.06%
    • FHA Refinance: Around 6.31%
    • VA Refinance: Around 5.86%

    It's essential to compare these options and see which one aligns with your financial goals and how long you plan to stay in your home.

  4. Boost Your Credit and Shop Around: Your credit score and debt-to-income ratio (DTI) play a huge role in the rate you'll be offered. Lenders add a “spread” to the base Treasury rate to account for risk, and a better financial profile can help reduce that spread.
    • Check your credit reports: Make sure there are no errors that could be hurting your score.
    • Lower your DTI: Paying down debt can significantly improve your borrowing power.
    • Get multiple quotes: Don't just go with the first lender you talk to. Shopping around and getting quotes from at least three different lenders can potentially save you a substantial amount of money, sometimes up to half a percentage point.

The Outlook for the Rest of 2026

Looking ahead, the general consensus from major housing forecasters like Fannie Mae is that we should expect rates to remain “sticky.” This means they likely won't plummet dramatically anytime soon. They're projecting that the average 30-year fixed rate will hover around 6.4% for the remainder of 2026 and into early 2027.

While this recent dip is a nice breather, it's wise to prepare for rates to stay somewhat elevated compared to the rock-bottom rates we saw a few years ago. The key is to stay informed, understand your personal financial picture, and be ready to act when a refinance opportunity genuinely benefits you.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 11: Mixed Moves Impact Buyer Budgets & Refinancing

June 11, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of today, June 11th, the mortgage rate scene is a mixed bag, with some loan types inching up while others see a slight dip. For those eyeing a new home or considering refinancing, understanding these shifts is crucial. The 30-year fixed-rate purchase loan is currently at 6.40%, up from yesterday. Similarly, the 20-year fixed purchase loan is also on the rise, now at 6.34%. However, there's a glimmer of good news for some: the 15-year fixed purchase loan has dropped to 5.86%, and the 5/1 ARM purchase rate is down to 6.51%.

Today's Mortgage Rates, June 11: Mixed Moves Impact Buyer Budgets & Refinancing

It's easy to get caught up in the daily numbers, and I often find myself scanning these updates too. But the real story isn't just the single-digit changes; it's about the bigger picture and what these rates mean for your financial decisions. I've been following the housing market and mortgage trends for a while now, and I can tell you that while these figures from Zillow are helpful snapshots, there's a lot more nuance beneath the surface.

What the Numbers Tell Us Today

Let's break down what Zillow's data is showing us today, June 11th:

Loan Type Rate (Today)
30-year fixed 6.40%
20-year fixed 6.34%
15-year fixed 5.86%
5/1 ARM 6.51%
7/1 ARM 6.46%
30-year VA 5.89%
15-year VA 5.54%
5/1 VA 5.70%

It’s interesting to see the 30-year fixed rate holding steady around the 6.45% to 6.55% mark. This suggests a market that’s a bit stuck in its ways, not making big moves up or down. While this is certainly better than the nearly 7% we saw last year, it's a stark reminder of how quickly things can change. Remember that brief period earlier this year when rates dipped closer to 6%? That felt like a real possibility for a while, but renewed economic worries have pushed them back up.

Industry leaders like Fannie Mae and the Mortgage Bankers Association are forecasting that these rates will likely stay put for the rest of the year, hovering between 6.1% and 6.5%. This isn't exactly exciting news for buyers hoping for a quick drop, but it does offer a degree of predictability.

The Hidden Forces: Why Rates Move

Mortgage rates don't just change on a whim. They're deeply connected to the 10-year U.S. Treasury yield, which in turn is influenced by bigger economic factors. Think of it like a chain reaction.

What's Pushing Rates Up?

  • Stubborn Inflation: We're seeing inflation figures that are higher than the Federal Reserve likes (around 3.8% to 4.2%). When money loses its value faster, investors demand higher returns on their investments, which pushes bond yields – and mortgage rates – up.
  • Global Unrest: International conflicts, especially those affecting oil prices, can create a ripple effect. Higher energy costs often mean higher prices for almost everything else, making inflation even worse.
  • Fed's Pause Button: The Federal Reserve has held interest rates steady for a while now. The idea of them cutting rates has pretty much vanished, and some are even whispering about the possibility of them raising rates again. This uncertainty keeps lenders cautious and rates higher.

What Could Potentially Bring Rates Down?

  • A Slowing Economy: If we start seeing signs that the job market is cooling or the economy is taking a breather, it could ease inflation fears and pull mortgage rates back down.
  • Long-Term Stability: Once the global supply chain issues and economic disruptions start to settle, forecasters like those at the National Association of Home Builders (NAHB) believe rates will gradually drift back below that 6% mark. This isn't happening tomorrow, but it's a goal on the horizon.

My Take: Navigating Today's Market

From my perspective, trying to perfectly time the market to snag the lowest possible rate is a losing game right now. The real focus needs to be on what's manageable for you and your finances. I’ve seen too many people miss out on great homes because they were waiting for a magical rate drop that never came, only to see prices skyrocket when rates did eventually fall slightly.

Advice for Homebuyers: “Marry the House, Date the Rate”

This is a saying I’ve heard a lot, and I truly believe in it for today’s market.

  • Don't Wait for Rates to Plummet: If you’ve found a home that fits your needs and budget, don't put your dreams on hold indefinitely waiting for rates to dive below 6%. A sudden drop could bring a flood of buyers, leading to bidding wars and higher prices.
  • Lock In Your Rate: Daily rate swings can add hundreds of dollars to your monthly payment. Talk to your lender about a rate lock. This protects your rate for a set period, giving you peace of mind.
  • Shop Around: Seriously, this is one of the easiest ways to save money. Get quotes from at least three different lenders. You might be surprised how much difference it makes – sometimes up to half a percentage point!
  • Consider Buying Points: If you have some extra cash, buying discount points can permanently lower your interest rate. It’s like paying a fee upfront for a lower monthly payment for the life of the loan.

Advice for Current Homeowners: Be Strategic with Refinancing

If you’ve owned your home for a while, you might be thinking about refinancing.

  • Evaluate Carefully: If your current rate is above 7.3% (from the recent highs), refinancing into a mid-6% rate makes a lot of sense. However, if your rate is already below 6.5%, you might want to hold off. The costs of refinancing might outweigh the savings.
  • Equity Loans vs. HELOCs: If you need to tap into your home's equity for renovations or other expenses, consider fixed-rate home equity options. Home Equity Lines of Credit (HELOCs) are variable, meaning their rates will likely stay high as long as the Federal Reserve keeps its benchmark rate elevated.

The mortgage market today is certainly a complex puzzle. By understanding the forces at play and focusing on smart strategies, you can make the best decisions for your own financial journey.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 11, 2026: 30‑Year Refinance Rate Drops by 6 Basis Points

June 11, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

The good news for homeowners looking to refinance is that 30-year fixed refinance rates took a slight dip today, June 11, 2026, settling at an average of 6.69%. This marks a 6-basis-point decrease from yesterday's average of 6.75%, according to data released by Zillow. While this might seem like a small move, it's a welcome change in what's been a rather steady, albeit high, interest rate environment. It's not a dramatic shift, but in the current market, any downward movement is worth paying attention to.

Mortgage Rates Today, June 11, 2026: 30‑Year Refinance Rate Drops by 6 Basis Points

What's Happening with Refinance Rates Right Now?

Let's break down the numbers as of today, June 11, 2026:

  • 30-Year Fixed Refinance Rate: Down to 6.69%. This is the rate most people are familiar with for home loans.
  • 15-Year Fixed Refinance Rate: Saw a small increase, now at 5.85%. This is typically for those looking to pay off their mortgage faster.
  • 5-Year Adjustable-Rate Mortgage (ARM) Refinance Rate: Holding steady at 6.31%. ARMs start with a fixed rate that can change later, usually annually.

Compared to last week, the 30-year fixed refinance rate is down by 3 basis points from 6.72%. So, while today saw a 6-basis-point drop, the trend over the past week has also been slightly downward for this popular loan type.

Why the Slight Dip and What Does it Mean for You?

It’s easy to get excited about any drop in mortgage rates, but it’s important to understand the bigger picture. Based on my experience, this current environment is best described as “higher for longer.” Experts are largely agreeing that we probably won't see rates drop significantly below 6% anytime soon.

Several factors are keeping rates where they are:

  • Stubborn Inflation: Prices for everyday goods and services are still higher than the 2.5% target many economists are aiming for. This persistent inflation makes lenders hesitant to offer lower rates, as the money they get back in the future won't buy as much.
  • A Cautious Federal Reserve: The Federal Reserve, which influences interest rates across the economy, has hit pause on its rate cuts. Even though they had started to lower rates, strong job numbers and that stubborn inflation have made them take a step back. They want to make sure the economy is truly stable before making big moves.
  • Bond Market Realities: Mortgage rates are closely tied to the performance of U.S. Treasury bonds, particularly the 10-year Treasury yield. Right now, this yield is hovering around 4.5%. This elevated yield is partly due to the growing amount of debt the U.S. government holds. When the government borrows a lot, it can push up the cost of borrowing for everyone else.

My take on this is that we're in a period of relative stability, but at a higher cost than we've seen in recent years. The days of sub-3% mortgage rates feel like a distant memory.

Expert Predictions: What's Next?

Looking ahead, major housing and finance organizations like Fannie Mae and the Mortgage Bankers Association (MBA) are predicting that 30-year fixed mortgage rates will likely stay in the mid-to-high 6% range for the rest of 2026. They are projecting averages between 6.3% and 6.5% through the end of the year.

This means that while we might see small fluctuations like today's drop, a major plunge in rates isn't on the immediate horizon.

Smart Moves for Borrowers in Today's Market

Navigating this “higher-for-longer” mortgage rate environment requires a thoughtful approach. Here's what I advise:

  • Don't Get Caught in the “Waiting Game”: It's tempting to wait for rates to drop significantly before buying or refinancing. However, if rates do fall sharply, you'll likely see a flood of buyers rush into the market. This surge in demand can push home prices up, potentially canceling out any savings you might have gotten from a lower interest rate.
  • Focus on the Purchase Price: Remember, you can always refinance your mortgage later if rates go down. However, you can't change the price you paid for the house itself. Make sure the total monthly payment – including principal, interest, taxes, and insurance (PITI) – fits comfortably within your budget right now.
  • Boost Your Credit Score: The best interest rates are always reserved for borrowers with excellent credit. To get close to the lower end of the current rates, you’ll need to be diligent about your credit.
    • Check your credit reports for any errors and get them fixed.
    • Pay down credit card balances to lower your debt-to-income (DTI) ratio.
    • Avoid opening new credit accounts while you're in the process of buying or refinancing a home.
  • Explore Creative Financing: Talk to your lender about options like rate buydowns.
    • A permanent rate buydown lets you pay an upfront fee to lower your interest rate for the entire life of the loan.
    • A temporary rate buydown (like a 2-1 or 1-0 buydown) lowers your rate by a larger amount for the first year or two. For example, a 2-1 buydown means your rate is 2% lower in the first year and 1% lower in the second year. This can provide welcome relief as you settle into your new home.

In Conclusion

Today's 6-basis-point drop in the average 30-year fixed refinance rate to 6.69% is a positive sign, but it doesn't signal a major shift in the market. My professional opinion is that borrowers should focus on finding a home that fits their budget and work on improving their credit to secure the best possible rate available today. Refinancing is always an option down the road.

🏡 Real Estate Investment: Tennessee vs Florida

Ribbon Ln Property
Franklin, TN
🏠 Property: Ribbon Ln
🛏️ Beds/Baths: 2 Bed • 2.5 Bath • 1662 sqft
💰 Price: $569,999 | Rent: $3,000
📊 Cap Rate: 5.1% | NOI: $2,415
📅 Year Built: 2022
📐 Price/Sq Ft: $343
🏙️ Neighborhood: A-

VS

Chamberlain Blvd Property
Port Charlotte, FL
🏠 Property: Chamberlain Blvd
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Tennessee’s newer rental with higher NOI vs Florida’s A+ property with strong yield. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 10: Buyer Costs Ease Slightly as 30‑Year Fixed Drops to 6.33%

June 10, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of June 10th, most mortgage rates are showing a slight dip compared to yesterday, with the notable exception of the 15-year fixed loan, which has nudged upwards. This means there might be a small window of opportunity for some buyers, but the overall picture remains one of cautious movement rather than a dramatic shift.

It feels like just yesterday we were talking about rates heading into the low 6s, and now, here we are, back to watching the numbers closely. As someone who's been following the housing market for a good while now, I know how much even small fluctuations can mean for your budget. So, let's dive into what's happening with today's mortgage rates and what it could mean for you.

Today's Mortgage Rates, June 10: Buyer Costs Ease Slightly as 30‑Year Fixed Drops to 6.33%

What the Numbers Say Today

The most recent data gives us a snapshot of where things stand on June 10, 2026. It's important to remember these are national averages, and your specific rate will depend on your credit score, down payment, and the lender you choose.

Here's a breakdown of what Zillow is reporting for purchase loans:

Loan Type Rate Today (June 10) Change from Yesterday
30-year fixed 6.33% Down 8 basis points
20-year fixed 6.26% Down 14 basis points
15-year fixed 5.89% Up 8 basis points
5/1 ARM 6.26% Down 14 basis points

It’s interesting to see the 30-year and 20-year fixed rates moving down, while the 15-year is inching up. This suggests a bit of a mixed bag. The 5/1 ARM is also showing a nice dip, which could be attractive for those looking for a lower initial payment.

For those who have served our country, VA loans also have their own set of rates:

Loan Type Rate Today (June 10)
30-year VA 5.80%
15-year VA 5.50%
5/1 VA 5.69%

Why Are Rates Moving Like This?

It’s easy to get caught up in just the numbers, but understanding why they move is crucial. Honestly, the mortgage rate environment right now feels a bit like being on a rollercoaster that’s mostly stuck on a middle track – it's volatile and seems determined to stay within a certain range. We’re seeing rates hovering between 6.0% and 6.7%, not really breaking free.

A big player in this is the ongoing geopolitical situation. Remember earlier this year when rates flirted with dipping below 6.0%? Well, events in places like the Middle East, specifically involving Iran and the Strait of Hormuz, have caused oil prices to spike. This, in turn, has made it harder for inflation to cool down. We’re looking at a US consumer price index (CPI) that’s stubbornly around 3.8%.

On top of that, the Federal Reserve, under its new Chair Kevin Warsh, has made it clear they're not rushing to cut interest rates. The job market is still showing strength, with reports like the 172,000 jobs added in May. This resilience means the Fed is less pressured to stimulate the economy with lower borrowing costs. In fact, some economists are even whispering about the possibility of a rate hike if inflation doesn’t start cooperating. So, any hope of a quick return to those ultra-low rates we saw during the pandemic (think 3% to 4%) is pretty much off the table for the foreseeable future. Housing authorities like Fannie Mae and the Mortgage Bankers Association are adjusting their predictions, suggesting that 30-year fixed rates will likely average between 6.3% and 6.5% for the rest of the year.

What This Means for You: Smart Moves to Make

So, what can you do with this information? It’s all about being strategic.

1. Rethink Your Refinance Plan

  • The Action Plan: If you’re thinking about refinancing, my advice is to only seriously consider it if your current mortgage rate is above 7.125%.
  • The Logic: Moving from a 7.5% rate down to today’s 6.33% would obviously save you money each month. However, if your current rate is already below 6.5%, the closing costs associated with refinancing will likely eat up any savings you’d see. It just doesn't make financial sense in that scenario.

2. Master the Rate Lock Game

  • The Action Plan: If you’re currently under contract to buy a home, be ready to lock in your rate the moment you see a short-term dip in the market.
  • The Logic: Mortgage rates are sensitive to sudden jumps in things like the 10-year Treasury yields and those unpredictable energy markets. If you’re waiting for a rate below 6.0%, you could miss your chance if geopolitical news causes rates to spike again. Acting quickly when you see a favorable movement is key.

3. Consider Shorter Terms or Different Loan Types

  • The Action Plan: Take a close look at how a 15-year fixed loan or a 7/1 Adjustable-Rate Mortgage (ARM) would fit your budget.
  • The Logic: A 15-year fixed loan, while it comes with a higher monthly payment, will save you a significant amount of money in interest over the life of the loan – often more than half of what you’d pay on a 30-year. A 7/1 ARM, on the other hand, offers a lower initial rate for the first seven years. This can provide some breathing room financially while you wait for the broader economic picture to stabilize. It's a trade-off, but a potentially worthwhile one for some.

4. Get Creative with Your Closing Costs

  • The Action Plan: Explore options like negotiating a temporary seller buydown (2-1 or 3-1) or paying for discount points upfront.
  • The Logic: In today’s market, asking the seller to help with a temporary buydown can lower your interest rate by 2% in the first year and 1% in the second year. This can significantly reduce your immediate housing costs, giving you more time to plan for a permanent refinance down the road if rates become more favorable. Paying discount points out-of-pocket is another way to permanently lower your rate, but you need to do the math to ensure it makes sense for how long you plan to stay in the home.

Navigating today's mortgage market requires a good understanding of the numbers and the forces behind them. By staying informed and being proactive, you can make the best decisions for your homeownership journey.

🏡 Real Estate Investment in Indiana and Florida

Indianapolis, IN
🏠 Property: Balboa Dr
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1925 sqft
💰 Price: $190,000 | Rent: $1,600
📊 Cap Rate: 8.1% | NOI: $1,277
📅 Year Built: 1963
📐 Price/Sq Ft: $99
🏙️ Neighborhood: C+

VS

Port Charlotte, FL
🏠 Property: Tyler Ave
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Indiana’s affordable rental with higher cap rate vs Florida’s newer A+ property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 10, 2026: 30‑Year Refinance Rate Rises by 3 Basis Points

June 10, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of Wednesday, June 10, 2026, the average 30-year fixed refinance rate is sitting at 6.75%, marking a slight uptick of 3 basis points from last week. While this movement might seem small, it's part of a larger picture of mortgage rates remaining in a tight, elevated range, especially for those looking to refinance their homes.

Mortgage Rates Today, June 10, 2026: 30-Year Refinance Rate Rises by 3 Basis Points

It’s been a bit of a roller coaster, hasn’t it? Just when you think you have a handle on where mortgage rates are headed, something shifts. I’ve been following this market closely for years, and I can tell you that even minor moves like this one can be telling. For homeowners thinking about refinancing, understanding these nuances is key. It’s not just about the headline number; it’s about what’s driving it and what it means for your financial goals.

What's Pushing Refinance Rates Today?

This slight increase in the 30-year fixed refinance rate isn't happening in a vacuum. Several big economic forces are at play, and they're keeping lenders a bit cautious.

  • A Stronger-Than-Expected Job Market: The latest report from the U.S. Bureau of Labor Statistics painted a pretty rosy picture of May's employment data. More jobs mean a stronger economy, which, in turn, gives the Federal Reserve less reason to rush into lowering its benchmark interest rate. When that benchmark rate stays higher, mortgage rates tend to follow suit.
  • Inflation Isn't Quite Beaten Yet: Even though we've made progress, inflation is still a persistent concern. This “stubbornly high” inflation keeps the yields on longer-term investments, like bonds, elevated. Investors are anxiously waiting for the next Consumer Price Index (CPI) report, which will be a major clue about where inflation is truly heading. The bond market, which mortgage rates are closely tied to, reacts strongly to these kinds of signals.
  • Treasury Yields are Creeping Up: If you’ve been paying attention, you’ll notice that mortgage rates often mirror the performance of the 10-year U.S. Treasury yield. We've seen this yield recently climb back above the 4.5% mark. This upward trend directly influences what lenders can offer on mortgages.
  • Global Jitters: The world stage can also play a role. Ongoing geopolitical tensions and instability in certain regions can create uncertainty in financial markets, including oil and bond prices. This added layer of unpredictability can make lenders more hesitant, leading to slightly higher rates.

The 15-Year Fixed and 5-Year ARM Picture

While the 30-year fixed refinance rate saw a minor bump, other popular options are holding steady:

  • 15-Year Fixed Refinance Rate: This option remains stable at 5.87%. This is often a good choice for those looking to pay off their mortgage faster and save on interest over time, provided they can manage the higher monthly payments.
  • 5-Year ARM Refinance Rate: The current national average for a 5-year Adjustable-Rate Mortgage (ARM) refinance is 6.31%. ARMs can be attractive if you plan to move or refinance again before the fixed period ends, as they often start with lower rates than fixed-rate loans.

What Does This Mean for You Right Now?

Seeing rates tick up, even slightly, can be frustrating, especially if you're a homeowner who locked in a much lower rate a few years ago. Based on my experience, traditional rate-and-term refinances are only a smart move for a smaller group of people right now. The key is to ensure that the savings you'll get from a new loan will actually outweigh the costs of getting that loan.

Here’s my advice for anyone considering a refinance in this market:

  • Know Your Break-Even Point: This is crucial. Calculate exactly how long it will take for the money you save on monthly payments to cover all your closing costs. If you don't plan on staying in your home long enough to “break even,” refinancing might not be the best financial decision.
  • Polish Your Credit Score: Lenders are currently offering their best rates to borrowers with excellent credit. If your score is in the mid-to-high 700s, you're in a strong position. Focus on paying down credit card balances and avoid opening new credit lines right before you apply.
  • Explore Cash-Out Options Carefully: If you need to access your home equity for renovations or to consolidate debt, a cash-out refinance isn't the only game in town. Definitely compare it to a Home Equity Line of Credit (HELOC). A HELOC might be a better fit because it allows you to keep your original, low-rate mortgage intact.
  • Shop Around Like You Mean It: Never settle for the first quote you get. I can’t stress this enough. Get official loan estimates from at least three different lenders – whether they are big banks, credit unions, or online mortgage companies. Compare not just the interest rate but also the Annual Percentage Rate (APR), which includes fees. This is where the real costs are often hidden.

Looking Ahead

The mortgage market is a dynamic beast, influenced by a constant flow of economic data and global events. While the 30-year refinance rate has nudged up by 3 basis points today, June 10, 2026, it's important to see this within the broader context. Rates remain elevated, and smart borrowers will focus on personalized calculations and diligent comparison shopping.

🏡 Out-of-state turnkey real estate investments

Helena, AL
🏠 Property: Village Pkwy
🛏️ Beds/Baths: 3 Bed • 2.5 Bath • 1500 sqft
💰 Price: $300,000 | Rent: $1,925
📊 Cap Rate: 6.4% | NOI: $1,608
📅 Year Built: 2025
📐 Price/Sq Ft: $200
🏙️ Neighborhood: B

VS

Nashville, TN
🏠 Property: Winton Dr
🛏️ Beds/Baths: 3 Bed • 2.5 Bath • 1688 sqft
💰 Price: $360,000 | Rent: $2,100
📊 Cap Rate: 5.5% | NOI: $1,662
📅 Year Built: 2001
📐 Price/Sq Ft: $214
🏙️ Neighborhood: A

Alabama’s newer rental with solid cap rate vs Tennessee’s established A‑rated property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

Today’s Mortgage Rates, June 9: Rates Are in Mid‑6% Range, Buyer Power Shrinks

June 9, 2026 by Marco Santarelli

Today's Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026

As of Tuesday, June 9, 2026, today's mortgage rates are showing a slight uptick, with the average 30-year fixed rate at 6.41%, according to Zillow. This means that if you're looking to buy a home or refinance, you'll find borrowing a little more expensive than yesterday.

Rates are now firmly settled in the mid-6% territory for the most common home loan, the 30-year fixed. I know this can be frustrating for anyone dreaming of homeownership or trying to trim their monthly payments. Let's dive into what's actually happening with these numbers and what it means for you.

Today's Mortgage Rates, June 9: Rates Are in Mid‑6% Range, Buyer Power Shrinks

The numbers are the numbers, but understanding them helps make sense of the market. Here's a breakdown from Zillow for Tuesday, June 9, 2026:

Loan Type Interest Rate
30-year fixed 6.41%
20-year fixed 6.40%
15-year fixed 5.81%
5/1 ARM 6.66%
7/1 ARM 6.74%
30-year VA 5.96%
15-year VA 5.51%
5/1 VA 5.71%

As you can see, the 30-year fixed and 15-year fixed loans have both edged up. The 5/1 ARM, which is a loan where the rate is fixed for five years before adjusting, saw a more significant jump. This suggests that lenders are becoming more cautious about longer-term fixed rates, perhaps anticipating further upward movement.

While these rates are higher than they were a few months ago (they dipped to around 5.98% in February 2026), they're still not at their highest point this year. We saw rates inching towards 6.75% back in May. So, there's some perspective to be had, but the trend lately has been upward.

Why Are Rates Moving Like This? It's Not Just the Fed.

Many people think mortgage rates are directly tied to what the Federal Reserve does with its overnight lending rate. While that influences things, the biggest driver for mortgage rates is actually the 10-year U.S. Treasury note yield. Think of it as the benchmark for longer-term borrowing costs.

Right now, that 10-year Treasury yield is trading around 4.55%. This is a noticeable jump from where it was at the end of last year, which was closer to 4.15%. When investors want more return on their investment in these government bonds, lenders have to increase mortgage rates to stay competitive.

The Big Picture: What's Pushing Yields Up?

So, why is the 10-year Treasury yield climbing? It's a mix of several factors, and understanding them gives you a better handle on where rates might go.

1. Inflation is Stubborn (and Energy Costs Aren't Helping)

This is probably the biggest reason rates are where they are. Inflation fears are keeping a lid on falling bond yields.

  • A Stronger-Than-Expected Economy: The latest jobs report showed that the U.S. economy is still adding jobs, with 172,000 jobs created in May. A healthy job market means people are spending money, and that can keep inflation from cooling down. When the economy is hot, inflation tends to follow.
  • Investor Worries: For lenders and investors who are locking in money for 30 years with a mortgage, they need to be compensated for the risk that inflation will eat away at the value of those future payments. If inflation stays high, they demand higher interest rates.

2. Global Turmoil and Oil Prices

The world stage has a direct impact on our wallets, and unfortunately, it's not in a good way right now.

  • Geopolitical Tensions: Military operations involving Iran have sent crude oil prices soaring, crossing the $115 per barrel mark.
  • The Ripple Effect: When oil prices jump, so do the costs of everything that relies on transportation – shipping, manufacturing, you name it. This surge in energy costs directly fuels inflation concerns here at home. It was a major shock that pushed those 10-year Treasury yields to their highest points in a year and reversed the downward trend we saw in mortgage rates earlier this year.

3. Domestic Debt and Federal Reserve Uncertainty

Our own government's finances and the future direction of interest rate policy also play a significant role.

  • Growing Debt: Big spending and tax packages passed last year have led to a wider U.S. budget deficit. To cover this debt, the U.S. Treasury is issuing a lot more bonds. When there's more supply of something, prices tend to drop, and in the bond market, this means yields go up. More bonds being issued means higher yields to attract buyers, which then pushes mortgage rates higher.
  • What About the Fed? Despite pressure from the President to lower interest rates, the new Federal Reserve Chair, Kevin Warsh, and the persistent economic data suggest that the Fed is likely to hold interest rates steady at their upcoming meeting on June 17. Some experts are even worried that if inflation doesn't cool down, we could see an interest rate hike later this year. This uncertainty can also make markets nervous and contribute to higher yields.

What This Means for You Today

If you're in the market for a home or considering refinancing, it's a good idea to:

  • Get Pre-Approved: Knowing your budget and what you can afford is crucial.
  • Shop Around: Don't just go with the first lender you talk to. Rates can vary significantly between lenders, even on the same day.
  • Understand Your Options: Fixed-rate mortgages offer stability, while ARMs can offer a lower initial rate but come with the risk of future increases.
  • Consider Your Long-Term Goals: How long do you plan to stay in the home? This can influence whether a fixed or adjustable-rate mortgage is a better fit.

The mortgage market is dynamic, and while today's rates are up slightly, understanding the underlying economic forces can help you make more informed decisions. Keep an eye on inflation data and global events, as these will continue to be major influencers of borrowing costs.

🏡 Real Estate Investment in Indiana and Florida

Indianapolis, IN
🏠 Property: Balboa Dr
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1925 sqft
💰 Price: $190,000 | Rent: $1,600
📊 Cap Rate: 8.1% | NOI: $1,277
📅 Year Built: 1963
📐 Price/Sq Ft: $99
🏙️ Neighborhood: C+

VS

Port Charlotte, FL
🏠 Property: Tyler Ave
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Indiana’s affordable rental with higher cap rate vs Florida’s newer A+ property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage, mortgage rates, Today’s Mortgage Rates

Mortgage Rates Today, June 9, 2026: 30‑Year Refinance Rate Rises by 13 Basis Points

June 9, 2026 by Marco Santarelli

Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points

As of today, June 9, 2026, the 30-year fixed refinance rate has seen an increase, now standing at 6.85%. This marks a rise of 13 basis points from the previous week's average of 6.72%, according to Zillow's latest data. While this uptick might seem small, it's part of a broader trend that's making refinancing a trickier proposition for many homeowners.

Mortgage Rates Today, June 9, 2026: 30‑Year Refinance Rate Rises by 13 Basis Points

It feels like just yesterday we were talking about rates hovering around 6% and then surging past 7%. Now, we've settled into a bit of a plateau in the mid-6% range, and today's figures show a slight upward nudge. This plateau has created what I like to call a “refinance paradox.” On one hand, more people are looking to refinance than last year, which sounds like good news. But here's the catch: most of us locked in mortgages with rates well below 5% in recent years. This means only a small fraction of homeowners can actually save money by refinancing their current rate and term.

What's Driving These Rate Changes?

Mortgage rates don't just change on a whim; they're deeply connected to the overall health of our economy. Think of them as a thermometer for broader economic conditions.

  • The 10-Year Treasury Yield: It's a common misconception that mortgage rates follow the Federal Reserve's short-term interest rate adjustments directly. In reality, mortgage rates are more closely tied to the yield on the 10-year U.S. Treasury bond. When economic news suggests growth, these bond yields tend to climb, pushing mortgage rates higher.
  • Stubborn Inflation: Inflation remains a persistent challenge. When prices are high, the long-term value of fixed-income investments, like mortgages, decreases. This forces investors to demand higher yields to compensate, which in turn pushes mortgage rates up. We're seeing this play out, keeping rates from dipping back into the 5% range.
  • Global Headwinds: Ongoing international conflicts, particularly in the Middle East, continue to affect oil prices. Higher energy costs ripple through the economy, increasing shipping and production expenses, which fuels inflation expectations and puts upward pressure on mortgage rates.

Refinance Rates at a Glance (as of June 9, 2026, per Zillow)

Here's a quick look at the national averages for refinance rates today:

Loan Type Current Average Rate Change from Previous Week
30-Year Fixed Refinance 6.85% +13 basis points
15-Year Fixed Refinance 5.87% +2 basis points
5-Year ARM Refinance 6.38% -100 basis points

Note: Rates are national averages provided by Zillow and may not reflect your specific loan offer.

Is Refinancing Right for You Today?

Given these shifting rates, it's crucial to be strategic if you're considering a refinance. Gone are the days when a 2% drop in rates was the magic number to trigger a refinance. In today's market, even a 1% reduction can translate into significant monthly savings, potentially hundreds of dollars.

Here’s what I always advise my clients to consider:

  • Your Credit Profile: The advertised rates, like the 6.85% for a 30-year fixed refinance, are typically reserved for borrowers with excellent credit. Before you even start shopping, take a close look at your credit report. Pay down credit card balances and address any recent inquiries. The cleaner your credit, the better your chances of securing the best rates.
  • The 1% Break-Even Rule: Don't dismiss refinancing if you only stand to save 1% on your rate. Calculate your closing costs and divide them by your monthly savings. This will tell you how long it takes to recoup your upfront expenses. If that timeline works for you, it's likely worth exploring.
  • Loan-to-Value (LTV) Ratio and Conforming Limits: Keep an eye on your home's value and your outstanding loan balance. If your loan amount exceeds conforming limits (which are $766,550 in most areas as of now), you'll be looking at “jumbo” loan rates, which are typically higher. Also, try to keep your loan balance below 80% of your home's appraised value to avoid paying for Private Mortgage Insurance (PMI).

My Take on the Current Market

From my perspective, this period of fluctuating but generally elevated rates requires patience and a sharp eye. The refinance market isn't as broad as it was a couple of years ago, but for those who can still benefit, acting with informed caution is key. It’s not about chasing the lowest possible rate, but about finding a rate that makes financial sense for your unique situation.

The 5-year Adjustable Rate Mortgage (ARM) refinance rate dropping a full percentage point to 6.38% is certainly noteworthy. This could be an attractive option for those who plan to sell or refinance again before the fixed period ends. However, it’s crucial to understand the risks associated with ARMs, as rates can increase after the initial fixed period.

Ultimately, the decision to refinance is deeply personal. It depends on your financial goals, your risk tolerance, and the specific numbers for your situation. Today's slight uptick in 30-year fixed rates is a reminder that the market is dynamic. Staying informed and working with a trusted advisor will be your best bet for navigating these waters successfully.

🏡 Out-of-state turnkey real estate investments

Helena, AL
🏠 Property: Village Pkwy
🛏️ Beds/Baths: 3 Bed • 2.5 Bath • 1500 sqft
💰 Price: $300,000 | Rent: $1,925
📊 Cap Rate: 6.4% | NOI: $1,608
📅 Year Built: 2025
📐 Price/Sq Ft: $200
🏙️ Neighborhood: B

VS

Nashville, TN
🏠 Property: Winton Dr
🛏️ Beds/Baths: 3 Bed • 2.5 Bath • 1688 sqft
💰 Price: $360,000 | Rent: $2,100
📊 Cap Rate: 5.5% | NOI: $1,662
📅 Year Built: 2001
📐 Price/Sq Ft: $214
🏙️ Neighborhood: A

Alabama’s newer rental with solid cap rate vs Tennessee’s established A‑rated property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals in 2026

Mortgage rates remain high in 2026, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT 2026 INVESTMENT LISTINGS JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Mortgage Rates Predictions Backed by 7 Leading Experts: 2025–2026
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: mortgage rates, Mortgage Rates Today, Refinance Rates

30-Year Fixed Mortgage Rate Drops by 37 Basis Points Year-Over-Year

June 9, 2026 by Marco Santarelli

30-Year Fixed Mortgage Rate Drops by 37 Basis Points Year-Over-Year

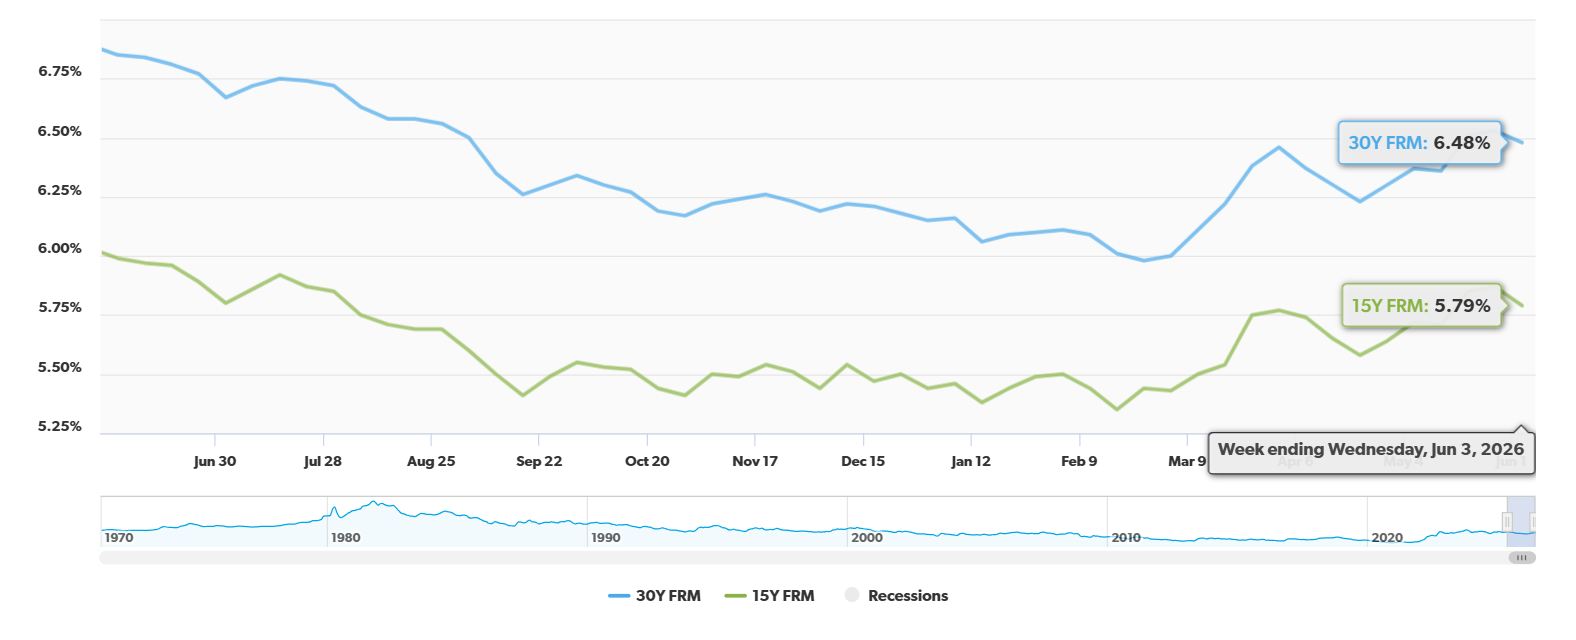
The latest numbers from Freddie Mac are certainly encouraging for anyone dreaming of homeownership. For the week ending June 4, 2026, the average rate for a 30-year fixed mortgage landed at 6.48%. This is a significant 37 basis point drop from where we were a year ago. And looking at the most immediate data, that rate also saw a slight dip of 0.05% just in the last week.

This combination of year-over-year and weekly improvement is more than just a number; it’s a tangible boost to affordability for many potential homeowners. This dip, while perhaps not a dramatic plunge, is a welcome breath of fresh air. It’s the kind of movement that can tip the scales for someone who’s been on the fence, or help make a move possible for those who thought they couldn't afford it.

30-Year Fixed Mortgage Rate is Down by 37 Basis Points Year-Over-Year

What Does This Rate Drop Really Mean for You?

Let’s break down what this 37 basis point (which is the same as 0.37%) drop actually signifies. Freddie Mac's Primary Mortgage Market Survey (PMMS) is the gold standard for tracking these rates, and their data shows that the average 30-year fixed-rate mortgage was at 6.85% for the same week in 2025. Fast forward a year, and we're now at 6.48%.

On the surface, that might not seem like a huge difference, but when you're talking about a loan that lasts 30 years, even small percentage points add up. My experience tells me that people often underestimate the power of these seemingly minor rate changes, especially when considering the long-term financial impact.

30-Year Fixed Mortgage Rate is Down by 37 Basis Points Year-Over-Year
Freddie Mac

Calculating the Savings: A Look at the Numbers

To really understand the impact, let's look at a common scenario. Imagine you're taking out a $400,000 mortgage.

  • Last Year (at 6.85%): Your monthly principal and interest payment would have been approximately $2,621.04.
  • This Year (at 6.48%): Your monthly payment drops to about $2,523.01.

That's a saving of nearly $98.03 per month. Now, $98 might not sound like life-changing money on its own, but over the course of a 30-year loan, that adds up to a staggering $35,290.80 in total savings on interest alone! That’s a significant chunk of change that can go towards other financial goals, home improvements, or simply provide a little more breathing room in your budget.

Here's a table showing how this savings plays out for different loan amounts:

Home Loan Amount 2025 Payment (6.85%) 2026 Payment (6.48%) Monthly Savings 30-Year Lifetime Savings
$300,000 $1,965.78 $1,892.26 $73.52 $26,467.20
$400,000 $2,621.04 $2,523.01 $98.03 $35,290.80
$500,000 $3,276.30 $3,153.77 $122.53 $44,110.80

As you can see, the larger your loan, the more significant the savings become.

Beyond the 30-Year Fixed: Other Rates to Consider

While the 30-year fixed is the most popular for its predictable payments, it's worth noting how other mortgage products are performing. The 15-year fixed-rate mortgage, a great option for those looking to pay off their home faster and save more on interest, has also seen a dip. For the week ending June 4, 2026, it averaged 5.79%, down from 5.87% the previous week. Year-over-year, this is a 20 basis point decrease from 5.99% in 2025.

Here’s a quick snapshot from Freddie Mac:

Mortgage Type Week Ending 06/04/2026 Previous Week Year-over-Year Change
30-Yr FRM 6.48% 6.53% -0.37%
15-Yr FRM 5.79% 5.87% -0.20%

This tells me that the broader trend is one of moderating interest rates, which is generally positive for the housing market.

Why Are Rates Moving Down? The Economic Picture

According to Sam Khater, Chief Economist at Freddie Mac, this slight drop into the mid-6% range is offering some much-needed breathing room for homebuyers. He points out that national income growth is currently outpacing home price appreciation. This is a critical factor for affordability. When your paycheck grows faster than the cost of the house, it makes buying a home feel more achievable.

It’s not just Freddie Mac's numbers telling this story. Broader affordability indexes, like the First American Real House Price Index (RHPI), are also showing that these lower year-over-year rates are contributing to modest affordability gains in major U.S. cities. This suggests a more widespread, albeit gradual, improvement in the housing market's accessibility.

Looking ahead, forecasts from organizations like the Mortgage Bankers Association (MBA) suggest that these 30-year rates are likely to fluctuate between 6.1% and 6.3% for the rest of 2026. This prediction is based on the expectation that inflation pressures will continue to stabilize, which is a good sign for borrowers.

My Take: A Balanced Outlook for Buyers

From my perspective, this is a really encouraging development for anyone considering buying a home. The combination of slightly lower mortgage rates and rising incomes creates a more favorable environment than we've seen in some time. It’s important to remember that the housing market is complex, and many factors influence prices and rates. However, this move downwards in mortgage rates is a significant positive signal.

It's not a time for wild speculation, but rather a moment for thoughtful consideration. If you've been waiting for a better opportunity to enter the housing market, now might be the time to start seriously exploring your options. Getting pre-approved for a mortgage and speaking with a trusted real estate agent can give you a clearer picture of what you can afford in today's market.

The fact that rates have decreased by 37 basis points year-over-year on the 30-year fixed mortgage is a clear indication that the market is responding to economic conditions in a way that benefits borrowers. It’s a gentle nudge in the right direction, making that dream home feel a little closer and a lot more affordable.

🏡 Rental Real Estate Investment: Indiana vs Florida

Indianapolis, IN
🏠 Property: Balboa Dr
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1925 sqft
💰 Price: $190,000 | Rent: $1,600
📊 Cap Rate: 8.1% | NOI: $1,277
📅 Year Built: 1963
📐 Price/Sq Ft: $99
🏙️ Neighborhood: C+

VS

Port Charlotte, FL
🏠 Property: Tyler Ave
🛏️ Beds/Baths: 4 Bed • 2 Bath • 1617 sqft
💰 Price: $274,900 | Rent: $1,845
📊 Cap Rate: 5.4% | NOI: $1,231
📅 Year Built: 2023
📐 Price/Sq Ft: $171
🏙️ Neighborhood: A+

Out‑of‑State investors can compare Indiana’s affordable rental with higher cap rate vs Florida’s newer A+ property with stability. Which fits YOUR investment strategy?

We have much more inventory available than what you see on our website – Let us know about your requirement.

📈 Choose Your Winner & Contact Us Today!

Speak to a Norada Investment Counselor (No Obligation):

(800) 611-3060

View All Properties

Build Passive Income & Wealth with Turnkey Rentals

Mortgage rates remain near 6%, but rental properties continue to deliver strong cash flow and appreciation. Savvy investors know that turnkey real estate is the path to passive income and long‑term wealth.

Norada Real Estate helps you secure turnkey rental properties designed for immediate cash flow and appreciation—so you can invest smartly regardless of interest rate trends.

🔥 HOT INVESTMENT Properties JUST ADDED! 🔥
Request a Callback / Fill Out the Form Online

Contact Us

Also Read:

  • Will Mortgage Rates Drop to 5% in 2026: Expert Forecast
  • How to Get a 3% Mortgage Rate in 2026 With Assumable Mortgages?
  • How to Get a 4% Interest Rate on a Mortgage in 2026?
  • What Leading Housing Experts Predict for Mortgage Rates in 2026
  • Mortgage Rate Predictions for 2026: What Leading Forecasters Expect
  • Mortgage Rate Predictions for the Next 3 Years: 2026, 2027, 2028
  • 30-Year Fixed Mortgage Rate Forecast for the Next 5 Years
  • 15-Year Fixed Mortgage Rate Predictions for Next 5 Years: 2025-2029
  • Will Mortgage Rates Ever Be 3% Again in the Future?
  • Mortgage Rates Predictions for Next 2 Years
  • Mortgage Rate Predictions for Next 5 Years
  • Mortgage Rate Predictions: Why 2% and 3% Rates are Out of Reach
  • How Lower Mortgage Rates Can Save You Thousands?
  • How to Get a Low Mortgage Interest Rate?
  • Will Mortgage Rates Ever Be 4% Again?

Filed Under: Financing, Mortgage Tagged With: 30-Year Fixed Mortgage Rate, mortgage, mortgage rates

  • « Previous Page
  • 1
  • …
  • 21
  • 22
  • 23
  • 24
  • 25
  • …
  • 156
  • Next Page »

Real Estate

  • Birmingham
  • Cape Coral
  • Charlotte
  • Chicago

Quick Links

  • Markets
  • Membership
  • Notes
  • Contact Us

Blog Posts

  • Today’s Mortgage Rates, September 15: 30-Year Fixed Crosses 7% for the First Time in 2026
    September 15, 2026Marco Santarelli
  • Mortgage Rates Today, September 15, 2026: 30-Year Refinance Rate Rises by 24 Basis Points
    September 15, 2026Marco Santarelli
  • Where to Keep Your Money During a Fed Rate Hike
    September 14, 2026Marco Santarelli

Contact

Norada Real Estate Investments 30251 Golden Lantern, Suite E-261 Laguna Niguel, CA 92677

(949) 218-6668
(800) 611-3060
BBB
  • Terms of Use
  • |
  • Privacy Policy
  • |
  • Testimonials
  • |
  • Suggestions?
  • |
  • Home

Copyright 2018 Norada Real Estate Investments

Loading...