The Fed rate hike countdown is no longer a vague macro story. The FOMC’s two-day meeting started Tuesday, September 15, 2026, and the policy decision lands Wednesday, September 16 at 2:00 p.m. ET, with the chair’s press conference shortly after. Markets are pricing roughly a 90% chance of a 25 basis-point increase that would lift the federal funds target range toward 3.75%–4.00% — the first hike since mid-2023 if it arrives as expected.
That matters for stocks and mortgages, sure. For cash savers, the more practical race is quieter: online banks, brokerage funding queues, and Treasury auction workflows get jammed the moment a widely telegraphed decision hits. If you already planned to open a high-yield savings account (HYSA) or buy short-term Treasury bills, doing the setup before Wednesday’s announcement can help you beat digital traffic and lock today’s available rates while competitors are still refreshing news apps.
Fed Rate Hike Countdown: 3 Cash Moves to Lock In Before Wednesday's Decision
Here are 3 cash moves worth executing on the countdown clock — focused on parking money, not predicting every word from the press conference.
- Move 1: Open and fund an HYSA while apps are still responsive
- Move 2: Buy short-term Treasuries before post-decision traffic
- Move 3: Sweep idle checking cash today so funding delays don’t strand you
The rate backdrop in one glance
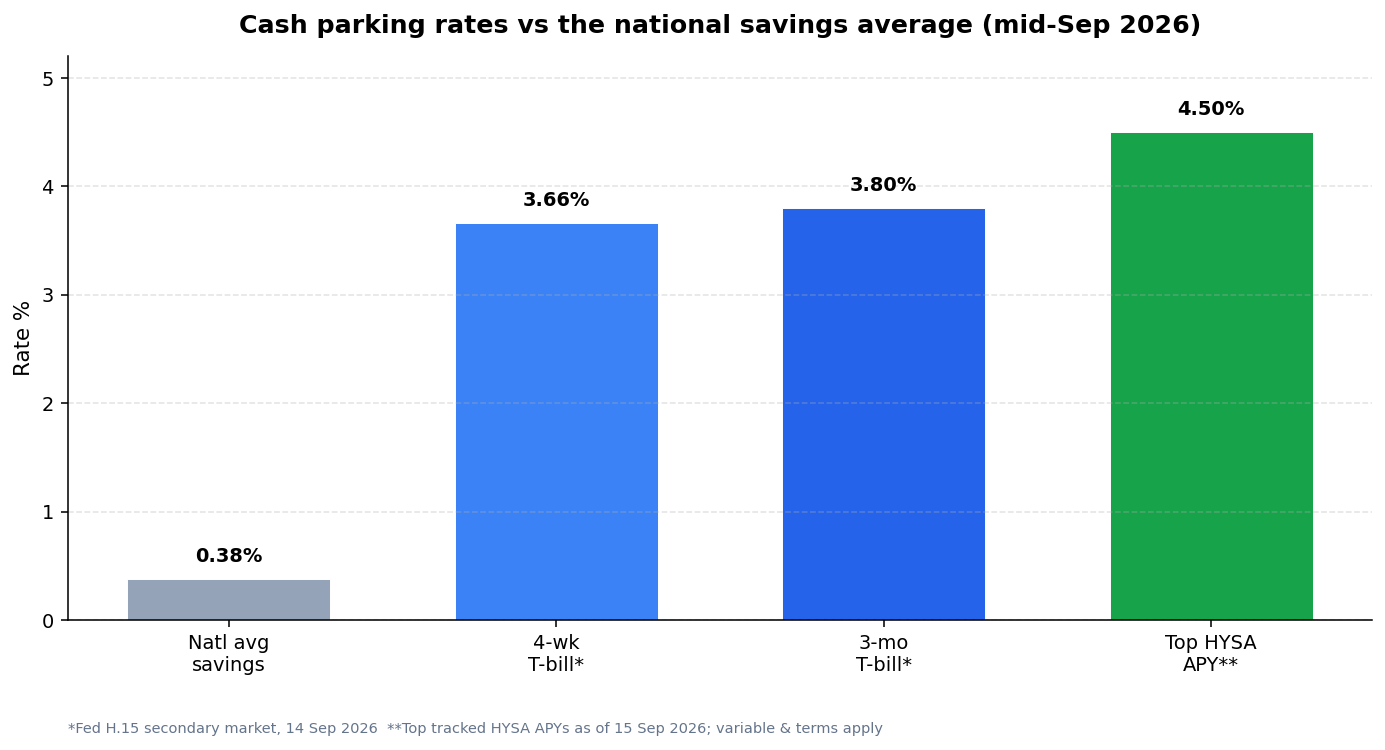
As of mid-September 2026, cash still pays far more in competitive online accounts and bills than in a typical brick-and-mortar savings balance. Top tracked HYSA offers are still printing roughly up to about 4.50% APY (terms and balance caps vary), while the FDIC national savings average sits near 0.38%. On the Treasury side, recent Fed H.15 secondary-market prints (as of September 14) showed about 3.66% on 4-week bills and about 3.80% on 3-month bills.
| Cash parking option | Recent rate signal | Liquidity | Best for |
|---|---|---|---|
| Typical savings (national avg) | ~0.38% APY | High | Convenience only |
| Competitive HYSA | Up to ~4.00%–4.50% APY* | High | Emergency + near-term cash |
| 4-week T-bill (secondary) | ~3.66%* | Short hold / sellable | Money you can park briefly |
| 3-month T-bill (secondary) | ~3.80%* | Known maturity | Cash with a date attached |
*HYSA APYs are variable and offer-specific as of Sept. 15, 2026 tracking. T-bill figures are approximate secondary-market rates from the Sept. 14, 2026 H.15 release. Always verify live quotes before you move money.
Move 1: Open (and fund) a high-yield savings account before Wednesday’s rush
An HYSA is still the simplest “cash upgrade” for money you may need in days or weeks. The Fed rate hike countdown creates a weird operational risk: even when banks do not instantly cut APYs the minute a statement drops, account-opening and ACH funding traffic spike as headlines go viral on Discover and social feeds.
Do this today while the decision is still pending:
- Pick an FDIC-insured HYSA and read the fine print on balance tiers, direct-deposit rules, and promo windows
- Complete identity verification now — do not wait until Wednesday afternoon
- Initiate the ACH transfer from checking so funds are already in motion
- Turn on alerts for rate changes and balance thresholds
Why timing helps: Variable APYs can move after policy shifts, but the bigger near-term pain for many households is friction — frozen apps, delayed micro-deposits, or transfers that miss a statement-day funding window. Opening before the announcement is less about “beating the Fed” and more about beating other shoppers to a clean onboarding lane.
Quick HYSA shopping checklist:
- APY on the balance size you actually keep (not just the headline teaser)
- Monthly fees and waiver rules
- Withdrawal limits / transfer speed back to checking
- Whether the top rate requires a bundled checking account
| HYSA question | Why it matters before Wednesday |
|---|---|
| Is the top APY capped at a low balance? | A 4.50%-style teaser on a small vault may not fit a full emergency fund |
| Do you need direct deposit? | Payroll timing can delay your “funded” status past decision day |
| How fast is outbound ACH? | Cash is only useful if you can pull it when a bill hits |
Move 2: Buy short-term Treasury bills before the post-decision crush
Short-term Treasuries are the other core cash tool in a Fed rate hike countdown. Bills can lock a known yield to maturity (if held), carry strong credit quality, and — via TreasuryDirect or a brokerage — give you a parking spot that is not sitting at 0.01% in a legacy savings account.
Recent secondary-market levels near 3.6%–3.9% across very short tenors are still meaningful versus average bank savings, even if they trail the flashiest HYSA teasers. The strategic point for this week is operational: auction calendars, brokerage cash desks, and first-time TreasuryDirect enrollments get noisy when a hike is the national story.
A practical pre-Wednesday T-bill plan:
- Decide the cash horizon: 4 weeks, 8 weeks, 13 weeks, or a small ladder
- Fund the brokerage or TreasuryDirect account before you need to bid
- Prefer settled cash over “pending” transfers on decision day
- If you are new to Treasuries, complete the account paperwork today — not at 1:55 p.m. ET Wednesday
HYSA vs T-bills (simple rule of thumb):
- Choose an HYSA for emergency cash and flexible spending money
- Choose T-bills for cash with a known end date you will not need early
- Use both if you have a larger cash pile — flexibility in one bucket, scheduled cash in the other
| If your cash need is… | Lean toward… | Why |
|---|---|---|
| 0–30 days / unknown | HYSA | Access without maturity planning |
| A known date in 1–3 months | Short T-bill | Yield locked to maturity if held |
| Split goals | HYSA + T-bill ladder | Liquidity plus scheduled rolls |
Move 3: Sweep idle cash out of low-yield checking today
The third move is the one people skip because it feels boring — and it is exactly where money leaks during a news cycle. If thousands of dollars are sitting in a checking account earning next to nothing while you “wait to see what the Fed does,” Wednesday’s statement will not rescue that overnight opportunity cost.
Use the countdown as a forcing function:
- Keep only the checking buffer you truly need for upcoming bills and autopays
- Sweep the surplus into the HYSA or T-bill workflow you set up in Moves 1 and 2
- Confirm transfer limits so a large sweep does not get blocked mid-week
- Screenshot or export your before/after APYs so you can track whether your bank later adjusts rates
This also reduces Wednesday operational risk. If identity checks, bank linking, or micro-deposits are still pending when the announcement hits, your cash can remain stranded in the wrong account while everyone else is doing the same transfers at once.
A simple same-day action plan (Tuesday into Wednesday)
- Morning: Choose HYSA + decide T-bill tenor; start account opening if not done
- Afternoon: Initiate ACH / brokerage funding; keep a checking buffer for bills
- Evening: Verify pending transfers and document current APYs
- Wednesday before 2 p.m. ET: Avoid starting brand-new KYC if you can; finish only what is already in progress
- After the statement: Re-check HYSA APYs and bill quotes — adjust later if needed, but do not let “waiting for clarity” become a week of 0% cash
What the Fed decision changes — and what it does not
A Wednesday hike would confirm the policy pivot markets already largely expect. It may eventually pressure some variable deposit rates, and it will dominate headlines around mortgages, credit cards, and risk assets. It does not change the basic household math of this week:
- Leaving cash in a near-zero savings account is still expensive versus competitive HYSAs
- Short Treasuries still offer a clean, dated parking spot for money you will not spend tomorrow
- The bottleneck for many savers is not intelligence — it is account setup speed under digital traffic
So treat the Fed rate hike countdown as a deadline for operations. If you were going to open the HYSA or buy the bills anyway, doing it before Wednesday’s decision is how you stay ahead of the crowd, lock in the rates available today, and keep your cash working while the press conference runs.
The Fed’s rate decisions can create market volatility, but turnkey rentals continue to deliver reliable cash flow and appreciation. Investors in 2026 are focusing on real estate as a hedge against uncertainty.
Norada Real Estate helps you secure turnkey properties designed for immediate income and long‑term growth—so your portfolio stays strong regardless of Fed policy shifts.
Want to Know More?
Explore these related articles for even more insights:
- How Fed Rate Hikes Affect Your Wallet, Credit Cards, and Loans
- Goldman Sachs and J.P. Morgan Warn of an Imminent Fed Rate Hike This Week
- Fed Interest Rate Decision July 29, 2026: Rates Steady at 3.50-3.75%
- Interest Rate Predictions for the Next 5 Years: 2026-2030
- J.P. Morgan Predicts No Fed Rate Cuts Before 2027 as Inflation Persists
- Fed Interest Rate Predictions for the Next 3 Years: 2026-2028
- The Fed After Jerome Powell: Who Could Drive Rate Cuts in 2026?
- Why Your Loan Payment Isn’t Budging Despite Recent Fed Rate Cut
- How Does the Recent Fed Rate Cut Impact Your Personal Finances
- Fed Interest Rate Forecast for the Next 12 Months